Lab check #2. "40% winners at 1:3": everyone quotes it. Math answers it before any backtest.
The risk rule in this post is sound: isolated margin, $10 at risk on $1,000. The 40% is the problem.
If price has no direction, a stop 1 step away is mathematically hit 3 times more often than a take 3 steps away. At 1:3 that's 25% winners, at 1:1 it's 50%. R:R doesn't create an edge: it only sets the break-even win rate. 40% is a wish, not a result.
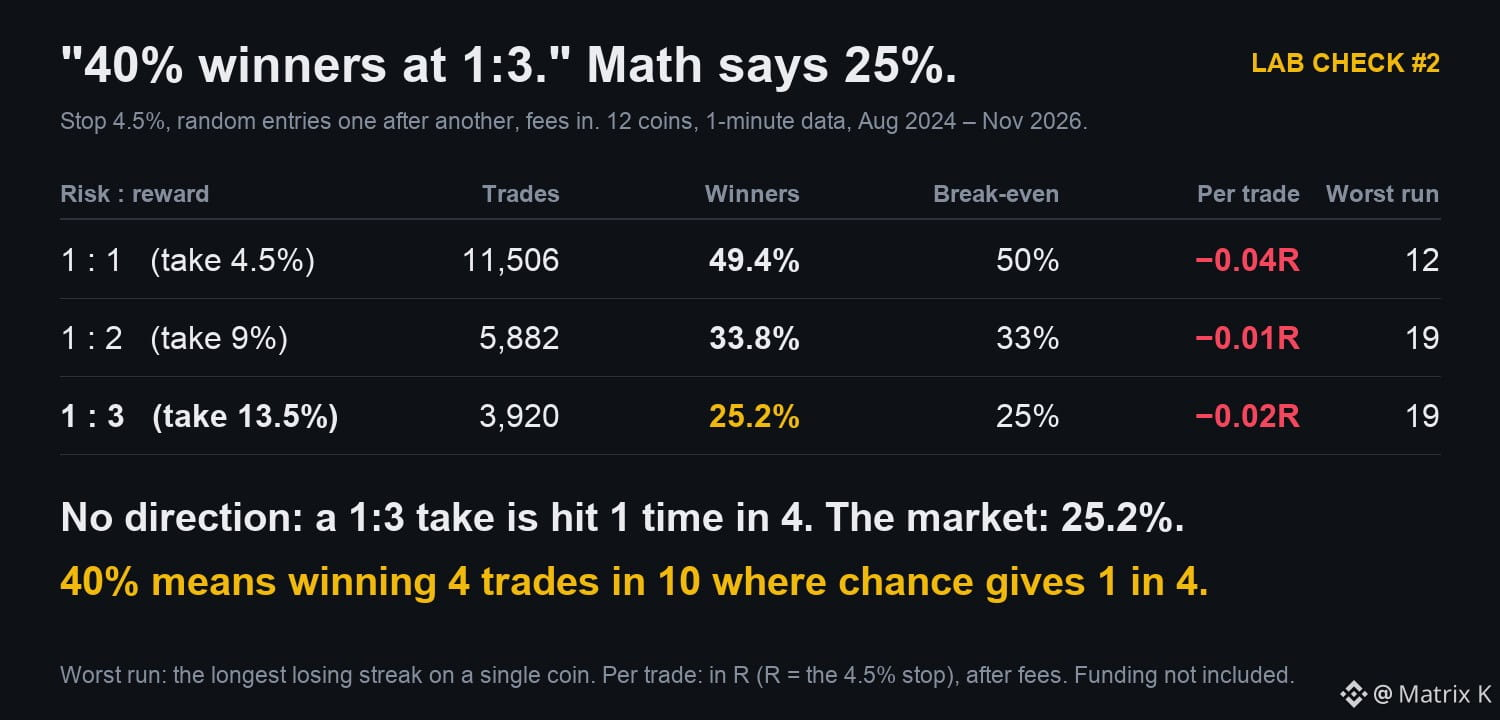
I checked it anyway: 12 coins, including $ADA $ENA $AVAX , 1-minute data, Aug 2024 to Nov 2026. Stop 4.5%, take 13.5%, random entries, fees in. 3,920 trades, 25.2% winners. 1:1 gave 49.4%, 1:2 gave 33.8%. The market agrees with the math, and fees push it below zero.
So 40% at 1:3 isn't a rule. It means winning 4 trades in 10 where chance gives 1 in 4. The best entry I've measured, with an ATR stop, won about 3 in 10.
And the losing runs: up to 19 in a row on one coin.
Where does your win rate come from?
#RiskManagement #trading
The risk rule in this post is sound: isolated margin, $10 at risk on $1,000. The 40% is the problem.
If price has no direction, a stop 1 step away is mathematically hit 3 times more often than a take 3 steps away. At 1:3 that's 25% winners, at 1:1 it's 50%. R:R doesn't create an edge: it only sets the break-even win rate. 40% is a wish, not a result.
I checked it anyway: 12 coins, including $ADA $ENA $AVAX , 1-minute data, Aug 2024 to Nov 2026. Stop 4.5%, take 13.5%, random entries, fees in. 3,920 trades, 25.2% winners. 1:1 gave 49.4%, 1:2 gave 33.8%. The market agrees with the math, and fees push it below zero.
So 40% at 1:3 isn't a rule. It means winning 4 trades in 10 where chance gives 1 in 4. The best entry I've measured, with an ATR stop, won about 3 in 10.
And the losing runs: up to 19 in a row on one coin.
Where does your win rate come from?
#RiskManagement #trading