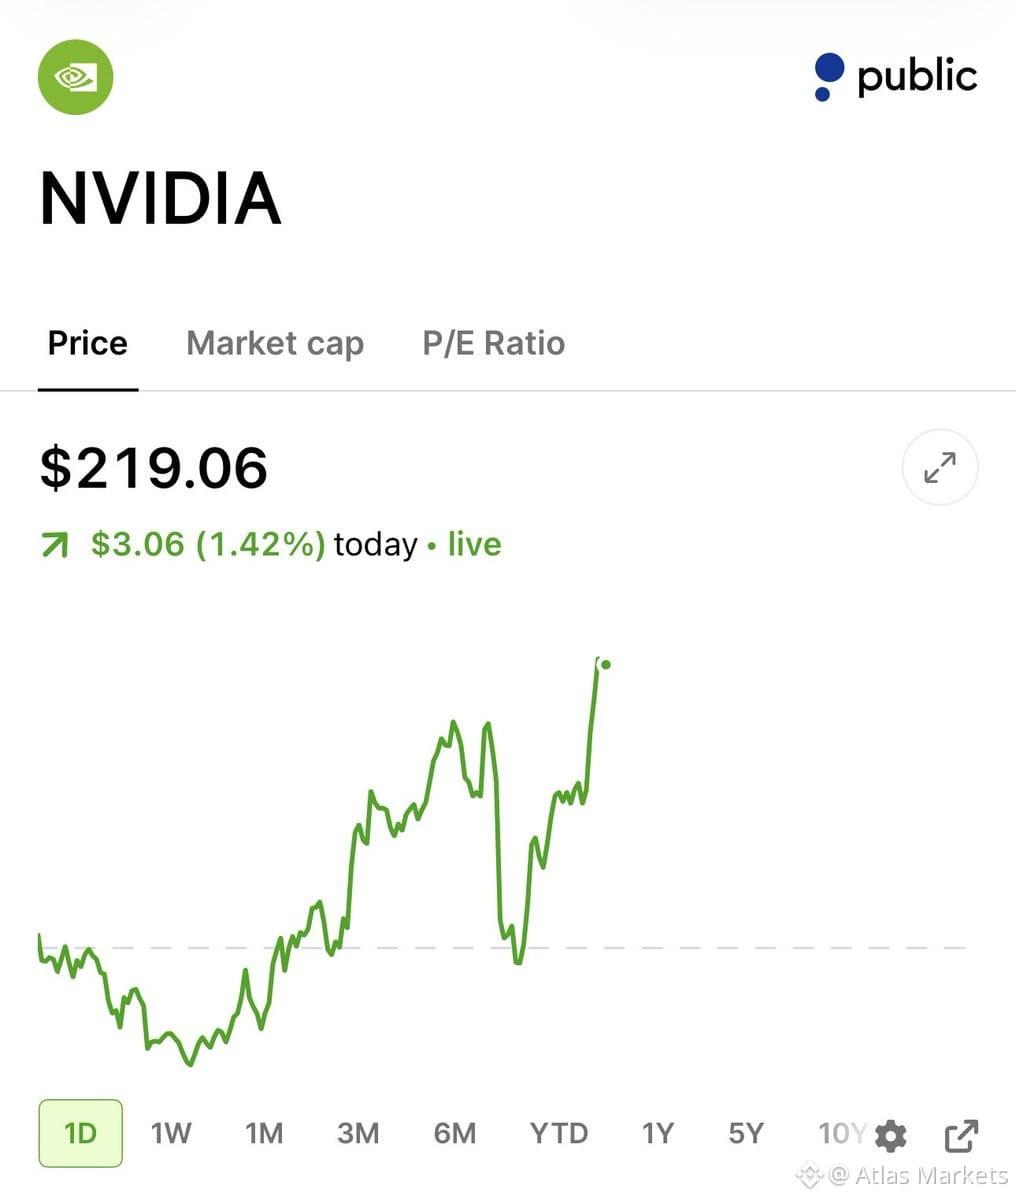
Someone's paying $730 to lock in the right to sell $NVDA at $200 by mid-January 2027. Stock's at $219 now. That's a cash-secured put—sell the $200 strike expiring Jan 15, 2027, pocket $730 upfront, and set aside $20k in case assignment happens.
Two outcomes:
1. $NVDA stays above $200 through expiry. Put expires worthless, you keep the $730. That's 3.7% on $20k in 80 days, roughly 17% annualized.
2. $NVDA drops below $200. You buy 100 shares at $200, but the premium drops your effective cost to $192.68—about 12% below current price.
Nvidia reports earnings before January, which explains the fat premium. Volatility = option juice.
Risk: if $NVDA tanks well below $192.68, you're underwater vs. spot. Only sell puts on names you actually want to own at that strike. This is a bullish-to-neutral trade with defined downside exposure.
Not advice—just the mechanics.