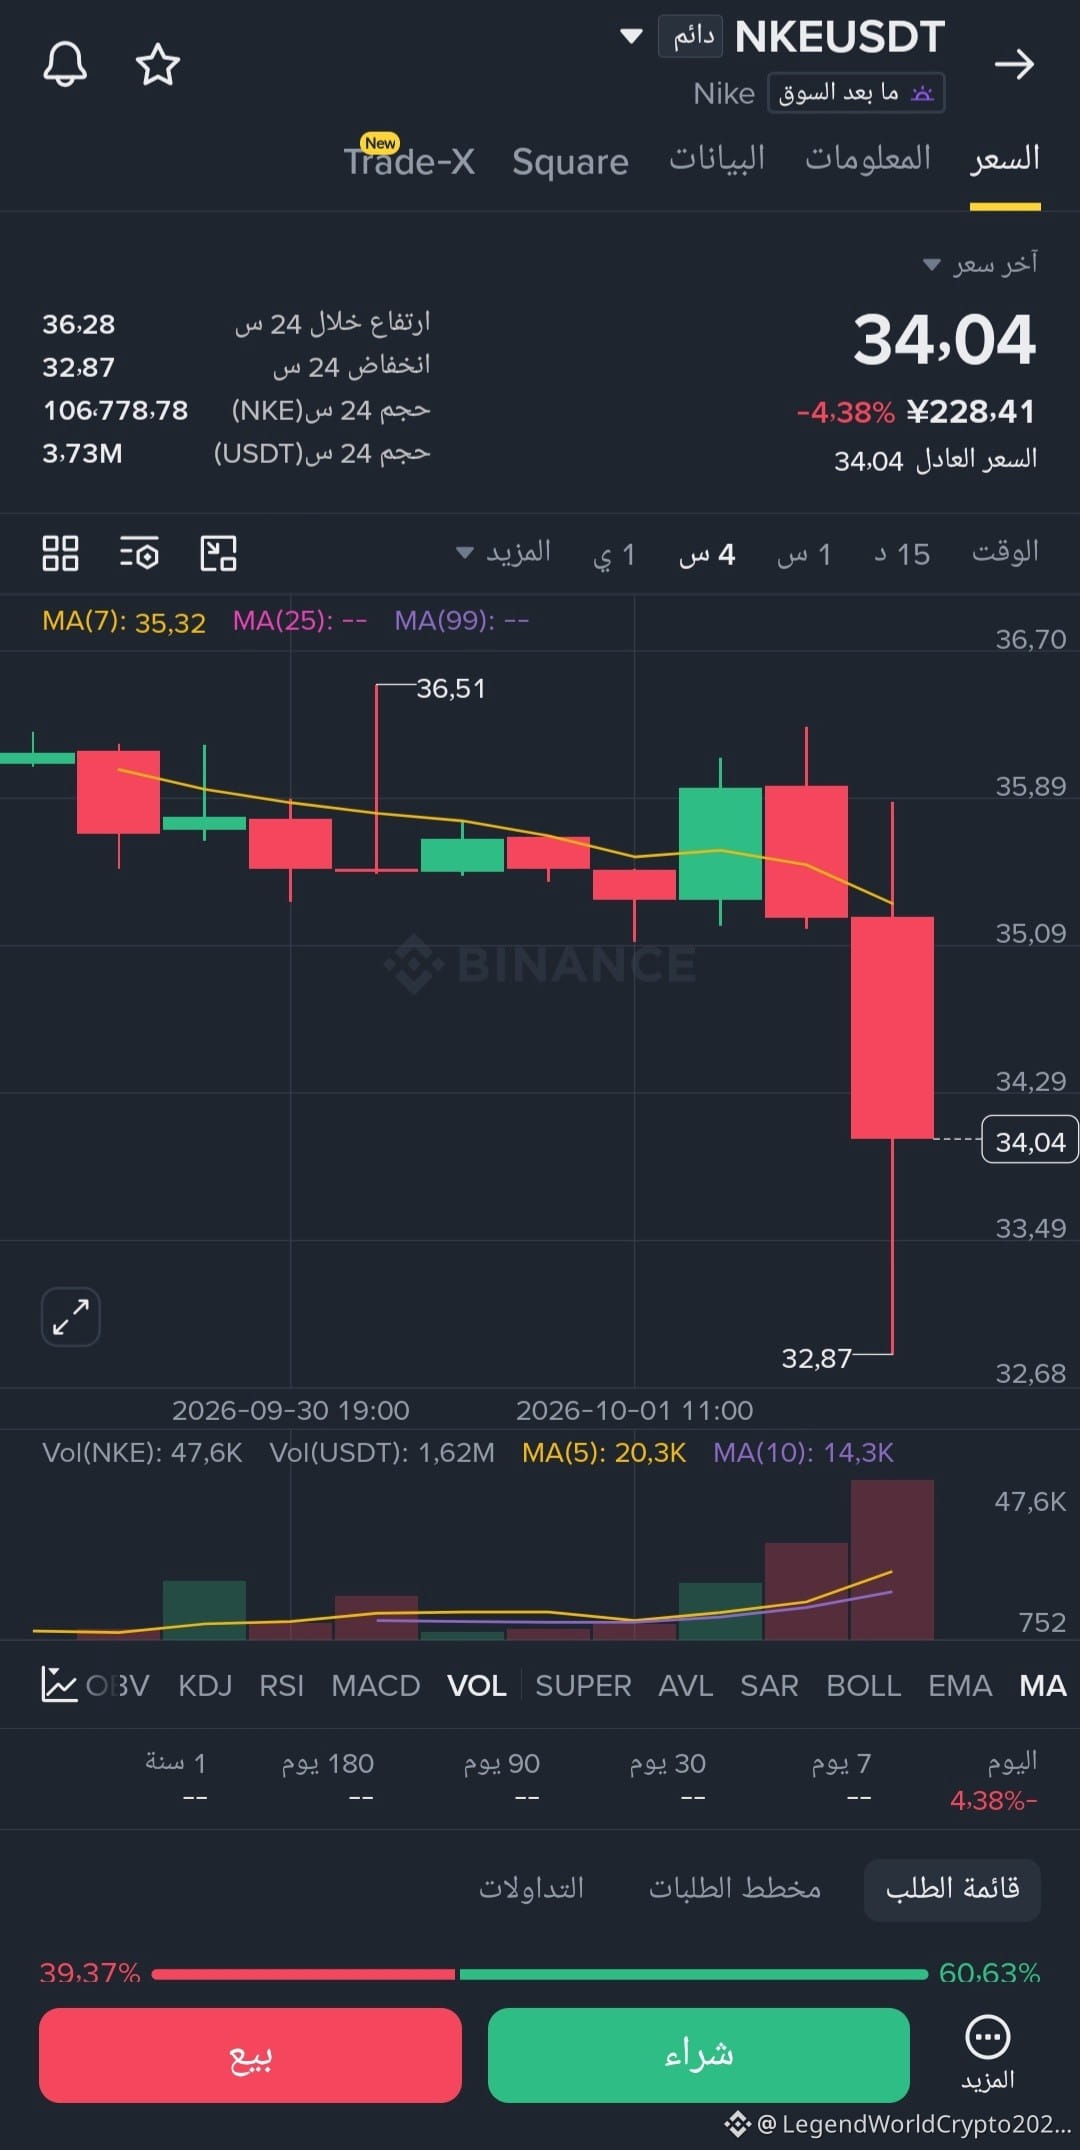
Nike is still lagging, isn't it—despite a few bright spots.
Earnings came in slightly better than expected—48 pence per share versus the anticipated 43 pence.
However, top-line revenue missed expectations, hitting $11.2 billion against a forecast of $11.32 billion—a 4% year-over-year decline.
Direct sales are truly struggling, down 8%, and digital sales took a major hit, dropping 13%. China also performed dismally, with a massive 22% decline.
$NKE
The worst part is the outlook, mate: they project fiscal year 2027 revenue to fall by a high single-digit percentage rather than growing by 2.3%, and EPS is pegged at £1.15–£1.35—far off the expected £1.67.
The stock is down 75% over five years—is anyone going to step in and fix things, or what? 🔍 A deeper look: What is really happening behind the scenes at Nike?
Even with slight earnings beats in certain periods, Nike continues to lag in a sprint won by rising, innovative competitors.
The struggle with direct sales (Nike Direct): With an 8% drop, it is clear that the previous strategy of relying entirely on direct sales—and cutting ties with some traditional retailers—has backfired on the company. Long-term price performance: The stock has faced historic pressure and a severe decline over the past five years, posing a critical question fo
Wait for confirmation of a bullish structure: Don't step in front of a falling train; wait for a double-bottom pattern to form or for a breakout above the downtrend line before establishing long-term investment positions.
Strict risk management: When day trading around earnings news and price swings, strictly adhere to stop-loss orders due to high volatility.
Do you think the new management can revitalize innovation and return Nike to the top, or has the sportswear giant lost market share forever to rising competitors? Share your thoughts below!
$NKE
@NKE GROUP
@LegendWorldCrypto2024
#NKE