

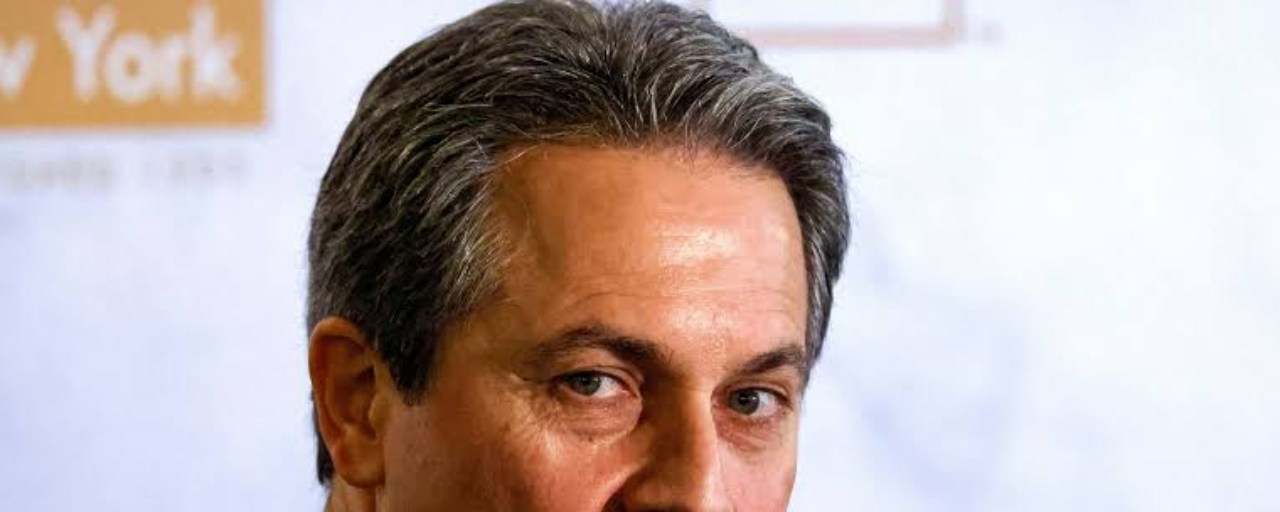
Alberto G. Musalem, President of the Federal Reserve Bank of St. Louis, and a non-voting member of the Federal Open Market Committee (FOMC) in 2026, left no doubt where he stands on easing: the Fed can't cut rates on expected AI productivity, he said, and policy remains somewhat accommodative even after the last rate hike.
He put a number on the inflation problem, saying about half of current inflation comes from persistent demand pressure. He also weakened the case for waiting out price shocks, arguing that the logic of looking through supply shocks falls apart when one shock follows another, which heightens the risk that broader inflation takes root.
Long-run inflation expectations, he added, remain consistent with 2%. He described the US economy as strong, with the labor market in a good place, but stressed that the strength is predicated on continued growth. AI sits at the center of the demand story: the capex boom is generating demand pressure now, while productivity and supply relief have yet to show up. A large part of his message concerned how the Fed talks to the public.
Key Quotes:
Inflation
About half of inflation now is from persistent demand pressure.
Logic of 'looking through' supply shocks weakens when one shock follows another; heightens risk of broader inflation taking root.
Inflation expectations remain consistent with 2% inflation over the long run.
Monetary Policy
Fed can't ease rates based on expected AI productivity.
Monetary policy remains somewhat accommodative even after the last rate hike.
Framework doesn't promise a specific interest rate path.
Growth & Economy
US economic growth is strong, labor market in a good place.
The economy is very strong now, but predicated on continued growth.
AI & Productivity
Right now the AI capex boom is resulting in demand pressure, with productivity and "supply relief" not yet apparent.
Fed Transparency & Accountability
The 'Hall of Mirrors' occurs when the Fed announces a forecast, not a framework.
Delegated power over interest rates also obligates the Fed to explain 'how and why that power is used'.
A predictable, explained framework, is part of what makes a central bank democratically legitimate.
Central bankers needn't make promises, but should tell the public how and why the central bank makes policy decisions.
A central bank that keeps its framework to itself forces market participants to guess at its reaction, rather than focus on data.
Central banks should also avoid 'exiting the conversation altogether', would pose risks in terms of inflation.
If the public understands the framework, private expectations line up with the Fed's intentions, improving trade-offs between inflation and employment.
Fed should communicate how it turns info into policy.
Clear framework helps policy transmission.
The Fed's SEP could be improved by anonymously connecting rate "dots" with economic projections.