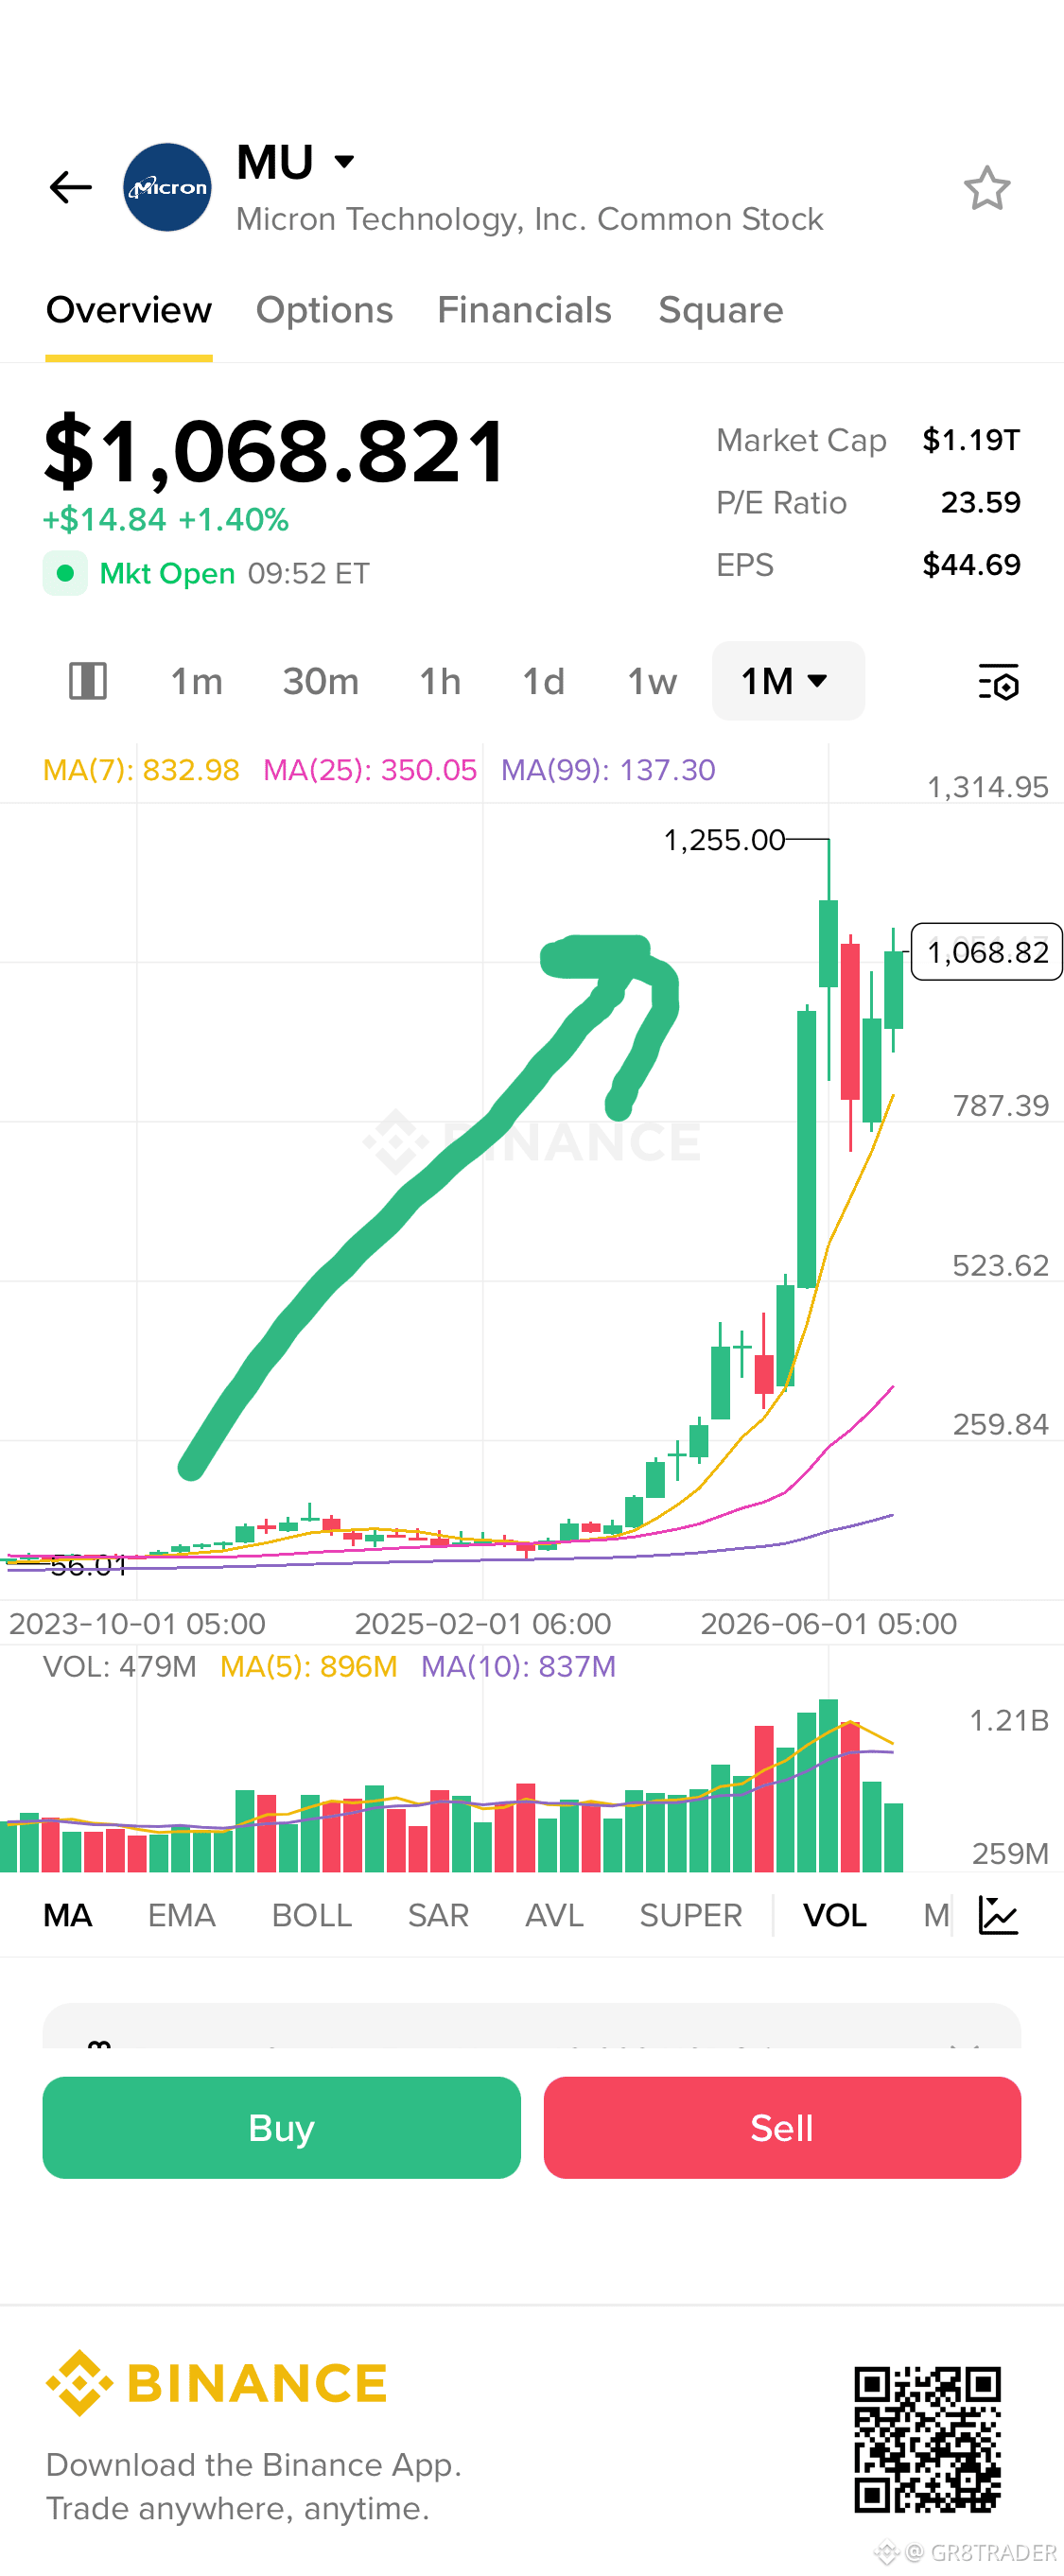
Looking at the numbers heading into $MU 's Q4 report. Guidance pointing around $50B in revenue and ~86% non-GAAP gross margin. High-bandwidth memory (HBM) supply remains constrained globally as AI compute ramps.
Margins crossing 86% is impressive, but for long-term builders, operational execution through supply constraints matters more than a single quarter's peak. Supply-demand dynamics in memory are tight, but cycles always require risk management.
How are you positioning your trade cards before the print? Share your charts below 👇
#EarningsSeason $MU