$MU — Earnings are not only about the headlines
Micron walks into FY2026 Q4 reporting season with exceptionally high expectations.
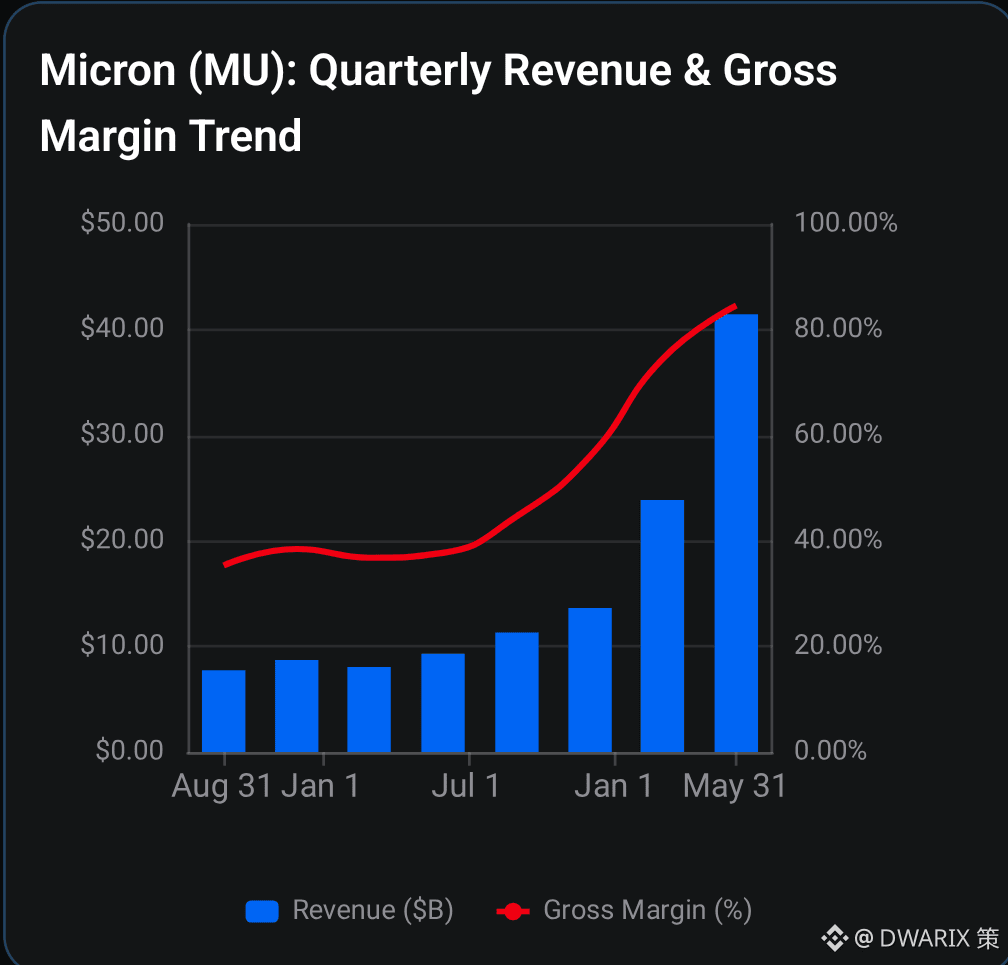
Their revenue guidance of ~$50B and gross margin of ~86% comes on the heels of Q3's sequential jump of ~85% (vs ~35% in Q3) and the question hovering over the industry is if Micron can raise it even further.
The bullish case for Micron is well supported with AI demand, HBM capacity constraints and tight memory supply helping it support pricing. Micron has even said that the industry tightness could persist beyond 2027.
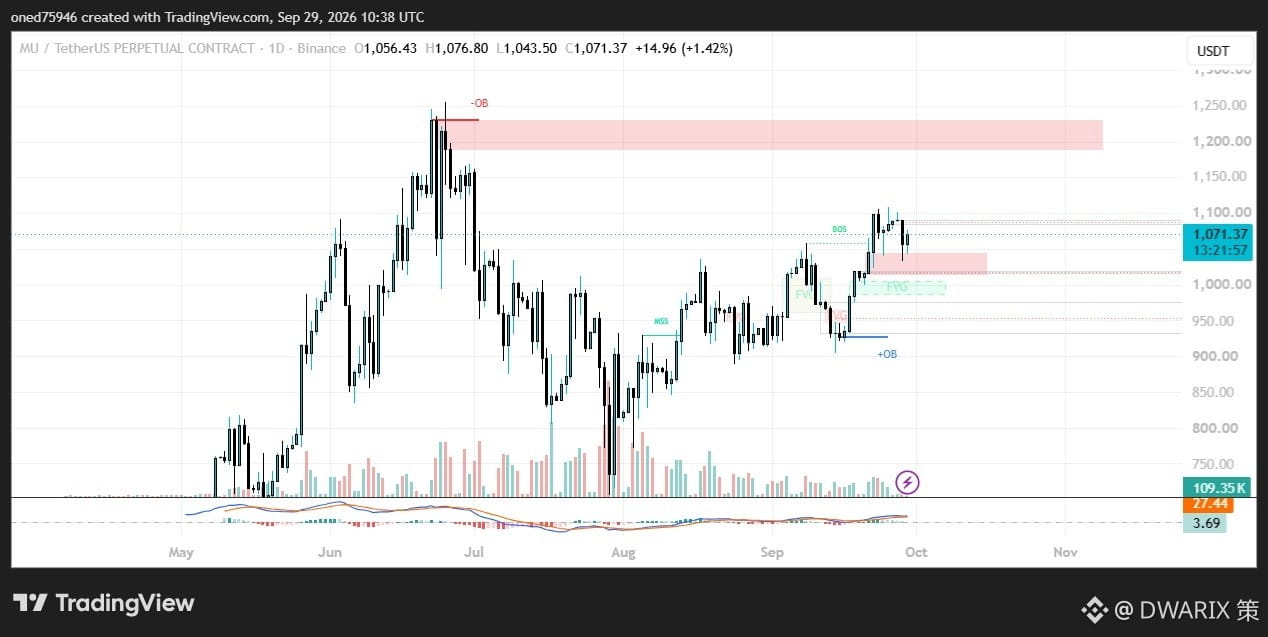
But at this valuation, and with this run-up, "good" might not be good enough.
In my view, 3 numbers matter most:
• Q4 gross margin vs 86%
• Q1 FY27 margin guidance
• FY27 capex + HBM4/HBM4E outlook
If the management is able to keep the margins strong and continue suggesting that there is pricing power, the memory super-cycle thesis is strengthened.
But a sharp rollover in margins would see the stock punished even if they beat estimates.
My view is cautiously bullish but the risks are with the expectations.
#EarningsSeason