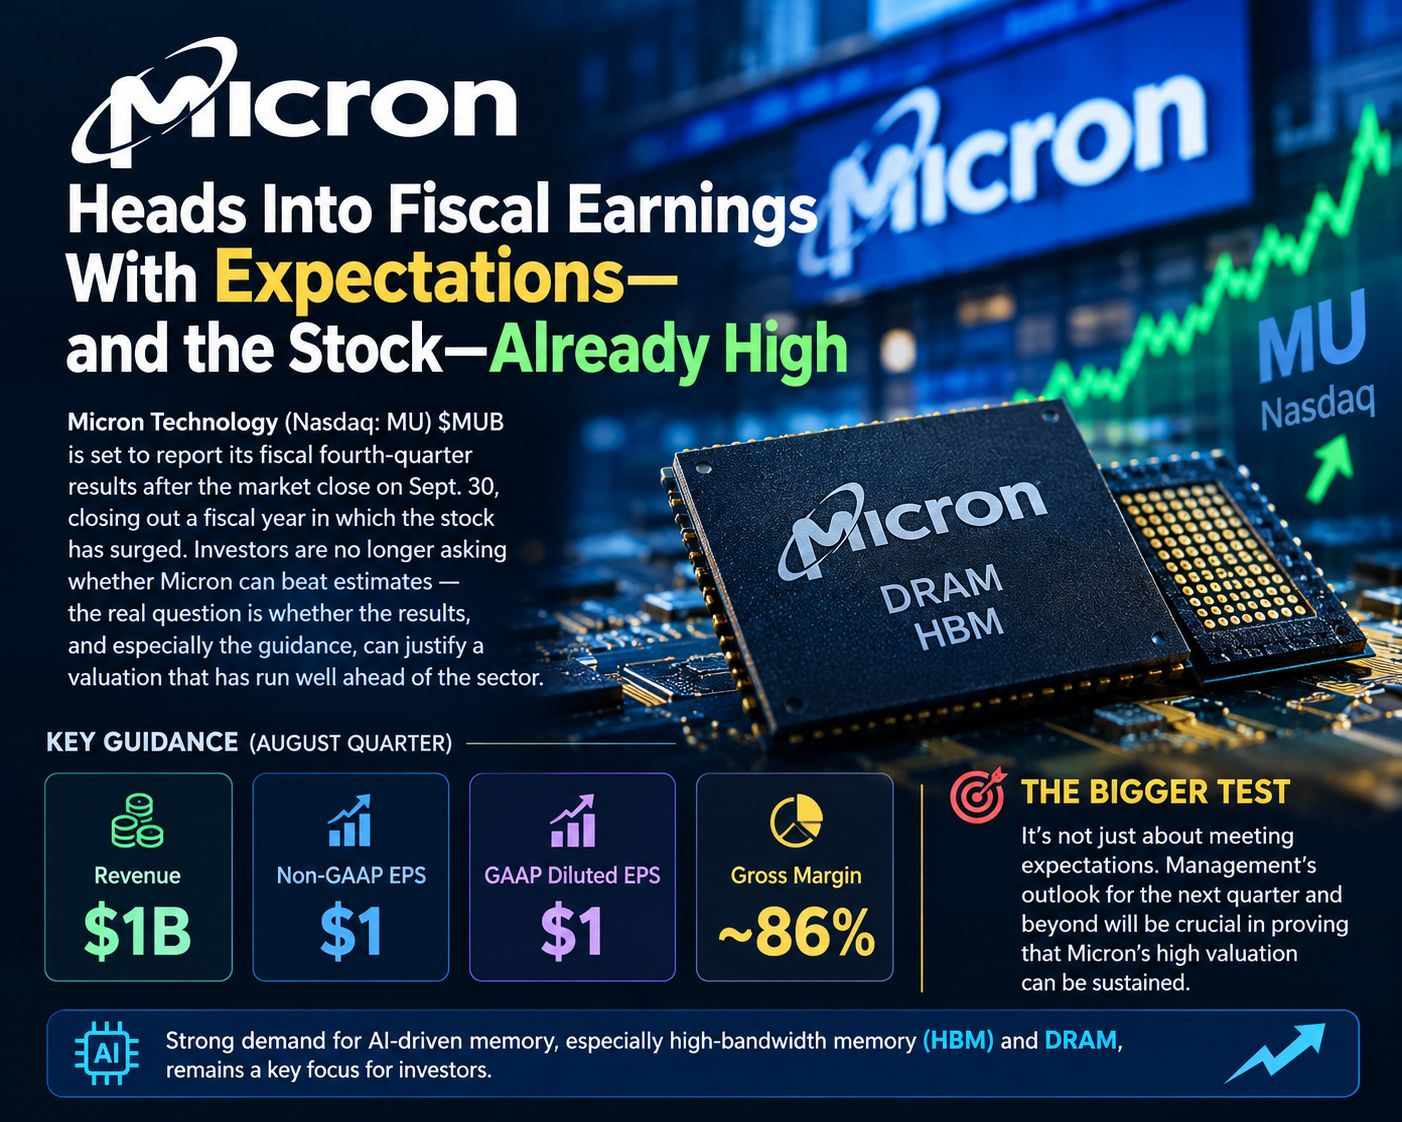
Micron Technology (Nasdaq: MU) $MUB is set to report its fiscal fourth-quarter results after the market close on Sept. 30, wrapping up a fiscal year in which the stock has posted a strong rally. The key question for investors is no longer simply whether the memory maker can beat estimates, but whether its results—and particularly its guidance—can justify a valuation that has moved well ahead of the broader sector.
For the August quarter, Micron guided to revenue of 1 billion; non-GAAP earnings of 1; GAAP diluted earnings of 1; and gross margin of roughly 86%. Wall Street sits at
Put simply, investors are not just expecting Micron to deliver strong results—they are already anticipating them. The bigger test will be whether management’s outlook for the next quarter and beyond can support the company’s elevated valuation following the stock’s strong run.
“The bar is high” means analysts and investors have established demanding expectations for revenue, earnings, and margins. If Micron simply meets those expectations, the market could still interpret the results as disappointing because much of the optimism may already be reflected in the stock price. On the other hand, results or guidance that significantly exceed expectations could strengthen confidence in AI-driven memory demand, particularly for high-bandwidth memory and DRAM.
The figures in the selected excerpt appear incomplete or incorrectly formatted, but the overall message is clear: investors are closely watching Micron’s revenue, adjusted and GAAP earnings per share, and its unusually high gross margin. Gross margin measures the amount of profit remaining after production costs; an 86% margin would indicate exceptionally strong pricing power, while also raising questions about how sustainable those conditions may be.