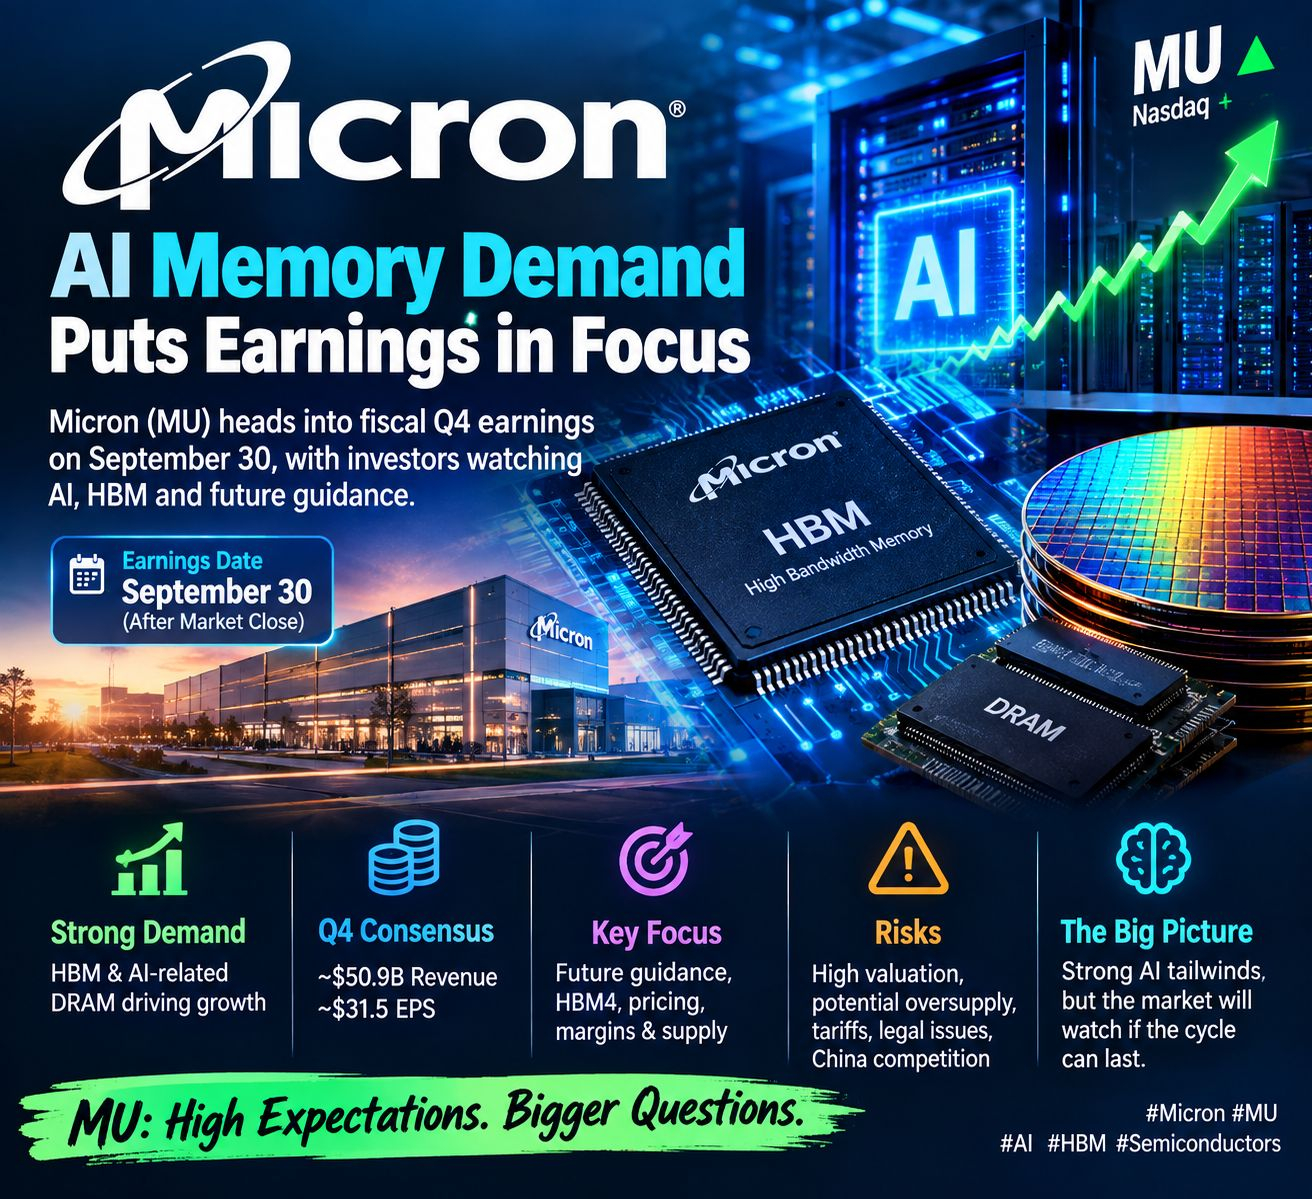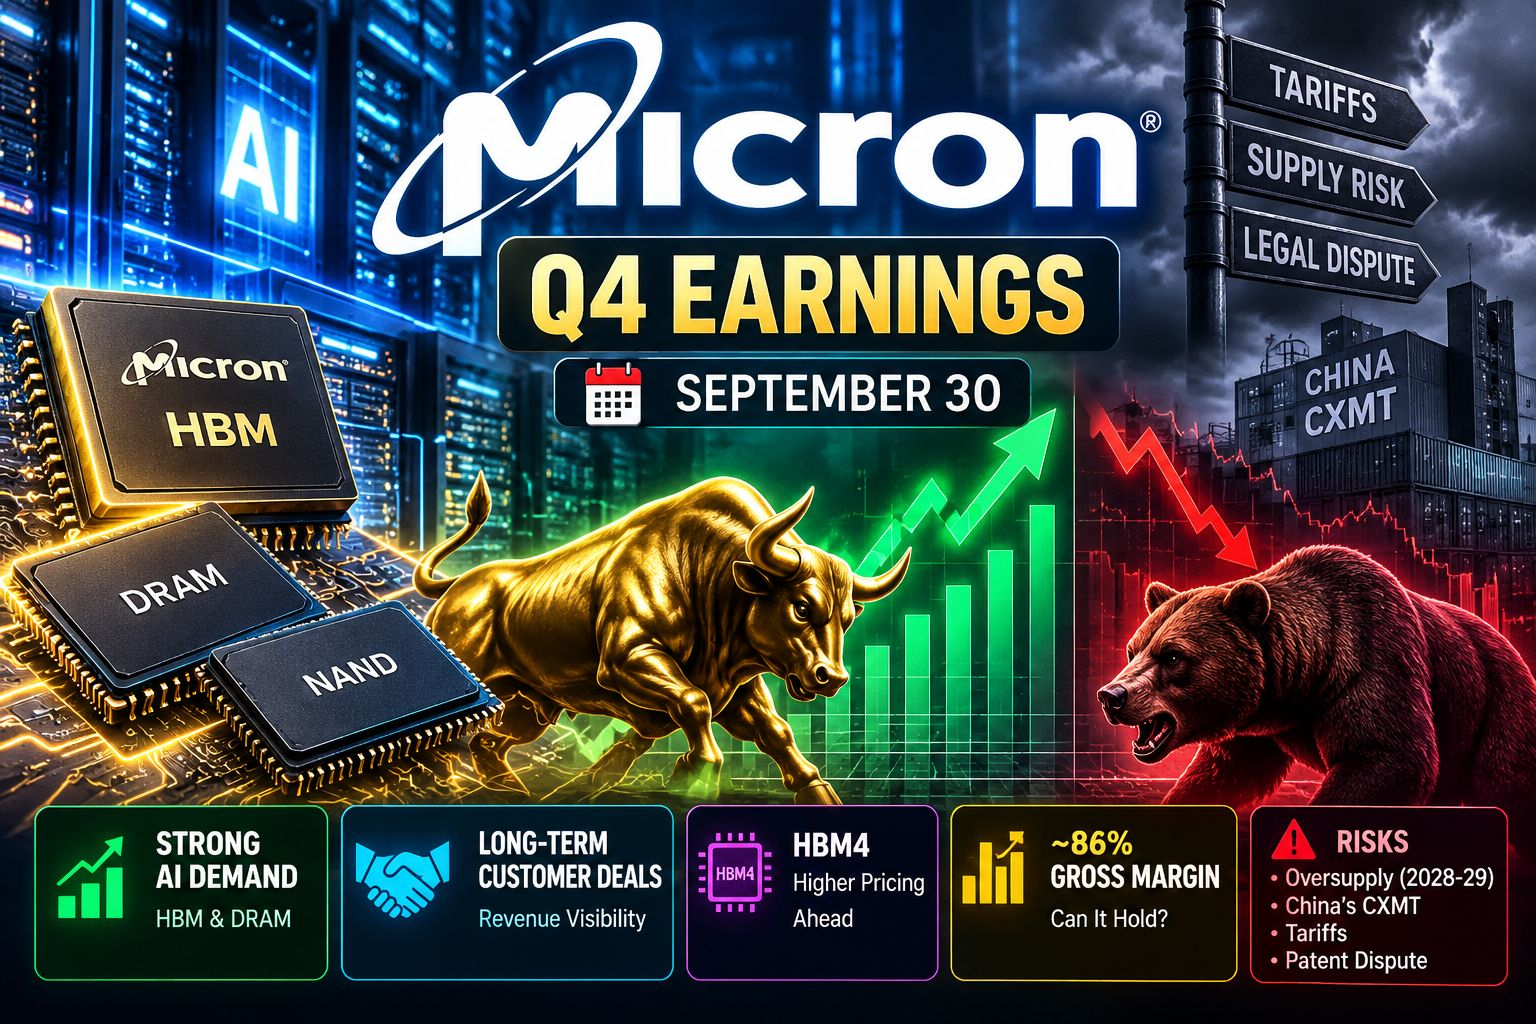
Micron Technology ($MU ) is heading into its fiscal Q4 earnings report on September 30, with investors closely watching the company’s AI-driven memory business. Micron is expected to report after the market close.
The key growth driver is strong demand for advanced memory, especially HBM and AI-related DRAM. Micron’s previous quarter was already very strong, with revenue reaching $41.46 billion and EPS of $25.11.
For Q4, current consensus expectations are around $50.9 billion in revenue and roughly $31.5 EPS. The bigger focus, however, may be future guidance rather than just the reported numbers.
Investors will be watching HBM4 progress, memory pricing, gross margins, AI demand and the company’s outlook for future supply. At the same time, higher valuation and the possibility of future memory oversupply remain important risks.
Overall, MU enters earnings with strong AI-memory demand and high expectations. The September 30 report could provide an important update on whether the current memory cycle is continuing to strengthen or beginning to normalize.
$MU #MU #Micron #AI #Semiconductors #HBM #stocks