

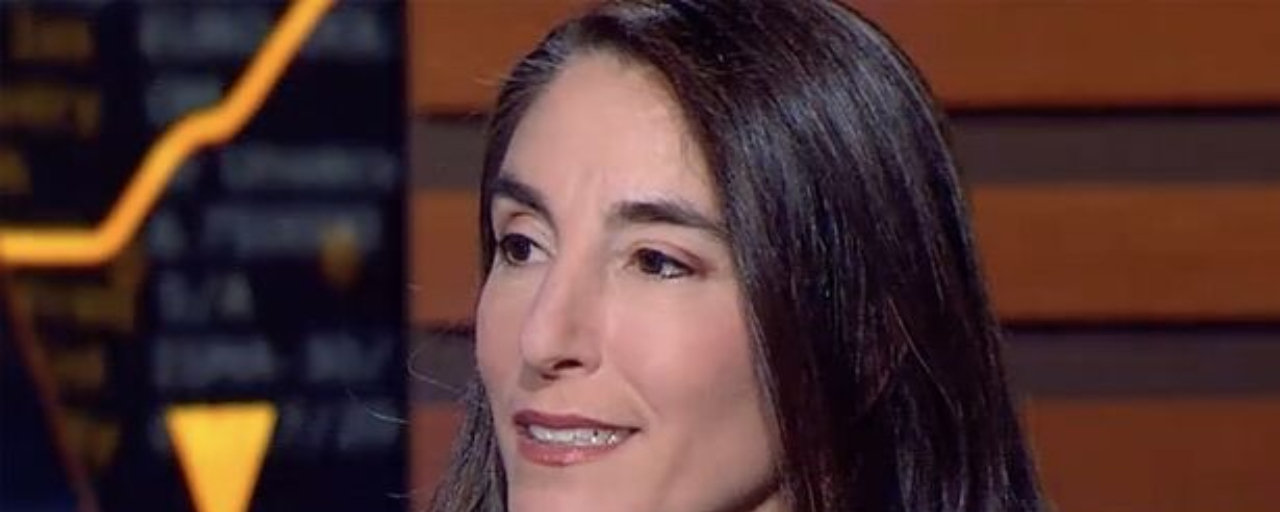

Beth M. Hammack, President of the Federal Reserve Bank of Cleveland and a voting member of the Federal Open Market Committee (FOMC) in 2026 through the rotating seat held by regional Reserve Bank presidents, put inflation psychology at the center of her remarks.
The biggest risk right now, she said, is the formation of an inflationary mindset after an extended stretch of above-target price growth. Persistently high inflation has 'real costs,' she added, pointing squarely at the pressure it puts on wages, and she named consumer spending and capital expenditures as the two forces keeping that pressure alive.
That's why she wants policy held in a restrictive stance — though she was careful to note that, outside of housing, current rates aren't restraining economic activity, and that the different sides of the Fed's mandate are generally not in conflict. She stopped short of committing to a clear path forward, saying the Fed needs flexibility in the current environment, which limits how much guidance it can offer.
On the labor market, Hammack struck a steadier note: growth has held up well and the job market remains stable. Turning to financial conditions, she pointed to a mix of forces behind the recent climb in bond yields — a strong economic outlook, the market's own reaction to Fed and government policy, and AI-driven investment demand pulling from the same pool of capital.
That last point tied into a broader theme, as she flagged plenty of unresolved long-term questions about what AI ultimately means for inflation. She closed with a warning that carried its own weight: the US, she said, is on an unsustainable fiscal path.
Monetary Policy
The Fed needs to make sure policy is at a restrictive stance to lower inflation.
Fed policy is not restraining activity outside of housing.
Sides of the Fed's mandates are generally not in conflict.
Inflation
The biggest risk with inflation is the formation of an inflationary mindset.
The public has been dealing with above-target inflation for an extended period.
Underlying inflation is likely above target.
High inflation complicates economic planning.
Persistently high inflation has 'real costs,' pressures wages.
Worried about demand-related pressure on inflation.
Consumer spending and CAPEX are sources of pressure.
Capital expenditures will pressure inflation for a while.
If we don't make progress lowering inflation, expectations could shift.
Inflation expectations are reasonably well anchored.
Labor Market
Growth has held up well, the job market is stable.
Growth
The US is on an unsustainable fiscal path.
AI & Productivity
There are lots of long-term questions on what AI will mean for inflation.
AI investment demand is competing for investors in the bond market.
Financial Conditions
Rising bond yields driven by a number of factors.
Some of what the bond market is doing is in reaction to the Fed and government policy.
Good economic outlook is pressuring up bond yields.
I am mindful of financial conditions, but the Fed is the decision maker on monetary policy.
Forward Guidance
The Fed needs flexibility in this environment, which limits guidance.