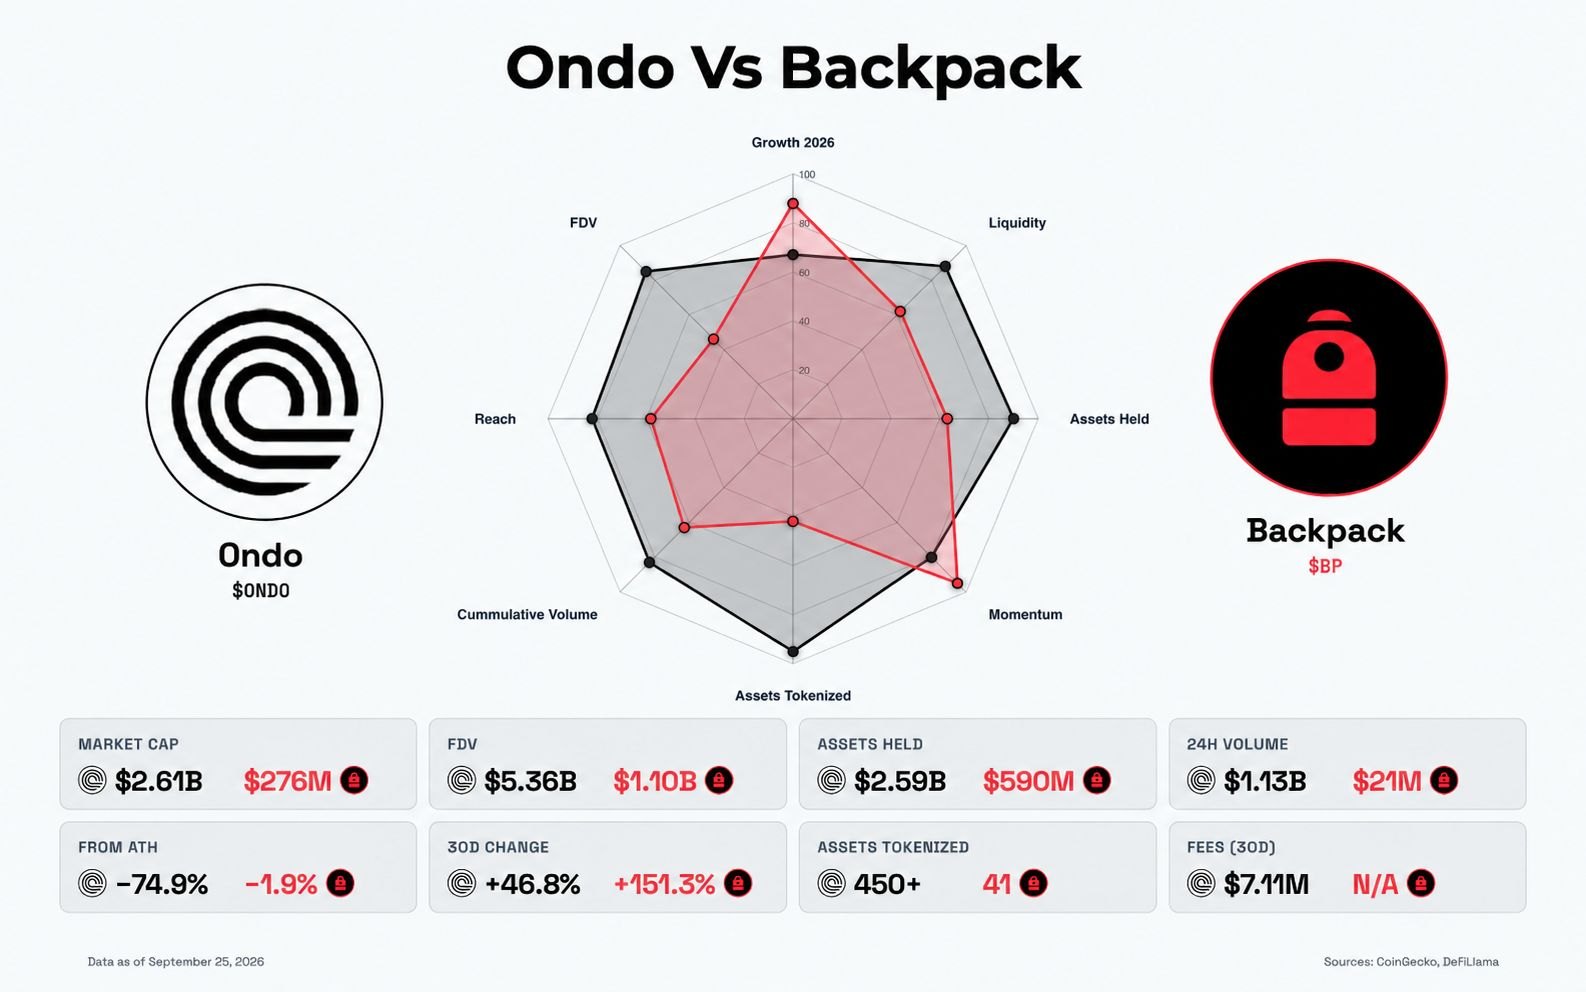
$ONDO | @Ondo Finance VS $BP | @Backpack

What a day to compare them.
BP printed a new all time high ✅
Ondo ripped 27% in a single day ✅
Both are chasing the same prize: putting Wall Street on-chain but from opposite ends.
Market cap:
$ONDO: ~$2.5B (FDV ~$5.2B)
$BP: ~$245M (FDV ~$980M)
A 10x gap. We ran the numbers to see if it's deserved 👇
1️⃣ What you're actually buying
Ondo is the issuer. It tokenizes US Treasuries (USDY, OUSG) and 450+ US stocks and ETFs (Ondo Stocks), then distributes them through Binance, Bitget, MetaMask and 30+ chains. Roughly $3.5B sits across its products.
=> You're buying governance over the biggest RWA shelf in crypto.
Backpack is the venue. A regulated exchange (Dubai VARA, EU MiFID II via the old FTX EU entity, Japan) that launched a US brokerage arm, Backpack Securities, in June and now issues its own tokenized stocks on Solana.
=> You're buying an exchange token with a path into the company's equity.
2️⃣ Revenue and Users
ONDO: ~$60M in annualized fees on DefiLlama, but most of it is yield passed through to USDY and OUSG holders. Retained protocol revenue runs ~$4M to $13M depending on the window. Broader estimates put company revenue around $48M.
BP: private company, no revenue disclosed. What's visible: $447B+ cumulative exchange volume, ~100K monthly active users, and reported funding talks at a $1B pre-money valuation in February.
3️⃣ The value-capture split
The real RWA question is not "how big is the platform," it's "does the token touch the cash flow?"
ONDO is governance only. Revenue from OUSG, USDY and Ondo Stocks flows to the company. Token holders get $0. A fee switch vote has been floated for H2 2026 but hasn't happened.
BP gives fee discounts, extra USD yield, and the unusual part: stake for 1 year+ and you can exchange BP for Backpack equity at IPO or acquisition, from a pool of up to 20% of the company.
ONDO's fix depends on a DAO vote that US securities law could complicate. BP's fix depends on Backpack actually going public or getting acquired.
4️⃣ Usage
This is the sharpest stat in the matchup.
Ondo owns the supply: 70%+ of tokenized equity issuance, $1.19B in Ondo Stocks TVL, ~225K unique holders, $26B+ cumulative trading volume.
Backpack owns the flow: $1.06B in tokenized stock DEX volume in July, 73% issuer-level share on Solana, while holding only ~5% of total tokenized stock supply. It also took 87% of tokenized SpaceX trading in Q2.
Ondo's volume includes CEX venues, Backpack's figure is Solana DEX only. But the direction is clear: its holding vs trading very clearly here.
5️⃣ Value accrual
ONDO: 10B hard cap, no inflation, no burn, no revenue share. Value today rests on governance optionality (fee switch, Ondo Network) and narrative.
BP: 1B hard cap, zero tokens to team or investors at TGE. ~66% of circulating supply was staked as of June, mostly chasing equity eligibility and fee tiers.
Same question for both: does platform growth reach the token?
For ONDO, only if governance flips the switch. For BP, only if the equity bridge actually gets used.
6️⃣ Supply and the overhang
ONDO: 4.87B of 10B circulating (~49%). Next cliff lands January 18, 2027: ~1.94B ONDO in one day, about 40% more than today's entire float (~$1B at current prices). The same-size unlock last January weighed hard on price.
BP: 250M of 1B circulating (25%). 375M unlocks on company milestones before IPO, and 375M stays in treasury until at least a year after IPO. No VC cliff, but the milestone tranche is 1.5x today's float and its timing sits with the company.
Both have this unlock issue, so burn your hand with either here tbh 🤷
✦ What to expect going ahead
ONDO is the category-leader bet.
> Biggest RWA issuer
> A seat in the DTCC tokenization group next to BlackRock and Goldman, FINRA clearance for US investors, Ondo Network live.
> The risk: a token that still captures $0, and a ~1.94B unlock less than four months away.
BP is the venue-and-equity bet.
>Volume leader in on-chain stock trading, licenses across multiple jurisdictions, a hard cap, and
> Real path to company equity.
> The risk: a small float, revenue you can't see, milestone unlocks the company controls, and a team with FTX/Alameda history plus a messy airdrop (sybil cuts and OTC-dump allegations the CEO denied).
One thing to note is that this is not a zero sum game for both these projects - both could succeed, or one could or umm.. both couldn't 💭