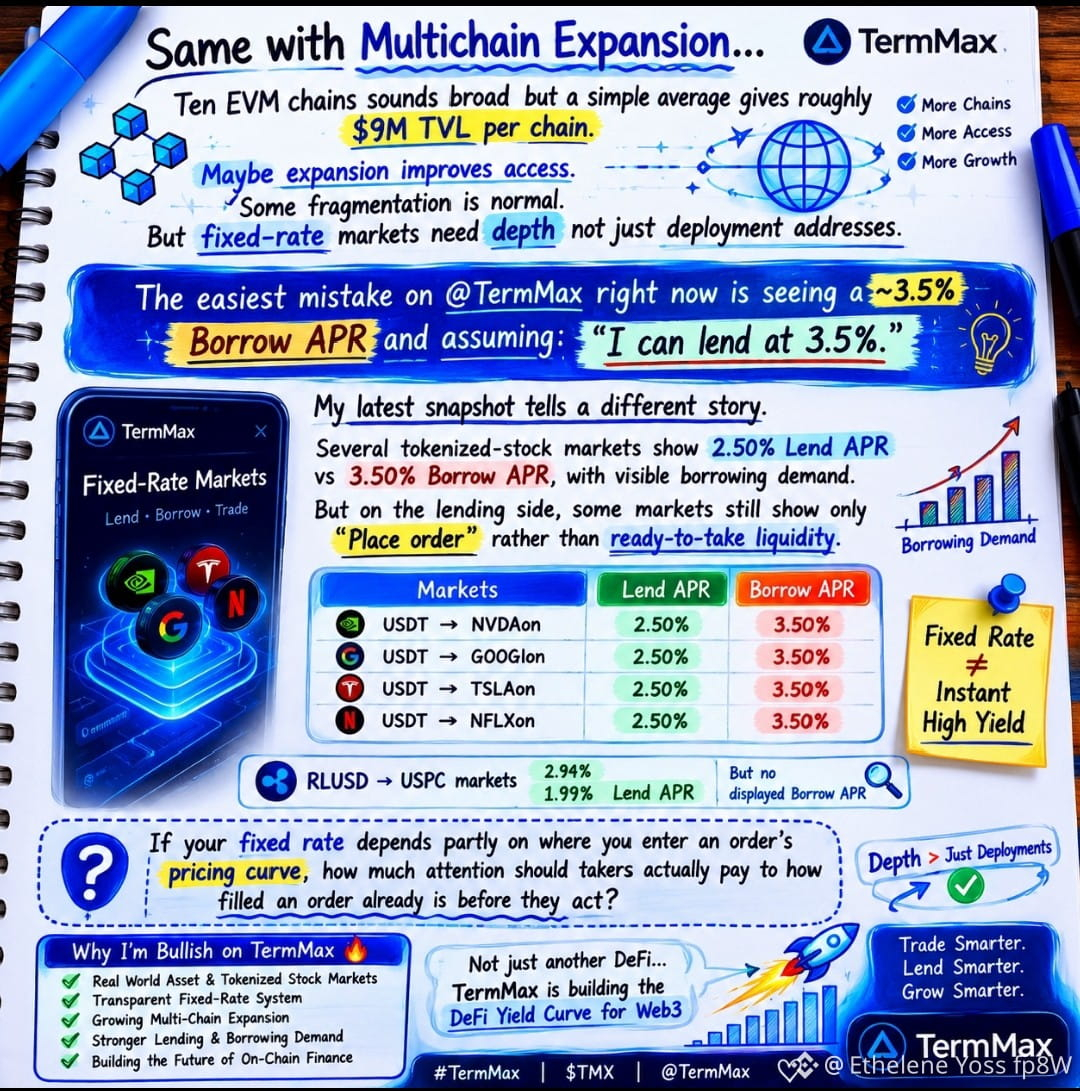
#termmax Same with multichain expansion. Ten EVM chains sounds broad but a simple average gives roughly $9M TVL per chain. Maybe expansion improves access. Some fragmentation is normal. But fixed-rate markets need depth not just deployment addresses.The easiest mistake on @TermMax right now is seeing a ~3.5% Borrow APR and assuming: “I can lend at 3.5%.”
My latest snapshot tells a different story.
Several tokenized-stock markets show 2.50% Lend APR vs 3.50% Borrow APR, with visible borrowing demand. But on the lending side, some markets still show only “Place order” rather than ready-to-take liquidity.
For example:
• USDT → NVDAon: 2.50% Lend / 3.50% Borrow
• USDT → GOOGlon: 2.50% / 3.50%
• USDT → TSLAon: 2.50% / 3.50%
• USDT → NFLXon: 2.50% / 3.50%
Meanwhile, the RLUSD → USPC markets show 2.94% and 1.99% Lend APR, but no displayed Borrow APR.If your fixed rate depends partly on where you enter an order's pricing curve, how much attention should takers actually pay to how filled an order already is before they act?
#termmax @TermMax