
#consumerstocks
consumerstocks
閲覧回数 5,058
8人が討論中
注目
最新

·
--
本人確認中
#earningsseason
🚨 プロクター・アンド・ギャンブル、売上高232億8000万ドルでウォール街の予想を上回る!
ジレット、パンパース、タイドなどのブランドを展開する消費財大手プロクター・アンド・ギャンブル($PG.US )は、予想を上回る四半期決算を発表しました。
同社の調整後1株当たり利益は2.00ドルとなり、アナリスト予想の1.89ドルを上回りました。
四半期売上高は232億8000万ドルに達し、前年同期比で約4%増加。ウォール街の予想である228億ドルも上回りました。
📈 決算発表後、株価は一時約5.6%急騰し、好決算に対する投資家の前向きな反応を示しました。
今回の報告は特に重要です。プロクター・アンド・ギャンブルの業績から、世界の消費支出、価格決定力、日用品への需要を読み取ることができるためです。
インフレ懸念や金利の先行き不透明感が市場に影響を与えるなか、投資家は大手消費財企業が収益性を維持できるかどうかを注視しています。
重要なポイントは、景気全体の先行きが不透明ななかでも、景気の影響を受けにくい消費財企業の好業績が、底堅さを示す可能性があることです。
#stockmarket #WallStreet #ConsumerStocks
#earningsseason
🚨 プロクター・アンド・ギャンブル、売上高232億8000万ドルでウォール街の予想を上回る!
ジレット、パンパース、タイドなどのブランドを展開する消費財大手プロクター・アンド・ギャンブル($PG.US )は、予想を上回る四半期決算を発表しました。
同社の調整後1株当たり利益は2.00ドルとなり、アナリスト予想の1.89ドルを上回りました。
四半期売上高は232億8000万ドルに達し、前年同期比で約4%増加。ウォール街の予想である228億ドルも上回りました。
📈 決算発表後、株価は一時約5.6%急騰し、好決算に対する投資家の前向きな反応を示しました。
今回の報告は特に重要です。プロクター・アンド・ギャンブルの業績から、世界の消費支出、価格決定力、日用品への需要を読み取ることができるためです。
インフレ懸念や金利の先行き不透明感が市場に影響を与えるなか、投資家は大手消費財企業が収益性を維持できるかどうかを注視しています。
重要なポイントは、景気全体の先行きが不透明ななかでも、景気の影響を受けにくい消費財企業の好業績が、底堅さを示す可能性があることです。
#stockmarket #WallStreet #ConsumerStocks
🚨 プロクター・アンド・ギャンブル、売上高232億8000万ドルでウォール街の予想を上回る!
ジレット、パンパース、タイドなどのブランドを展開する消費財大手プロクター・アンド・ギャンブル($PG.US )は、予想を上回る四半期決算を発表しました。
同社の調整後1株当たり利益は2.00ドルとなり、アナリスト予想の1.89ドルを上回りました。
四半期売上高は232億8000万ドルに達し、前年同期比で約4%増加。ウォール街の予想である228億ドルも上回りました。
📈 決算発表後、株価は一時約5.6%急騰し、好決算に対する投資家の前向きな反応を示しました。
今回の報告は特に重要です。プロクター・アンド・ギャンブルの業績から、世界の消費支出、価格決定力、日用品への需要を読み取ることができるためです。
インフレ懸念や金利の先行き不透明感が市場に影響を与えるなか、投資家は大手消費財企業が収益性を維持できるかどうかを注視しています。
重要なポイントは、景気全体の先行きが不透明ななかでも、景気の影響を受けにくい消費財企業の好業績が、底堅さを示す可能性があることです。
#stockmarket #WallStreet #ConsumerStocks
2.6k

·
--
記事
翻訳参照
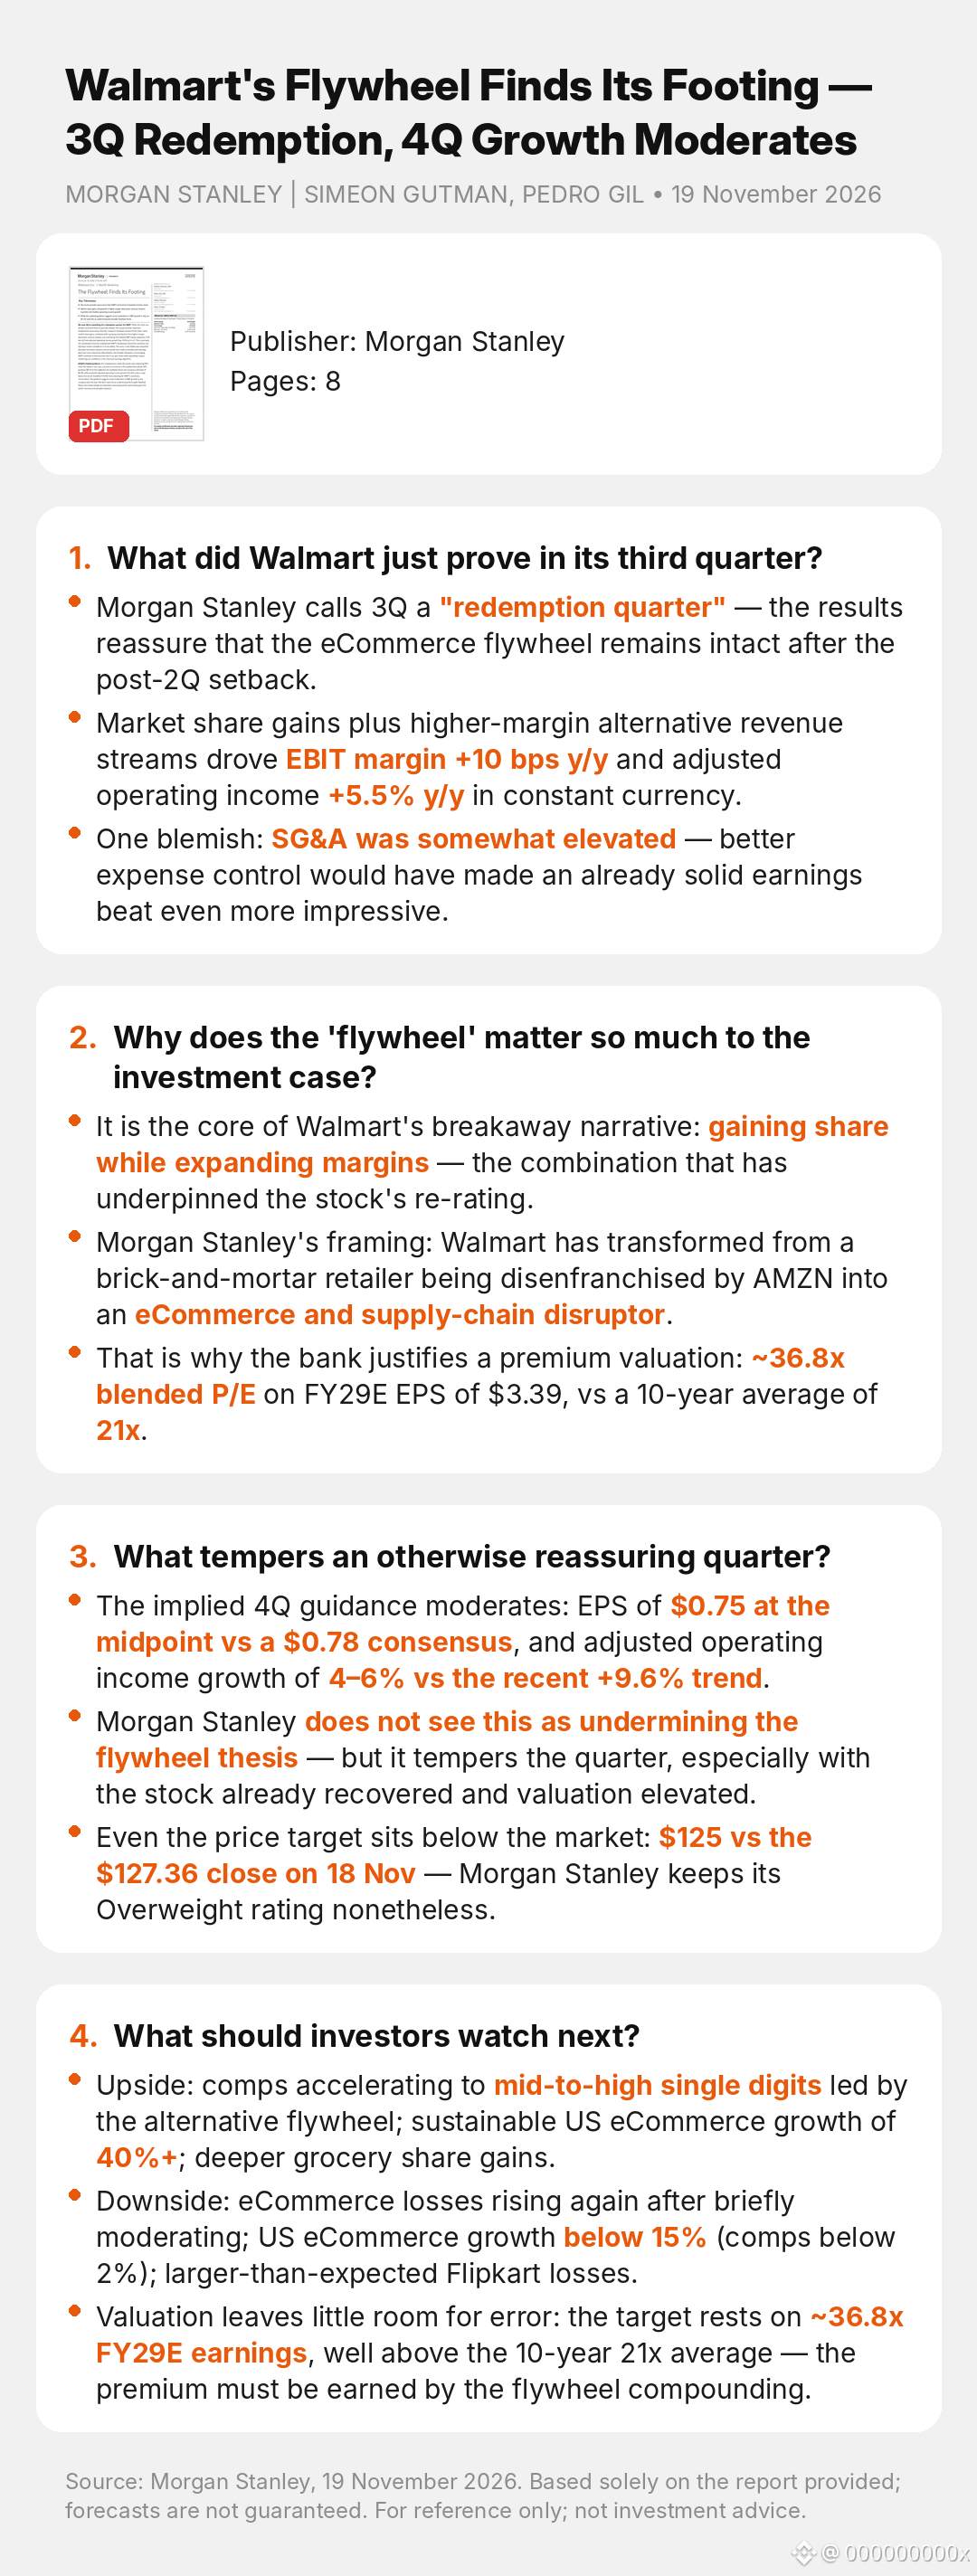
Walmart's Flywheel Finds Its Footing — 3Q Redemption, 4Q Growth ModeratesWalmart's Flywheel Finds Its Footing — 3Q Redemption, 4Q Growth Moderates
$WMT
MORGAN STANLEY | SIMEON GUTMAN, PEDRO GIL • 19 November 2026
1. What did Walmart just prove in its third quarter?
• Morgan Stanley calls 3Q a "redemption quarter" — the results reassure that the eCommerce flywheel remains intact after the post-2Q setback.
• Market share gains plus higher-margin alternative revenue streams drove EBIT margin +10 bps y/y and adjusted operating income +5.5% y/y in constant currency.
• One blemish: SG&A was somewhat elevated — better expense control would have made an already solid earnings beat even more impressive.
2. Why does the 'flywheel' matter so much to the investment case?
• It is the core of Walmart's breakaway narrative: gaining share while expanding margins — the combination that has underpinned the stock's re-rating.
• Morgan Stanley's framing: Walmart has transformed from a brick-and-mortar retailer being disenfranchised by AMZN into an eCommerce and supply-chain disruptor.
• That is why the bank justifies a premium valuation: ~36.8x blended P/E on FY29E EPS of $3.39, vs a 10-year average of 21x.
3. What tempers an otherwise reassuring quarter?
• The implied 4Q guidance moderates: EPS of $0.75 at the midpoint vs a $0.78 consensus, and adjusted operating income growth of 4–6% vs the recent +9.6% trend.
• Morgan Stanley does not see this as undermining the flywheel thesis — but it tempers the quarter, especially with the stock already recovered and valuation elevated.
• Even the price target sits below the market: $125 vs the $127.36 close on 18 Nov — Morgan Stanley keeps its Overweight rating nonetheless.
4. What should investors watch next?
• Upside: comps accelerating to mid-to-high single digits led by the alternative flywheel; sustainable US eCommerce growth of 40%+; deeper grocery share gains.
• Downside: eCommerce losses rising again after briefly moderating; US eCommerce growth below 15% (comps below 2%); larger-than-expected Flipkart losses.
• Valuation leaves little room for error: the target rests on ~36.8x FY29E earnings, well above the 10-year 21x average — the premium must be earned by the flywheel compounding.
Update after this report (not in the Morgan Stanley note): Walmart reported 3Q adjusted EPS of $0.65 vs $0.64 expected and revenue of $188.8bn (+5.2%) vs ~$187.3bn expected. Shares fell 1.0% to $126.04 on 19 Nov, then rose ~1.5% to $127.95 on 20 Nov as money rotated out of AI names. Morgan Stanley has since raised its price target to $135 from $125 (Benzinga, 20 Nov).
Source: Morgan Stanley, "The Flywheel Finds Its Footing", 19 November 2026. Based solely on the report provided; forecasts are not guaranteed. For reference only; not investment advice.
#Retail #Earnings #ConsumerStocks #USStocks #Walmart
Walmart's Flywheel Finds Its Footing — 3Q Redemption, 4Q Growth Moderates
Walmart's Flywheel Finds Its Footing — 3Q Redemption, 4Q Growth Moderates
$WMT
MORGAN STANLEY | SIMEON GUTMAN, PEDRO GIL • 19 November 2026
1. What did Walmart just prove in its third quarter?
• Morgan Stanley calls 3Q a "redemption quarter" — the results reassure that the eCommerce flywheel remains intact after the post-2Q setback.
• Market share gains plus higher-margin alternative revenue streams drove EBIT margin +10 bps y/y and adjusted operating income +5.5% y/y in constant currency.
• One blemish: SG&A was somewhat elevated — better expense control would have made an already solid earnings beat even more impressive.
2. Why does the 'flywheel' matter so much to the investment case?
• It is the core of Walmart's breakaway narrative: gaining share while expanding margins — the combination that has underpinned the stock's re-rating.
• Morgan Stanley's framing: Walmart has transformed from a brick-and-mortar retailer being disenfranchised by AMZN into an eCommerce and supply-chain disruptor.
• That is why the bank justifies a premium valuation: ~36.8x blended P/E on FY29E EPS of $3.39, vs a 10-year average of 21x.
3. What tempers an otherwise reassuring quarter?
• The implied 4Q guidance moderates: EPS of $0.75 at the midpoint vs a $0.78 consensus, and adjusted operating income growth of 4–6% vs the recent +9.6% trend.
• Morgan Stanley does not see this as undermining the flywheel thesis — but it tempers the quarter, especially with the stock already recovered and valuation elevated.
• Even the price target sits below the market: $125 vs the $127.36 close on 18 Nov — Morgan Stanley keeps its Overweight rating nonetheless.
4. What should investors watch next?
• Upside: comps accelerating to mid-to-high single digits led by the alternative flywheel; sustainable US eCommerce growth of 40%+; deeper grocery share gains.
• Downside: eCommerce losses rising again after briefly moderating; US eCommerce growth below 15% (comps below 2%); larger-than-expected Flipkart losses.
• Valuation leaves little room for error: the target rests on ~36.8x FY29E earnings, well above the 10-year 21x average — the premium must be earned by the flywheel compounding.
Update after this report (not in the Morgan Stanley note): Walmart reported 3Q adjusted EPS of $0.65 vs $0.64 expected and revenue of $188.8bn (+5.2%) vs ~$187.3bn expected. Shares fell 1.0% to $126.04 on 19 Nov, then rose ~1.5% to $127.95 on 20 Nov as money rotated out of AI names. Morgan Stanley has since raised its price target to $135 from $125 (Benzinga, 20 Nov).
Source: Morgan Stanley, "The Flywheel Finds Its Footing", 19 November 2026. Based solely on the report provided; forecasts are not guaranteed. For reference only; not investment advice.
#Retail #Earnings #ConsumerStocks #USStocks #Walmart
$WMT
MORGAN STANLEY | SIMEON GUTMAN, PEDRO GIL • 19 November 2026
1. What did Walmart just prove in its third quarter?
• Morgan Stanley calls 3Q a "redemption quarter" — the results reassure that the eCommerce flywheel remains intact after the post-2Q setback.
• Market share gains plus higher-margin alternative revenue streams drove EBIT margin +10 bps y/y and adjusted operating income +5.5% y/y in constant currency.
• One blemish: SG&A was somewhat elevated — better expense control would have made an already solid earnings beat even more impressive.
2. Why does the 'flywheel' matter so much to the investment case?
• It is the core of Walmart's breakaway narrative: gaining share while expanding margins — the combination that has underpinned the stock's re-rating.
• Morgan Stanley's framing: Walmart has transformed from a brick-and-mortar retailer being disenfranchised by AMZN into an eCommerce and supply-chain disruptor.
• That is why the bank justifies a premium valuation: ~36.8x blended P/E on FY29E EPS of $3.39, vs a 10-year average of 21x.
3. What tempers an otherwise reassuring quarter?
• The implied 4Q guidance moderates: EPS of $0.75 at the midpoint vs a $0.78 consensus, and adjusted operating income growth of 4–6% vs the recent +9.6% trend.
• Morgan Stanley does not see this as undermining the flywheel thesis — but it tempers the quarter, especially with the stock already recovered and valuation elevated.
• Even the price target sits below the market: $125 vs the $127.36 close on 18 Nov — Morgan Stanley keeps its Overweight rating nonetheless.
4. What should investors watch next?
• Upside: comps accelerating to mid-to-high single digits led by the alternative flywheel; sustainable US eCommerce growth of 40%+; deeper grocery share gains.
• Downside: eCommerce losses rising again after briefly moderating; US eCommerce growth below 15% (comps below 2%); larger-than-expected Flipkart losses.
• Valuation leaves little room for error: the target rests on ~36.8x FY29E earnings, well above the 10-year 21x average — the premium must be earned by the flywheel compounding.
Update after this report (not in the Morgan Stanley note): Walmart reported 3Q adjusted EPS of $0.65 vs $0.64 expected and revenue of $188.8bn (+5.2%) vs ~$187.3bn expected. Shares fell 1.0% to $126.04 on 19 Nov, then rose ~1.5% to $127.95 on 20 Nov as money rotated out of AI names. Morgan Stanley has since raised its price target to $135 from $125 (Benzinga, 20 Nov).
Source: Morgan Stanley, "The Flywheel Finds Its Footing", 19 November 2026. Based solely on the report provided; forecasts are not guaranteed. For reference only; not investment advice.
#Retail #Earnings #ConsumerStocks #USStocks #Walmart
61

Lululemonの新CEOの動きは、市場が待ち望んでいたリセットになるかもしれない🌿
ハイジ・オニールは、26年にわたるナイキでの経験を、米国での成長鈍化や、より厳しいアクティブウェア競争によってセンチメントが圧迫されている局面で<LULU>にもたらします。この人事は、立て直し(ターンアラウンド)の物語により信ぴょう性を与えますが、時間外での下落は、プロダクト、ブランド、そして需要が再び加速できるのかという「実証」をトレーダーがまだ求めていることを示しています。
<LULU>は、ただ見出しを信じているだけではなく、市場が実行を求めているかのような値動きをしています。新しいリーダーシップはより長期の資本を惹きつける可能性がありますが、短期ではテープ(板)の様子が慎重で、いわゆる“クジラ”たちは、実際の勢いが出るのを見てから改めて同銘柄を再評価するのを待っているようです。
投資助言ではありません。リスクを管理し、資本を守ってください。
#RetailStocks #StockMarket #Investing #WallStreet #ConsumerStocks
✦
Lululemonの新CEOの動きは、市場が待ち望んでいたリセットになるかもしれない🌿
ハイジ・オニールは、26年にわたるナイキでの経験を、米国での成長鈍化や、より厳しいアクティブウェア競争によってセンチメントが圧迫されている局面で<LULU>にもたらします。この人事は、立て直し(ターンアラウンド)の物語により信ぴょう性を与えますが、時間外での下落は、プロダクト、ブランド、そして需要が再び加速できるのかという「実証」をトレーダーがまだ求めていることを示しています。
<LULU>は、ただ見出しを信じているだけではなく、市場が実行を求めているかのような値動きをしています。新しいリーダーシップはより長期の資本を惹きつける可能性がありますが、短期ではテープ(板)の様子が慎重で、いわゆる“クジラ”たちは、実際の勢いが出るのを見てから改めて同銘柄を再評価するのを待っているようです。
投資助言ではありません。リスクを管理し、資本を守ってください。
#RetailStocks #StockMarket #Investing #WallStreet #ConsumerStocks
✦
ハイジ・オニールは、26年にわたるナイキでの経験を、米国での成長鈍化や、より厳しいアクティブウェア競争によってセンチメントが圧迫されている局面で<LULU>にもたらします。この人事は、立て直し(ターンアラウンド)の物語により信ぴょう性を与えますが、時間外での下落は、プロダクト、ブランド、そして需要が再び加速できるのかという「実証」をトレーダーがまだ求めていることを示しています。
<LULU>は、ただ見出しを信じているだけではなく、市場が実行を求めているかのような値動きをしています。新しいリーダーシップはより長期の資本を惹きつける可能性がありますが、短期ではテープ(板)の様子が慎重で、いわゆる“クジラ”たちは、実際の勢いが出るのを見てから改めて同銘柄を再評価するのを待っているようです。
投資助言ではありません。リスクを管理し、資本を守ってください。
#RetailStocks #StockMarket #Investing #WallStreet #ConsumerStocks
✦
18

📊 $MCD BEAT THE STREET — その理由は?ゴールデン・アーチがマクロ全体を動かすからだ!🟢
ゴールデン・アーチはウォール街に、謙虚な一皿を提供した。調整後EPSは市場予想の$3.32に対して$3.38を計上——一方でヘッドライン利益は前年の$3.14から$3.32へと上昇した。📊
これは単なる誤差じゃない。防御力の強い巨人が減速局面の物語へと加速しており、平均的な財布にはまだ燃料が残っていることを示している。クォーターパウンダーが動き続けるなら、消費者の底堅さがじわじわとより広いリスク選好へとにじみ出てくる。💡
暗号資産トレーダーにとって、これは尊重すべきマクロのサインだ。底堅い支出は緊急の政策対応に対する圧力を弱める。そして安定した流動性の背景は、リスク資産がゲームに残り続ける環境を支える。🔍
伝統的な決算の数字は、あなたの暗号資産のポジション調整に影響しますか?それとも2つのテープ(市場データ)を切り離して取引していますか?💬👇
⚠️ 金融助言ではありません。常にリスク管理を行ってください。🛡️
🏷️ #MCD #EarningsBeat #MacroSignal #ConsumerStocks #Crypto
📊 💡
📊 $MCD BEAT THE STREET — その理由は?ゴールデン・アーチがマクロ全体を動かすからだ!🟢
ゴールデン・アーチはウォール街に、謙虚な一皿を提供した。調整後EPSは市場予想の$3.32に対して$3.38を計上——一方でヘッドライン利益は前年の$3.14から$3.32へと上昇した。📊
これは単なる誤差じゃない。防御力の強い巨人が減速局面の物語へと加速しており、平均的な財布にはまだ燃料が残っていることを示している。クォーターパウンダーが動き続けるなら、消費者の底堅さがじわじわとより広いリスク選好へとにじみ出てくる。💡
暗号資産トレーダーにとって、これは尊重すべきマクロのサインだ。底堅い支出は緊急の政策対応に対する圧力を弱める。そして安定した流動性の背景は、リスク資産がゲームに残り続ける環境を支える。🔍
伝統的な決算の数字は、あなたの暗号資産のポジション調整に影響しますか?それとも2つのテープ(市場データ)を切り離して取引していますか?💬👇
⚠️ 金融助言ではありません。常にリスク管理を行ってください。🛡️
🏷️ #MCD #EarningsBeat #MacroSignal #ConsumerStocks #Crypto
📊 💡
ゴールデン・アーチはウォール街に、謙虚な一皿を提供した。調整後EPSは市場予想の$3.32に対して$3.38を計上——一方でヘッドライン利益は前年の$3.14から$3.32へと上昇した。📊
これは単なる誤差じゃない。防御力の強い巨人が減速局面の物語へと加速しており、平均的な財布にはまだ燃料が残っていることを示している。クォーターパウンダーが動き続けるなら、消費者の底堅さがじわじわとより広いリスク選好へとにじみ出てくる。💡
暗号資産トレーダーにとって、これは尊重すべきマクロのサインだ。底堅い支出は緊急の政策対応に対する圧力を弱める。そして安定した流動性の背景は、リスク資産がゲームに残り続ける環境を支える。🔍
伝統的な決算の数字は、あなたの暗号資産のポジション調整に影響しますか?それとも2つのテープ(市場データ)を切り離して取引していますか?💬👇
⚠️ 金融助言ではありません。常にリスク管理を行ってください。🛡️
🏷️ #MCD #EarningsBeat #MacroSignal #ConsumerStocks #Crypto
📊 💡
28
ログインして、さらにコンテンツを読む
厳選トピックで世界の暗号資産トレーダーの仲間入り
⚡️ 暗号資産に関する最新かつ有益な情報が見つかります。
💬 世界最大の暗号資産取引所から信頼されています。
👍 認証を受けたクリエイターから、有益なインサイトを得られます。
メール / 電話番号
トレンドトピック
1
#CanBTCReboundAfterFallingBelow60K?
閲覧回数 388,957
1,699人が討論中
2
#GlobalStocksFaceLongestLosingStreakSince2023
閲覧回数 129,378
1,190人が討論中
3
#BlackRockIBITPostsRecord$541MSingleDayOutflow
閲覧回数 1,028
32人が討論中
4
#AnthropicPlungesTowardIPOPriceonDay2
閲覧回数 61,498
656人が討論中
5
#TwentyOneCapitalAdds172.25BTC
閲覧回数 14,326
215人が討論中
6
#HKBillWouldExcludeTokenizedDepositsFromVirtualAssets
閲覧回数 1,432
19人が討論中
7
#BNBDropsBelow540USDTWith8.46%DailyDecline
閲覧回数 34,954
317人が討論中
8
#HKBillProposesHK$100KFineForUnauthorizedCryptoTitles
閲覧回数 1,141
17人が討論中
9
#BitMineFaces$10.1BUnrealizedETHLoss
閲覧回数 2,166
20人が討論中
10
#StrategyReports$35BNetReserves
閲覧回数 2,128
18人が討論中