
Bitcoin’s Sell-Off: A Multi-Factor Event, Not a Single Culprit
There has been a lot of discussion and speculation surrounding Bitcoin’s recent decline, with some narratives attempting to connect the sell-off directly to Binance and its recent security incident.
But when we step back and examine the broader market data, the picture looks quite different.
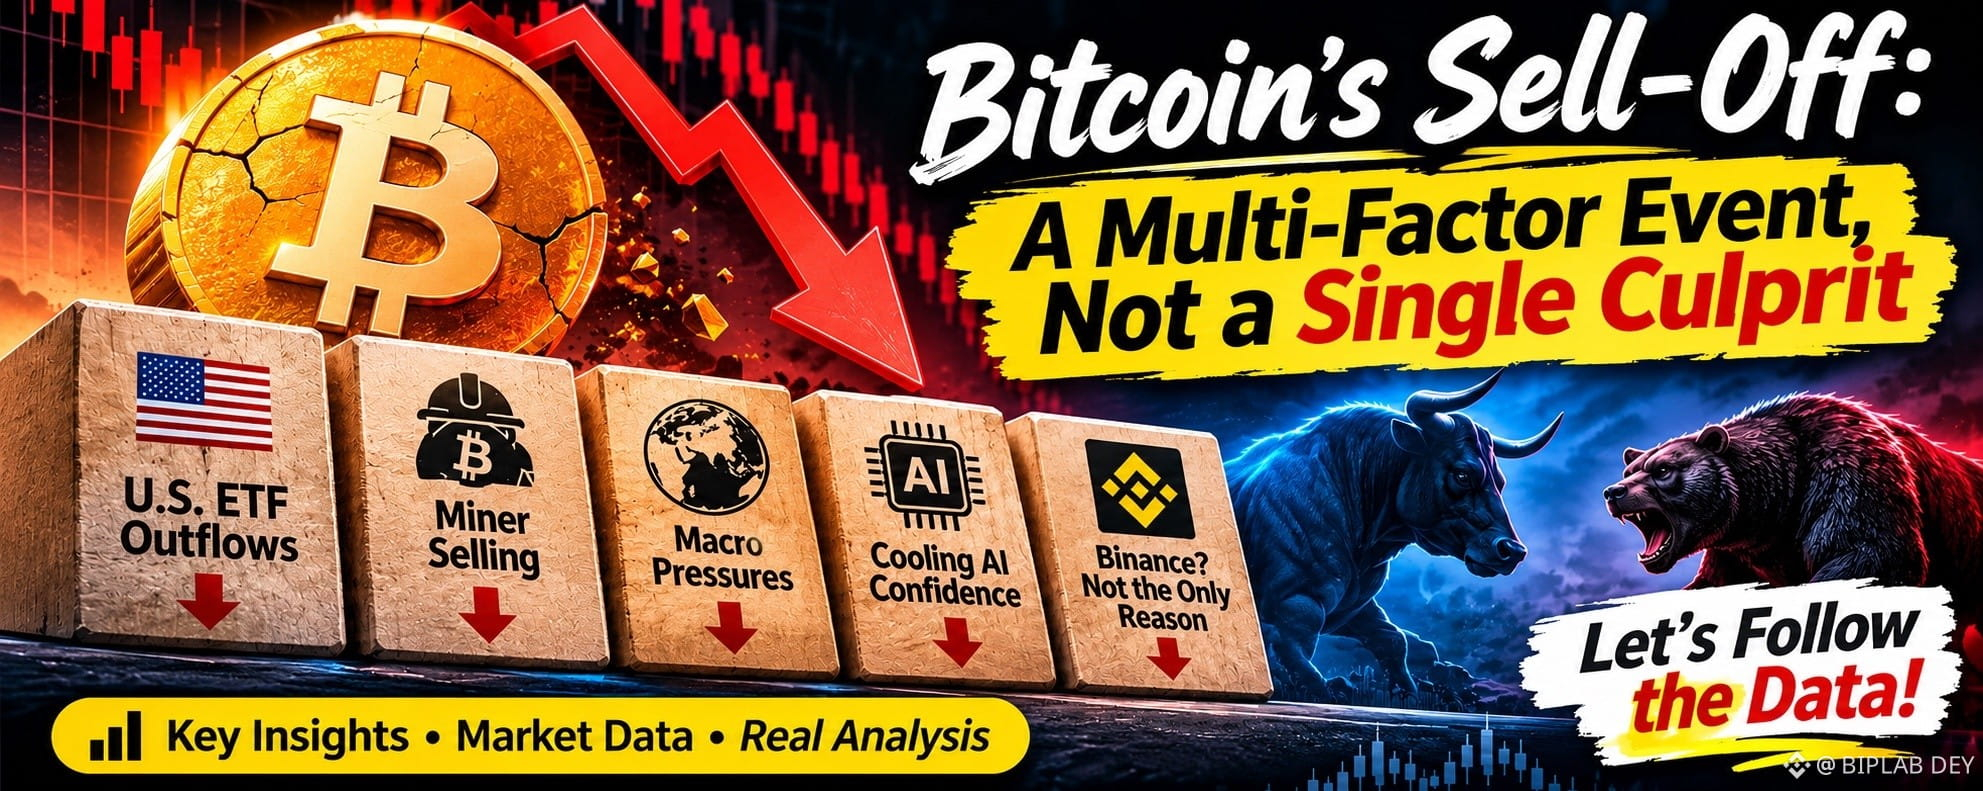
Bitcoin has declined 15.6% over an 11-day period, marking its sharpest comparable sell-off since June. While market participants are looking for one explanation, several indicators suggest that this correction is the result of multiple forces coming together: institutional outflows, aggressive spot selling, miner treasury adjustments, tightening macroeconomic conditions and weakening confidence in the AI investment cycle.
Blaming one exchange without examining the wider market structure would be an incomplete analysis.
Here are five important factors worth looking at.
1. U.S. Spot Market Selling and Institutional Outflows
One of the clearest signs of selling pressure is coming from the U.S. market.
U.S. spot Bitcoin ETFs recorded approximately $1.91 billion in net outflows over seven consecutive trading sessions. This represents one of the most significant outflow periods since these products were launched.
When institutional capital starts moving out of Bitcoin ETFs, it can create meaningful selling pressure and weaken overall market sentiment.
Another interesting data point comes from Anchorage Digital’s David Lawant, who shared Bitcoin Cumulative Volume Delta (CVD) data between November 9 and 14 (UTC).
The reported figures were:
Coinbase: approximately -8,900 BTC
Binance: approximately -3,100 BTC
Bybit: approximately -700 BTC
These figures indicate that aggressive selling was particularly pronounced on Coinbase during the observed period, although selling pressure was present across multiple exchanges.
This is an important distinction. Market-wide selling activity should not automatically be attributed to one particular exchange.
Another interesting comparison is NBIS perpetuals, which declined approximately 27.5% over the same 11-day period, compared with Bitcoin’s 15.6% decline.
This suggests that weakness was not limited to crypto. Assets sensitive to AI financing and technology-sector sentiment were also experiencing significant pressure.
What I am watching: Whether U.S. spot selling slows down and ETF outflows begin to stabilize. A meaningful improvement in institutional flows could be an important signal for market recovery.
2. Bitcoin Miners Are Also Adding to Market Supply
Another important factor that deserves attention is selling from Bitcoin miners.
According to MARA’s reported figures, the company sold 13,597 BTC for approximately $1.1 billion, at an average price of around $81,039, over roughly six weeks.
There is another important detail.
MARA had already sold approximately 26,984 BTC during the first nine months of 2026.
Meanwhile, its Q3 Bitcoin production was approximately 2,247 BTC.
In other words, its subsequent six-week sale was roughly six times its entire third-quarter mining production.
Why did this happen?
The sales were connected to MARA’s broader treasury and financing strategy.
Approximately $750 million from the proceeds was used to repay Bitcoin-backed loans.
The repayment resulted in the release of 17,477 BTC previously pledged as collateral.
The company is also pursuing opportunities in AI infrastructure, data centres and energy-related businesses.
This illustrates an important market dynamic: Bitcoin miners are not necessarily holding all the BTC they produce. They may sell existing treasury holdings to manage debt, improve liquidity or finance new business opportunities.
Miner selling and institutional portfolio adjustments are additional sources of supply that should be considered when analysing Bitcoin’s price movements.
3. Macroeconomic and Geopolitical Pressure
We cannot analyse Bitcoin independently of the global financial environment.
Higher-than-expected inflation and stronger employment data have increased expectations of further Federal Reserve tightening.
This matters because:
Higher Treasury yields make traditional fixed-income investments more attractive relative to non-yielding assets such as Bitcoin.
A stronger U.S. dollar can create additional pressure on risk-sensitive assets.
Tighter financial conditions reduce the availability of liquidity.
Geopolitical uncertainty encourages investors to become more defensive and reduce exposure to volatile investments.
Bitcoin is increasingly connected to global liquidity and institutional risk appetite.
When investors become cautious across financial markets, crypto is often among the assets facing reduced exposure.
This is why macroeconomic developments cannot be ignored when discussing the current correction.
4. Cooling AI Investment Confidence and Competing Capital Demands
Another development I find particularly interesting is the changing sentiment around AI-related investments.
The AI industry has attracted enormous capital over the past few years. However, investors are increasingly evaluating the financing requirements, infrastructure costs, valuations and long-term returns associated with this investment cycle.
The decline in AI financing-sensitive assets, including the 27.5% fall in NBIS perpetuals during the same observed period, highlights the broader weakness in technology-sector risk appetite.
There are also major developments on the horizon.
Anthropic’s anticipated IPO and Nvidia’s upcoming earnings commentary could influence how institutional investors allocate capital across technology, AI and other risk assets.
This does not mean that capital is necessarily moving directly from Bitcoin into AI investments.
Rather, institutional investors are constantly making allocation decisions. When confidence in one investment category weakens, or another opportunity demands substantial capital, overall liquidity and risk appetite can change.
The AI financing cycle is therefore another factor worth monitoring.
5. Why Blaming Binance Alone Does Not Explain the Sell-Off
Now let’s address the speculation surrounding Binance.
Some recent narratives have suggested that Binance was selling tokens to cover losses related to its security incident and that this activity triggered the wider market decline.
However, the available market data presented above does not establish that connection.
There are several reasons why a single-exchange explanation is insufficient.
First, U.S. spot Bitcoin ETFs experienced approximately $1.91 billion in outflows over seven consecutive trading sessions.
Second, Coinbase recorded significantly more negative BTC CVD than Binance during the November 9–14 observation window.
Third, MARA disclosed substantial Bitcoin sales as part of its treasury and debt-management strategy.
Fourth, AI-related assets and broader risk markets were also experiencing considerable weakness amid changing macroeconomic expectations.
These are independently observable market developments. They deserve consideration before drawing conclusions about the cause of Bitcoin’s decline.
From a business perspective, Binance’s long-term success depends on liquidity, trading activity, user confidence and the overall health of the cryptocurrency ecosystem.
A deliberate attempt to trigger a market-wide sell-off would carry enormous commercial and reputational consequences. There is no apparent commercial rationale for such an action.
Furthermore, Binance has stated that it replenished the vast majority of assets affected by the security incident, including BTC and other major assets, with remaining smaller assets addressed subsequently.
It is important to distinguish between speculation, allegations and verifiable evidence.
An allegation should not be treated as an established fact without supporting data.
My Take: Look at the Entire Market, Not Just One Headline
In my view, Bitcoin’s recent correction is better understood as the convergence of several market pressures rather than the result of one event or one market participant.
Consider the bigger picture:
Institutional selling: $1.91 billion in U.S. spot Bitcoin ETF outflows.
Exchange-level activity: Significant aggressive selling across major trading venues, with Coinbase showing particularly negative CVD.
Miner supply: MARA sold 13,597 BTC over approximately six weeks.
Macroeconomic pressure: Inflation, Treasury yields, dollar strength and expectations of tighter monetary policy.
Technology-sector weakness: Cooling confidence around AI financing and capital-intensive investments.
All these factors matter.
The next important question is not simply who to blame for the decline. It is whether these sources of selling pressure are beginning to ease.
I will be closely watching:
Whether U.S. spot Bitcoin ETF outflows start slowing.
Whether Coinbase and other major spot markets show improving buying pressure.
Whether miner selling activity begins to normalize.
Whether the Federal Reserve outlook and global liquidity conditions improve.
Whether confidence in the broader technology and AI investment cycle stabilizes.
Markets rarely move because of one headline. They move because of liquidity, positioning, sentiment, capital allocation and changing expectations.
As traders and investors, we should follow the data, question narratives and avoid jumping to conclusions.
Don’t confuse a complicated market correction with a simple blame story.
Do your own research. Manage risk. Stay objective.
Sources and References
1. U.S. Market Activity, ETF Outflows and CVD Data
Binance Research:
Anchorage Digital – David Lawant:
CoinGlass:
2. Bitcoin Miner Selling
CoinDesk – MARA sold 13,597 BTC for $1.1 billion in six weeks:
3. Additional Market Context
U.S. spot Bitcoin ETF flows, institutional positioning, macroeconomic developments and technology-sector sentiment discussed above.
Note: Figures refer to the specific observation periods mentioned. Market data and company disclosures are presented as reported, while interpretations of their impact are analytical rather than proof of direct causation.