($SNDK ) SanDisk has a business that looks pretty good right now. AI data centers need more storage, memory demand is rising, and companies are willing to spend serious money to secure supply. But here's the problem. A great business doesn't automatically make its stock a great buy at every price.
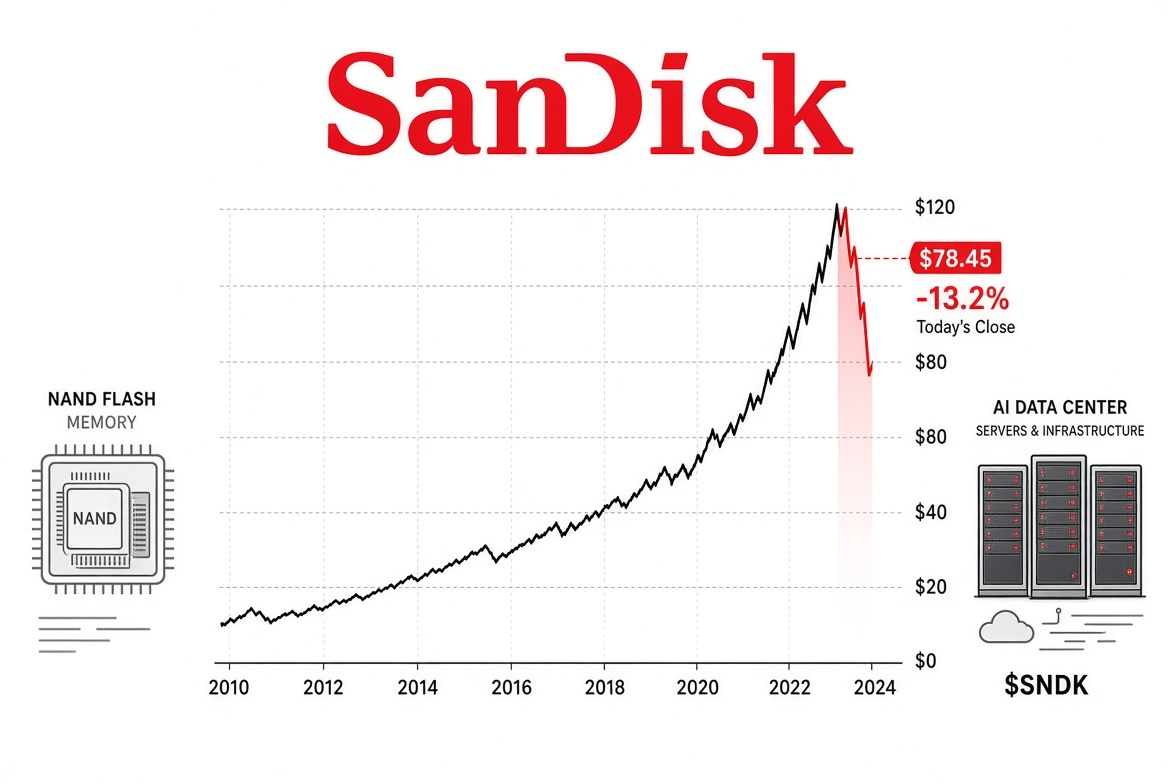
SNDK is trading around $1,150.89 based on the latest reported regular-session close, down approximately 13.47%. That is a painful move, especially after such a massive rally over the past year. The stock has already shown how quickly market sentiment can change when expectations get too high.
What's interesting is that SanDisk just reported some very strong numbers. Fiscal Q1 2027 revenue reached $11.03 billion, beating analyst expectations of $10.71 billion. Adjusted earnings came in at $49.51 per share, also above forecasts. Data-center revenue reached $4.08 billion, showing just how important AI infrastructure has become for the company.
So why is the stock under pressure?
I think investors are starting to ask a harder question. How long can this growth continue, and how much of it is already reflected in the share price?
SanDisk also gave strong guidance for the next quarter, expecting revenue around $12.4 billion at the midpoint. That's impressive. The company even announced an eight-for-one stock split scheduled for November 19. But a stock split doesn't create new business value. It only changes the number of shares and their individual price.
There is another risk that deserves attention. Memory is a cyclical business. When demand is strong and supply is tight, manufacturers can make huge profits. But the situation can change if competitors increase production or AI spending slows down. Even a company with strong customer contracts isn't completely protected from that cycle.
The latest weakness in other memory stocks is also worth watching. Kioxia shares dropped sharply after its latest outlook disappointed investors, despite continued demand for AI storage. That tells me the market is becoming more selective. Good demand is no longer enough. Investors want clear evidence that companies can turn that demand into lasting profits.
For the next 24 hours, my signal is bearish with a chance of a technical rebound. The sharp decline shows that sellers currently have the advantage. If SNDK stabilizes and buyers return, a recovery attempt could develop. But I would want to see stronger buying volume before calling it a real reversal. Another weak session could bring more pressure.
I still like the long-term storage demand story. AI models need data, data centers need storage, and SanDisk is in a position to benefit from that demand. But I don't think investors should ignore valuation, competition or the risk of a memory market slowdown just because the latest earnings were strong.
Sometimes the most important thing in the market isn't how good a company's results look. It's whether those results are good enough to meet expectations.
That's the real test for SanDisk now.