The Fed meets next week: should growth stocks wait for the answer, or watch expectations first?
The Fed meeting next week does not mean the market already knows the interest rate outcome. For growth stocks, what really needs to be separated are the two lines of discount rate changes and corporate earnings expectations; directly translating “rate cuts” into “stock prices must rise” skips a key condition.
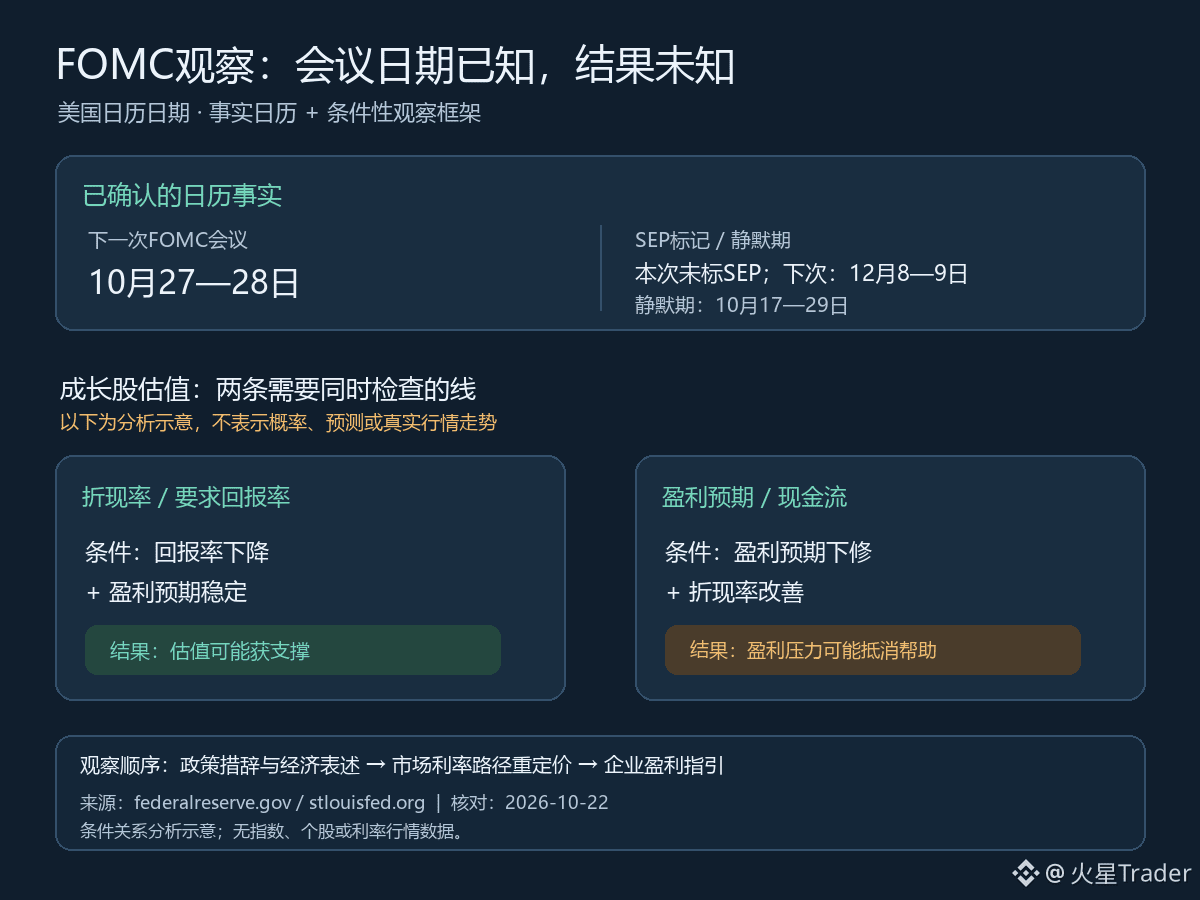
What can be confirmed on the calendar is this: the Federal Reserve’s next Federal Open Market Committee (FOMC) meeting is scheduled for October 27–28 on the U.S. calendar. The Fed’s published schedule does not mark a Summary of Economic Projections (SEP) alongside this meeting; the next date marked SEP on the schedule is December 8–9. Another verifiable time boundary is that the blackout period for Fed officials’ communications runs from October 17 to October 29. The above is only the meeting and communication calendar, and does not include an interest rate decision or market pricing conclusion.
Growth stocks are valued more sensitively to future cash flows. If the return required by the market falls while expectations for future corporate earnings remain stable, valuations may be supported; but if a change in rates comes with downward revisions to earnings expectations, pressure on cash flows may offset the help from the discount rate. Conversely, even if rates do not move in the direction investors expect, individual stocks may still perform differently as long as earnings expectations are stronger. This is a conditional analysis, not a prediction of the meeting result or stock price direction.
It is also important to note that the policy rate and the discount rate used in stock valuation are not the same thing. Long-term Treasury yields, risk premia, and investors’ judgment about the durability of growth can all change the market’s required return. Even if policy action matches expectations, if stock prices had already priced in more easing, the actual reaction may be the opposite of what the headline suggests. What is being discussed here is the mechanism of expectation differences, without using unverified current odds of a rate cut.
Therefore, on the day of the meeting, I would observe the policy language, the statements on the economy and inflation, and the market’s post-meeting repricing of the rate path separately, then compare them with earnings guidance from large growth companies. A single intraday move in an index cannot prove that discount-rate logic has already dominated the market; and the two words “rate cut” alone cannot replace earnings verification.
Next, first watch the October 27–28 meeting communication, then see whether company earnings reports and guidance can sustain earnings expectations. Only when the direction of both the rate path and cash flow expectations becomes clearer will the valuation reaction in growth stocks be easier to explain. The two paths shown in the illustration are an observation framework, not a probability or market forecast.
Data: Federal Reserve FOMC meeting calendar, St. Louis Fed officials’ communication blackout period calendar; both rechecked on 2026-10-23. Meeting dates are listed according to the U.S. calendar to avoid ambiguity from time zone conversion. The valuation and market reaction section is a conditional analysis and does not include rate forecasts, current market conditions, or probability judgments.
Source:
https://www.federalreserve.gov/monetarypolicy/fomccalendars.htm
https://www.stlouisfed.org/about-us/resources/blackout-periods