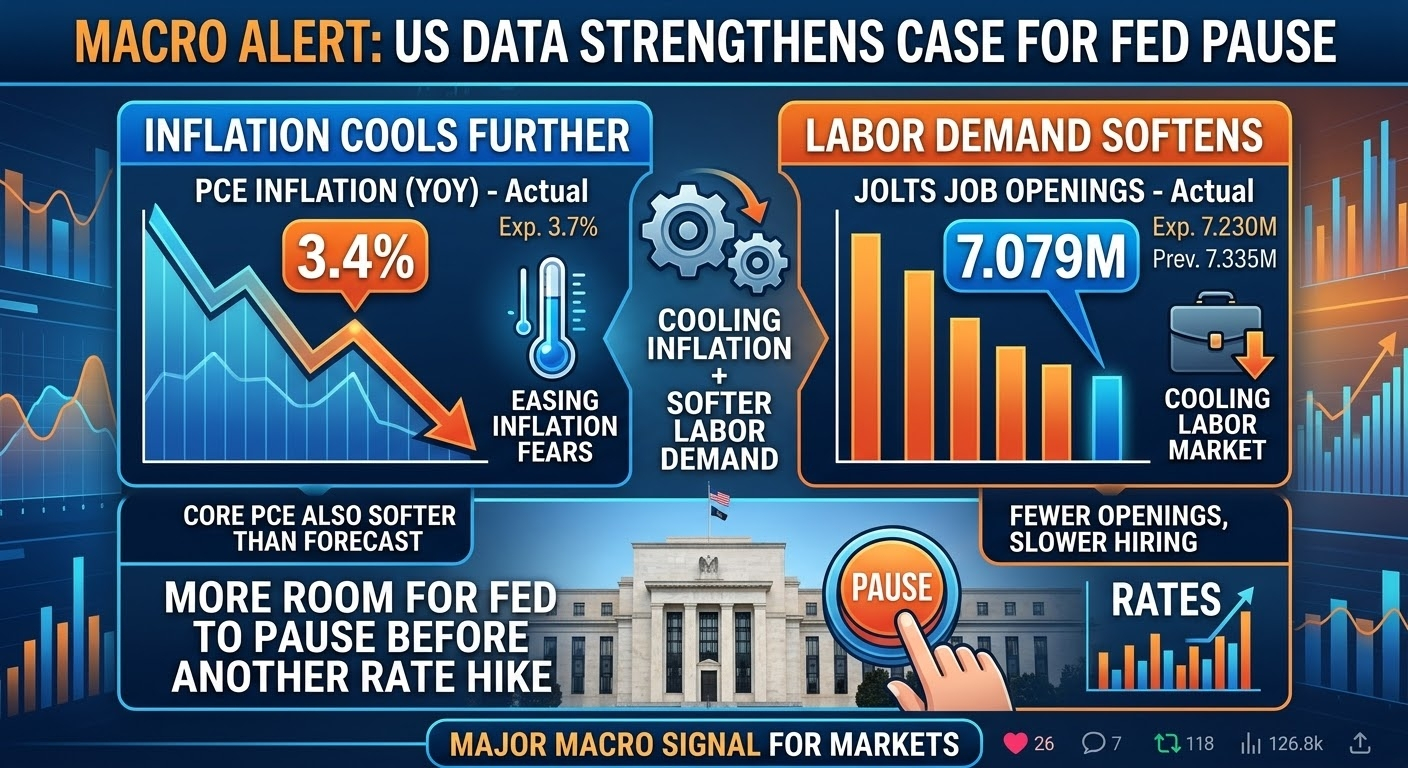
This macro setup presents a classic "bad-is-good" narrative for risk assets. When both inflation cools and the labor market softens simultaneously, it significantly reduces the pressure on the Federal Reserve to continue tightening policy.
### Key Takeaways from the Data
* PCE Disinflation (3.4% vs 3.7% Exp): As the Fed's preferred inflation gauge, a softer-than-expected headline and core reading suggests that restrictive interest rate policy is effectively pulling down price pressures without triggering an immediate structural break.
* Labor Market Normalization (7.079M JOLTS): The drop in open jobs signals that labor demand is cooling. This eases concerns over wage-push inflation while showing an economy transitioning toward a soft landing rather than an abrupt spike in unemployment.
* Policy Implication: A pause allows the Federal Reserve time to monitor lagged policy effects, giving both equities and broader risk markets temporary breathing room as terminal rate expectations shift.
While headline inflation remains above the Fed's 2% target, this dual signal aligns with the scenario needed to justify holding interest rates steady in the near term.