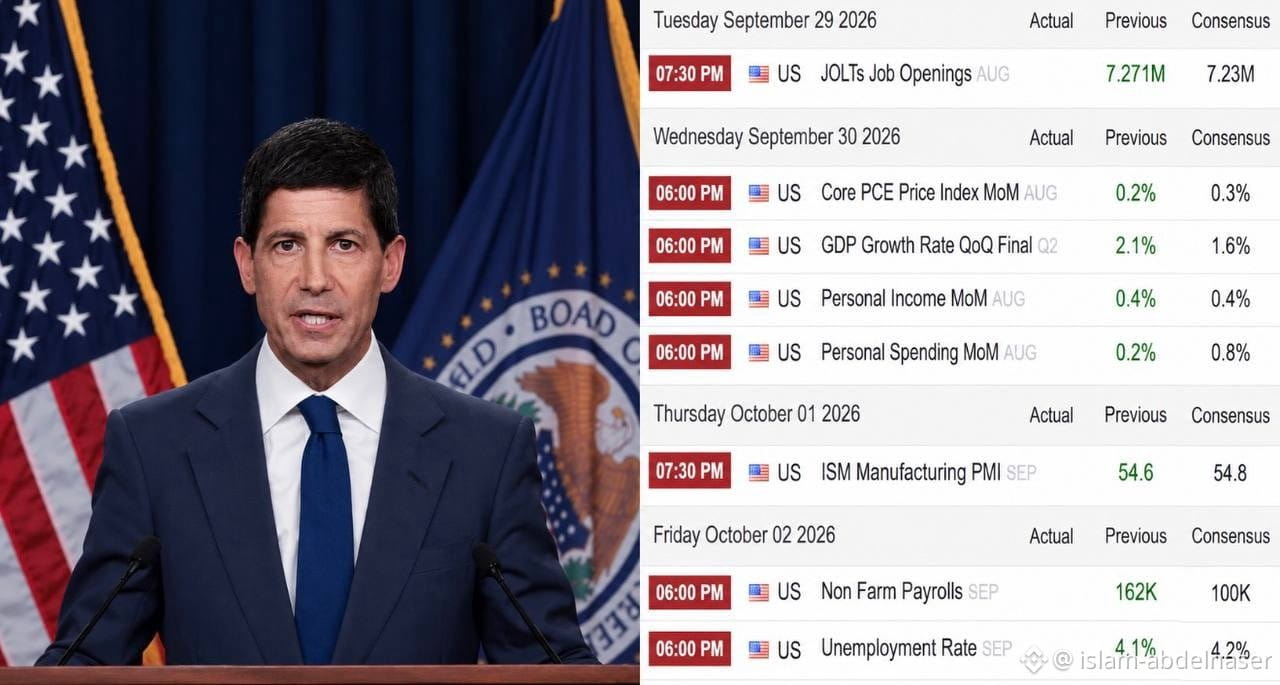
NEXT WEEK COULD COMPLETELY CHANGE THE FED’S OCTOBER RATE DECISION.
MONDAY: U.S. markets reopen with the Iran conflict and uncertainty over a possible deal still hanging over oil and inflation.
TUESDAY: August JOLTS job openings drop, giving the Fed a fresh look at whether the labor market is weakening or getting better.
WEDNESDAY: August PCE inflation and the final Q2 GDP estimate are released together.
The Fed gets fresh inflation and growth data at the same time.
THURSDAY: September ISM Manufacturing PMI drops.
August was 54.6, and a higher reading means economic activity is rising.
FRIDAY: September jobs data lands, including the unemployment rate, another major piece of the Fed’s labor market picture.
Inflation, GDP, jobs, and manufacturing data will drop in the same week.
Any signs of a strong labor market and rising inflation will almost lock another 25 bps rate hike in October.
MONDAY: U.S. markets reopen with the Iran conflict and uncertainty over a possible deal still hanging over oil and inflation.
TUESDAY: August JOLTS job openings drop, giving the Fed a fresh look at whether the labor market is weakening or getting better.
WEDNESDAY: August PCE inflation and the final Q2 GDP estimate are released together.
The Fed gets fresh inflation and growth data at the same time.
THURSDAY: September ISM Manufacturing PMI drops.
August was 54.6, and a higher reading means economic activity is rising.
FRIDAY: September jobs data lands, including the unemployment rate, another major piece of the Fed’s labor market picture.
Inflation, GDP, jobs, and manufacturing data will drop in the same week.
Any signs of a strong labor market and rising inflation will almost lock another 25 bps rate hike in October.