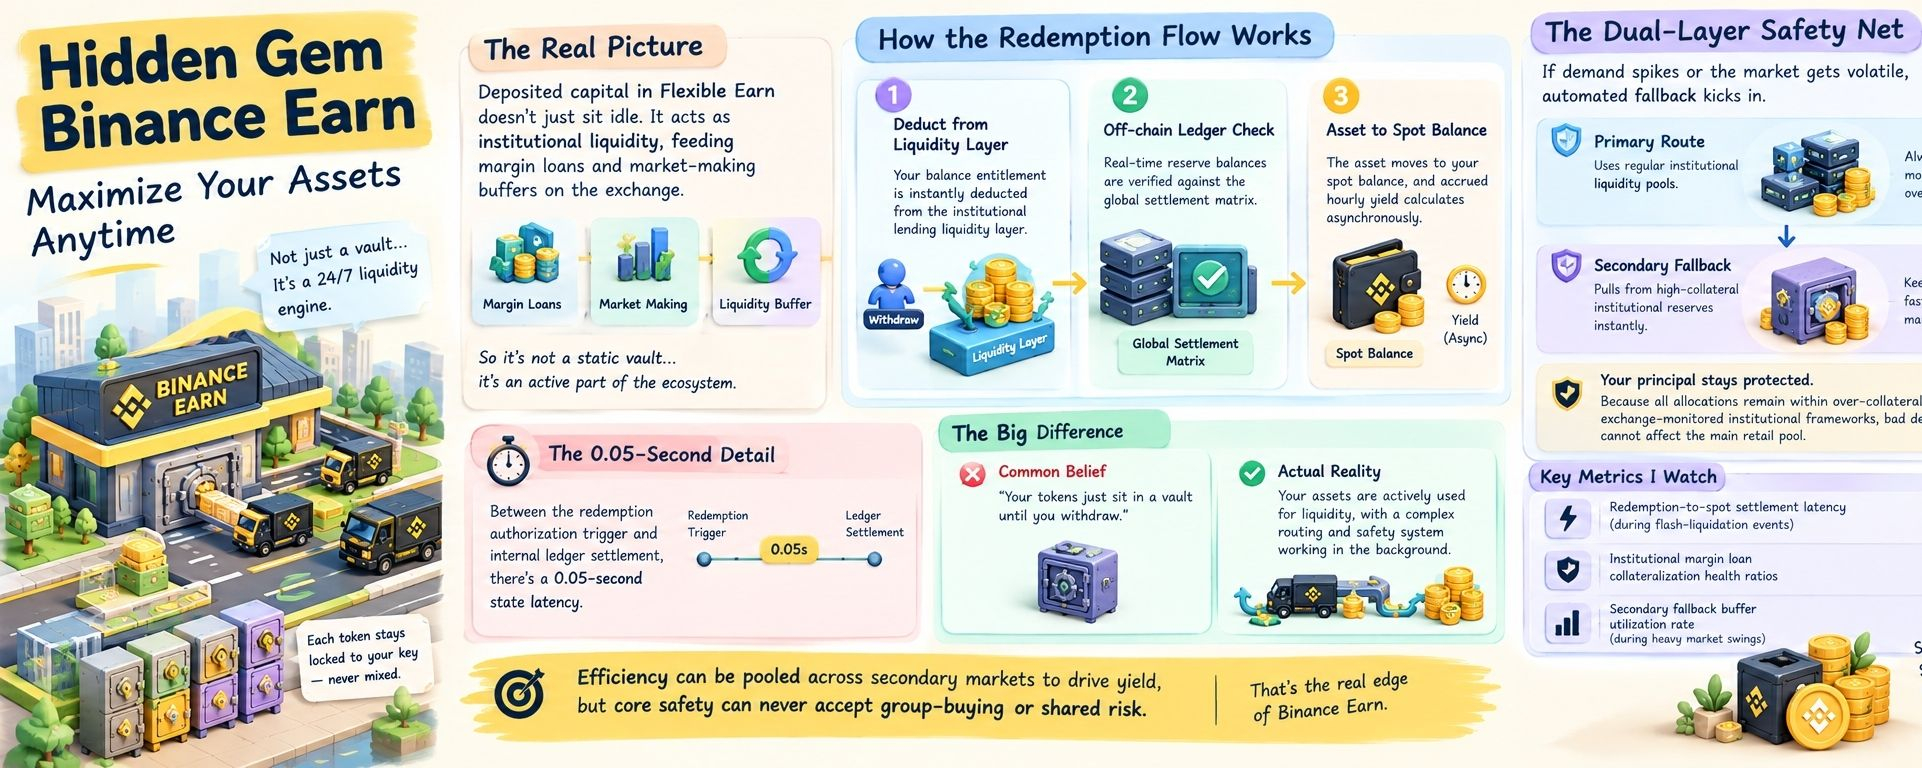
Late last night, while combing through the settlement parameters of Binance Simple Earn, I stumbled upon a intriguing 0.05-second state latency tucked between the redemption authorization trigger and internal ledger settlement. Most everyday market participants look at Binance Earn as a passive vault, operating under the naive assumption that deposited tokens remain sitting untouched in isolated digital vaults awaiting a withdrawal click. The underlying architecture tells a completely different story. Deposited capital in Flexible Earn acts as immediate, dynamic institutional liquidity that feeds over-the-counter margin loans and exchange market-making buffers. To allow seamless, 24/7 instant redemptions without slippage or order book distortion, the protocol relies on an automated dual-layer routing network. Think of it like a fleet of high-security armored delivery vans carrying thousands of individually tagged safe deposit boxes: the transport unit moves fluidly to support immediate citywide demand, but each box remains cryptographically locked and indexed to its owner’s exact key.
What captures my attention far more than base APY percentages is the precise multi-stage fallback flow engineered to preserve principal safety when volatility surges. Once a user triggers a flexible withdrawal, the system executes a rapid three-phase state transition. First, it instantly deducts the balance entitlement from the institutional lending liquidity layer; second, an off-chain ledger check verifies real-time reserve balances against the global settlement matrix; third, the asset state flips directly to the user's spot balance while accrued hourly yield calculates asynchronously in the background. If primary liquidity pools experience sudden demand spikes during market downturns, an automated secondary fallback route pulls immediately from high-collateral institutional reserves to maintain instantaneous redemptions. Because all allocations stay strictly within over-collateralized, exchange-monitored institutional lending frameworks, systemic bad debt cannot bleed into the primary retail capital pool.
Efficiency can be pooled across secondary markets to drive yield, but core safety can never accept group-buying or shared risk. Moving forward as this architecture operates at scale, I am consistently monitoring three primary operational health metrics: the average redemption-to-spot state settlement latency during flash-liquidation events, institutional margin loan collateralization health ratios, and the secondary fallback buffer utilization rate during heavy market swings.