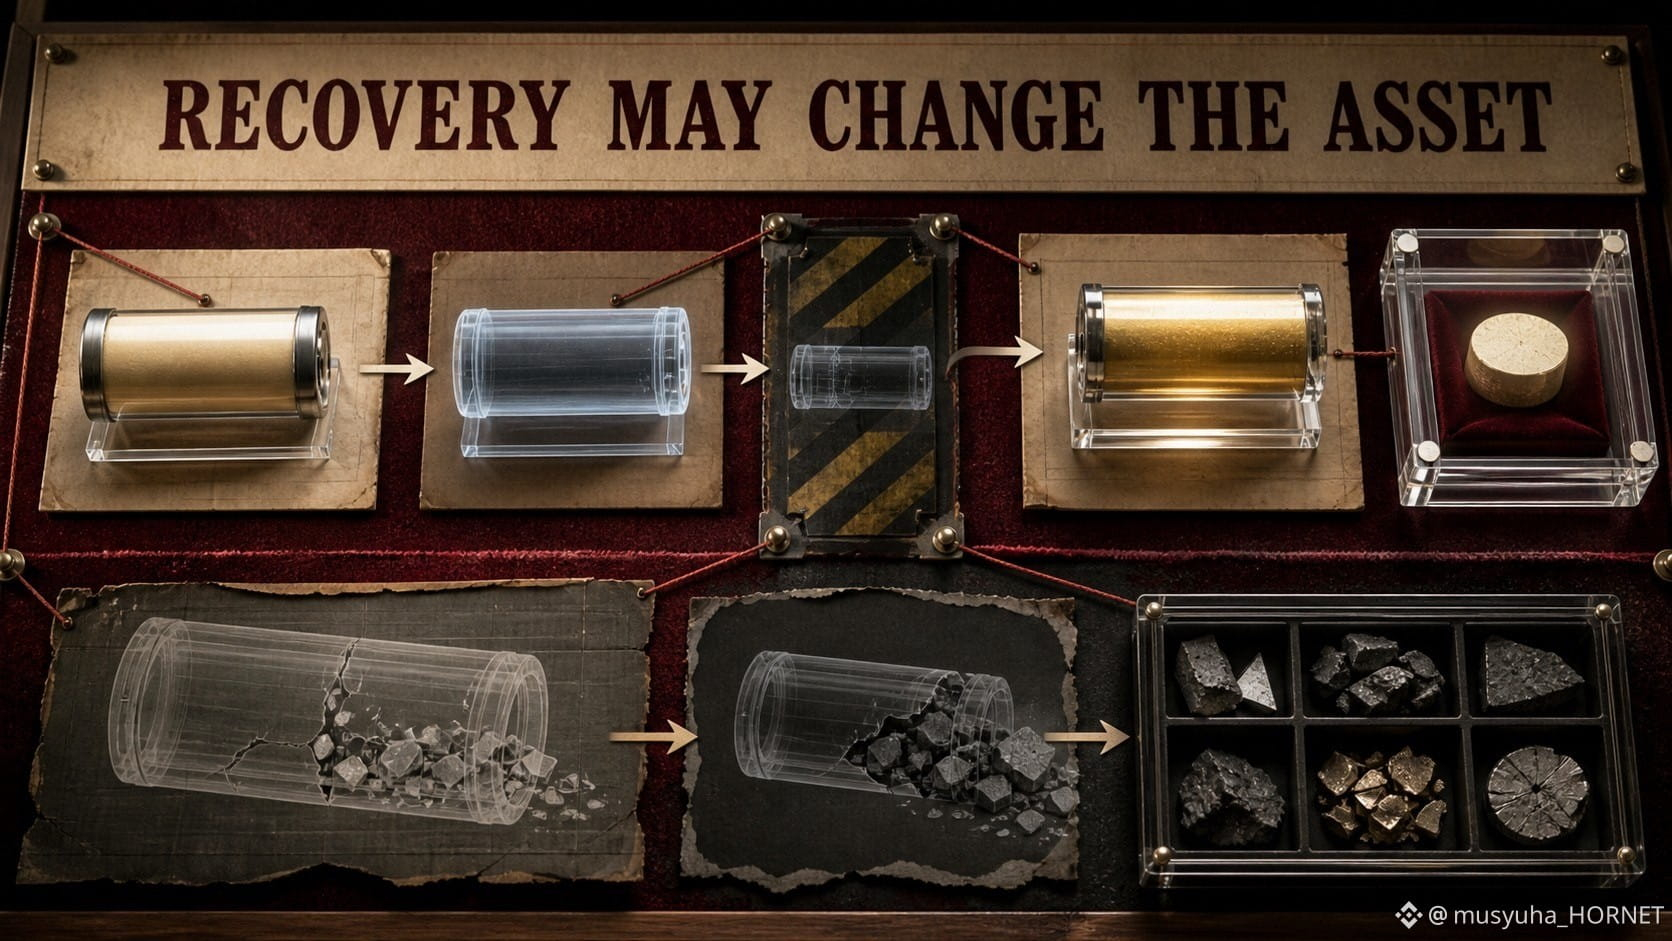
Receiving collateral is not the same as receiving the debt asset you originally expected.
TermMax describes a physical-delivery mechanism for cases where liquidation does not fully recover the debt token. FT holders can receive a proportional share of delivered collateral rather than being left only with an unrecovered claim.
That mechanism can improve recovery, but it changes the asset-level risk.
A lender who expected USDC may finish with part of the collateral instead. The value then depends on the collateral price, liquidity and the cost of converting it. For a vault, delivered collateral can also affect withdrawal timing if there is not enough idle liquidity.
I would therefore audit a fixed-rate position in two layers:
1. Payment layer: face value and maturity.
2. Recovery layer: collateral type, LLTV, oracle, liquidation liquidity and delivery rules.
The deeper lesson is that “fixed” describes the contractual rate, not the exact asset composition under every stress scenario.
Sources checked: TermMax Docs — Protocol FAQ; Risks.
@TermMax #TermMax
TermMax describes a physical-delivery mechanism for cases where liquidation does not fully recover the debt token. FT holders can receive a proportional share of delivered collateral rather than being left only with an unrecovered claim.
That mechanism can improve recovery, but it changes the asset-level risk.
A lender who expected USDC may finish with part of the collateral instead. The value then depends on the collateral price, liquidity and the cost of converting it. For a vault, delivered collateral can also affect withdrawal timing if there is not enough idle liquidity.
I would therefore audit a fixed-rate position in two layers:
1. Payment layer: face value and maturity.
2. Recovery layer: collateral type, LLTV, oracle, liquidation liquidity and delivery rules.
The deeper lesson is that “fixed” describes the contractual rate, not the exact asset composition under every stress scenario.
Sources checked: TermMax Docs — Protocol FAQ; Risks.
@TermMax #TermMax