
Apple Delivers Record Revenue, but Rising Costs Cloud Its Earnings Outlook
Apple’s latest earnings beat Wall Street expectations, yet rising memory prices, supply constraints and a challenging holiday-quarter outlook are raising fresh questions about the company’s profitability.
Apple has delivered another record-breaking quarter, but the technology giant’s latest financial results reveal a more complicated picture beneath the headline numbers.
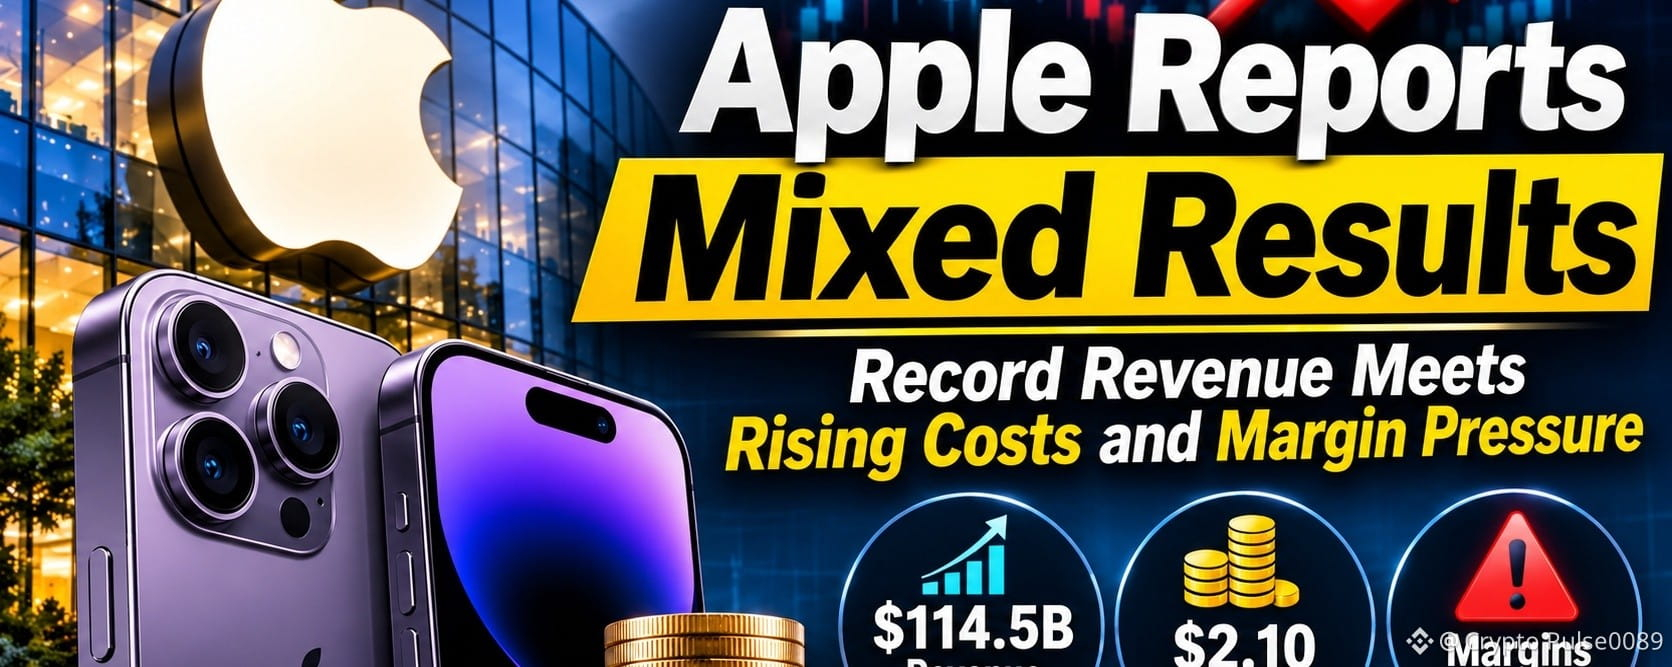
The company reported fiscal fourth-quarter revenue of $114.5 billion for the quarter ended September 26, 2026, representing a 12% increase from a year earlier. Earnings per share reached $2.10, exceeding analyst expectations, while net income climbed to $30.71 billion.
The results mark a strong start for CEO John Ternus, who took over from Tim Cook in September. However, investors are weighing Apple’s impressive sales performance against rising production costs and growing uncertainty about its profit margins.
iPhone remains Apple’s biggest growth engine
The iPhone continued to lead Apple’s financial performance, generating $57.6 billion in revenue, up approximately 17% year over year.
Services revenue also reached a new record of $31.6 billion, highlighting the continued importance of Apple’s ecosystem of subscriptions and digital services. Mac revenue delivered another positive surprise, while several other product categories struggled to keep pace.
The company’s performance demonstrates that demand for its premium devices remains resilient, even as consumers and businesses face a challenging economic environment.
The hidden pressure behind the earnings beat
Despite the strong headline figures, Apple faces a growing cost challenge.
Higher memory prices are putting pressure on profitability, while expenses associated with the development and rollout of Siri’s AI capabilities are adding to the company’s spending.
Apple reported a gross margin of 47.9% for the September quarter, but management expects that figure to fall to between 45% and 46% in the December quarter.
The company also benefited from tariff refunds during the latest reporting period, which added approximately $0.05 to earnings per share. This means investors must look beyond the headline earnings beat to understand the underlying strength of Apple’s business.
Holiday quarter becomes the real test
Apple expects revenue growth of approximately 7% to 10% year over year for the December quarter, traditionally one of its most important sales periods.
The outlook suggests that demand remains healthy, but rising component costs and supply limitations could make it more difficult for Apple to translate higher sales into stronger profits.
For investors, the key question is no longer simply whether Apple can sell more devices. It is whether the company can protect its margins while continuing to invest in artificial intelligence and maintain its competitive position.
What it means for the market
Apple’s latest results reinforce the strength of its consumer business, but they also highlight a broader challenge facing the technology sector: strong demand does not automatically translate into expanding profit margins.
The company’s ability to manage memory costs, maintain product availability and turn AI investments into commercially valuable services will be crucial in the months ahead.
Bottom line: Apple’s earnings were stronger than expected, but the market now has to decide whether record revenue can overcome rising costs. The December quarter may provide the clearest indication of whether Apple’s growth story is entering another powerful phase—or facing a more difficult period.
This article is for informational purposes only and does not constitute investment advice.