$SPCXB : Exploring Dollar‑Based Volume Comparisons
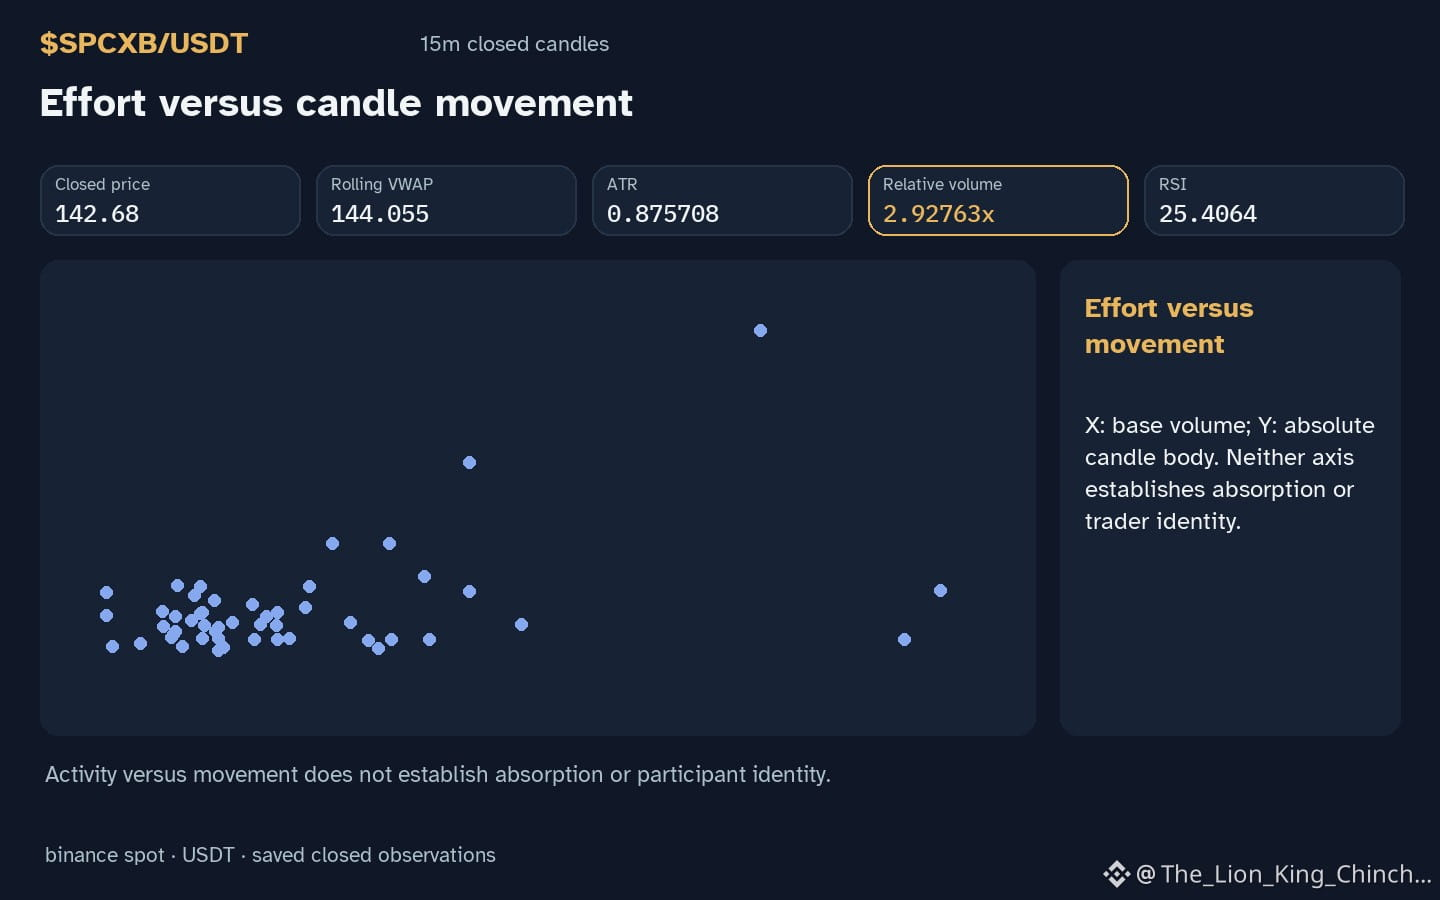
Why does $SPCXB show a down hourly direction while its quote volume stays above baseline? The observation invites a thought experiment: if every peer were measured by dollar‑denominated volume, could the risk profile become more comparable?\n\nA hypothetical decision would treat each asset’s quoted volume, such as 2.94062e+07, as the common metric. This removes the distortion caused by differing token supplies and price levels. When we look at the peer set, $ETH moves up hourly but its volume does not rise above its baseline, whereas $GRAM also moves up and its volume exceeds baseline. The contrast illustrates that identical directional moves can accompany divergent dollar participation.\n\nWhere the analogy helps is in normalizing exposure: a trader allocating a fixed dollar amount to each coin would face similar capital at risk if the quoted volumes align. Where it fails is the assumption that volume alone predicts price impact; liquidity depth, order‑book structure and market microstructure remain unaddressed.\n\nA self‑check suggests re‑evaluating the interpretation by monitoring how quoted volume reacts to price changes on an hourly basis and comparing the magnitude of 2.92763 across peers. If the dollar‑based view diverges from token‑count volume, the hypothesis may need refinement.
Probabilistic market research, not a recommendation or guaranteed return.
For a wider view: $ETH has hourly direction up and volume not above its baseline; $GRAM has hourly direction up and volume above its baseline. This alone does not establish correlation.
Same move, but the same risk?
#SPCXB
Why does $SPCXB show a down hourly direction while its quote volume stays above baseline? The observation invites a thought experiment: if every peer were measured by dollar‑denominated volume, could the risk profile become more comparable?\n\nA hypothetical decision would treat each asset’s quoted volume, such as 2.94062e+07, as the common metric. This removes the distortion caused by differing token supplies and price levels. When we look at the peer set, $ETH moves up hourly but its volume does not rise above its baseline, whereas $GRAM also moves up and its volume exceeds baseline. The contrast illustrates that identical directional moves can accompany divergent dollar participation.\n\nWhere the analogy helps is in normalizing exposure: a trader allocating a fixed dollar amount to each coin would face similar capital at risk if the quoted volumes align. Where it fails is the assumption that volume alone predicts price impact; liquidity depth, order‑book structure and market microstructure remain unaddressed.\n\nA self‑check suggests re‑evaluating the interpretation by monitoring how quoted volume reacts to price changes on an hourly basis and comparing the magnitude of 2.92763 across peers. If the dollar‑based view diverges from token‑count volume, the hypothesis may need refinement.
Probabilistic market research, not a recommendation or guaranteed return.
For a wider view: $ETH has hourly direction up and volume not above its baseline; $GRAM has hourly direction up and volume above its baseline. This alone does not establish correlation.
Same move, but the same risk?
#SPCXB