#CanMicrosoftDeliverOnAI
Microsoft is set to report its Q1 FY27 earnings today (October 28), marking a significant moment for its AI initiatives.
Key insights include:
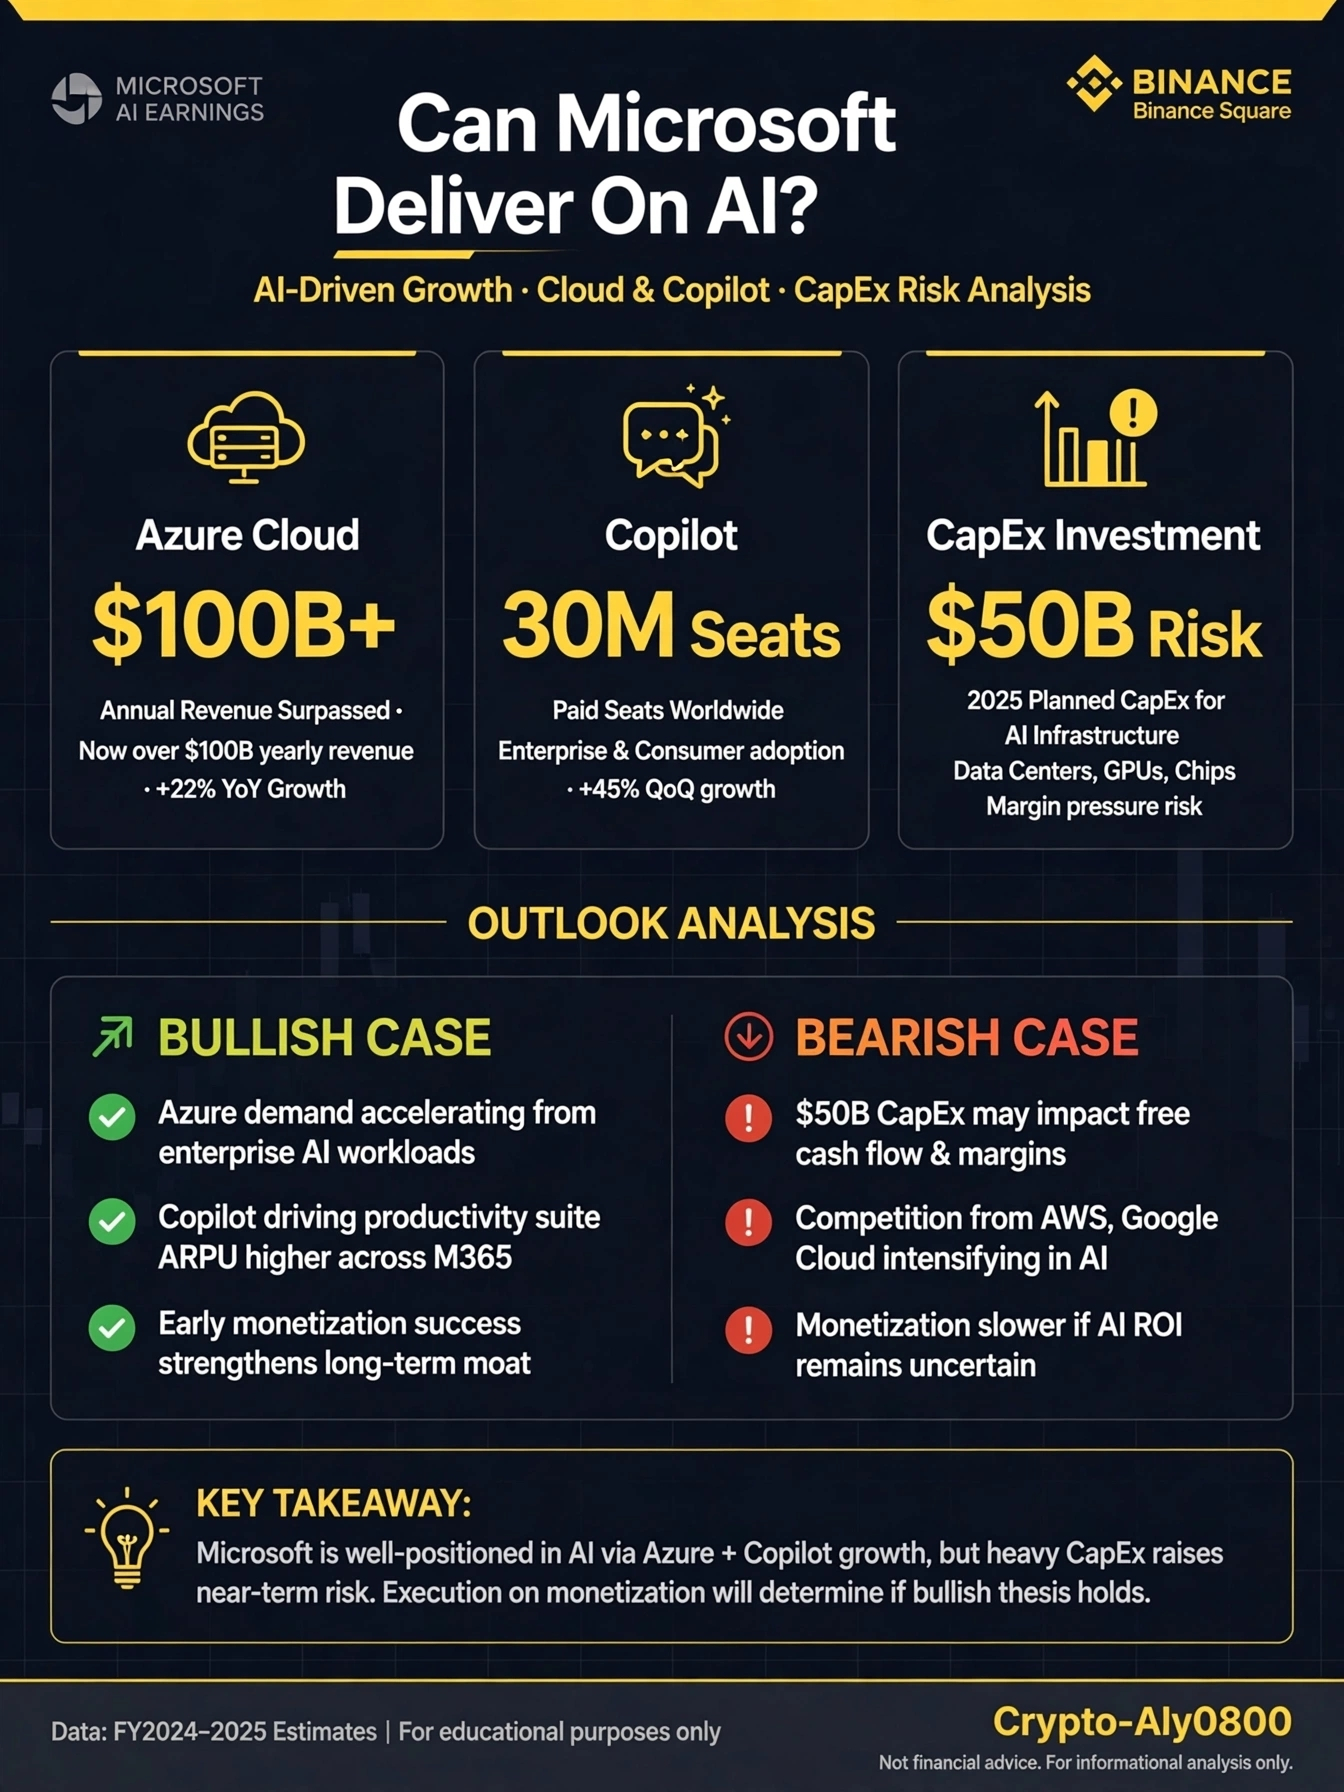
1. Azure Cloud Revenue Azure has surpassed $100 billion in annual revenue for the first time, boasting a 41% year-over-year growth in the last quarter.
Demand appears to be outpacing supply, indicating robust customer interest.
2. Microsoft 365 Copilot Adoption
Microsoft 365 Copilot has achieved over 30 million paid seats, demonstrating successful monetization and adoption among paying enterprise customers.
3. Capital Expenditure Concerns
Microsoft has projected more than $50 billion in capital expenditures for the quarter.
Questions arise regarding whether significant spending on AI infrastructure could negatively impact profit margins and free cash flow.
Outlook Analysis: - Bullish Perspective:
Growth in Azure and the monetization of Copilot, with Microsoft having control over both the underlying infrastructure and the applications, creates a competitive advantage.
Bearish Perspective: High capital expenditures may impact cash flow without a clear return on investment, which could lead to a decline in stock value despite meeting expectations.
Key Question: Will Azure achieve approximately 45% growth, and will the growth in Copilot seats continue?
The answers to these questions will influence the stability of Microsoft’s stock.
This situation extends beyond Microsoft; if Azure continues to grow, it could support the broader narrative around AI infrastructure investments, impacting companies such as Nvidia, OpenAI, and those involved in AI-related cryptocurrencies.
What is your perspective—should the focus be on patience or profitability?
#Microsoft #AI板块强势进击 #BİNANCE