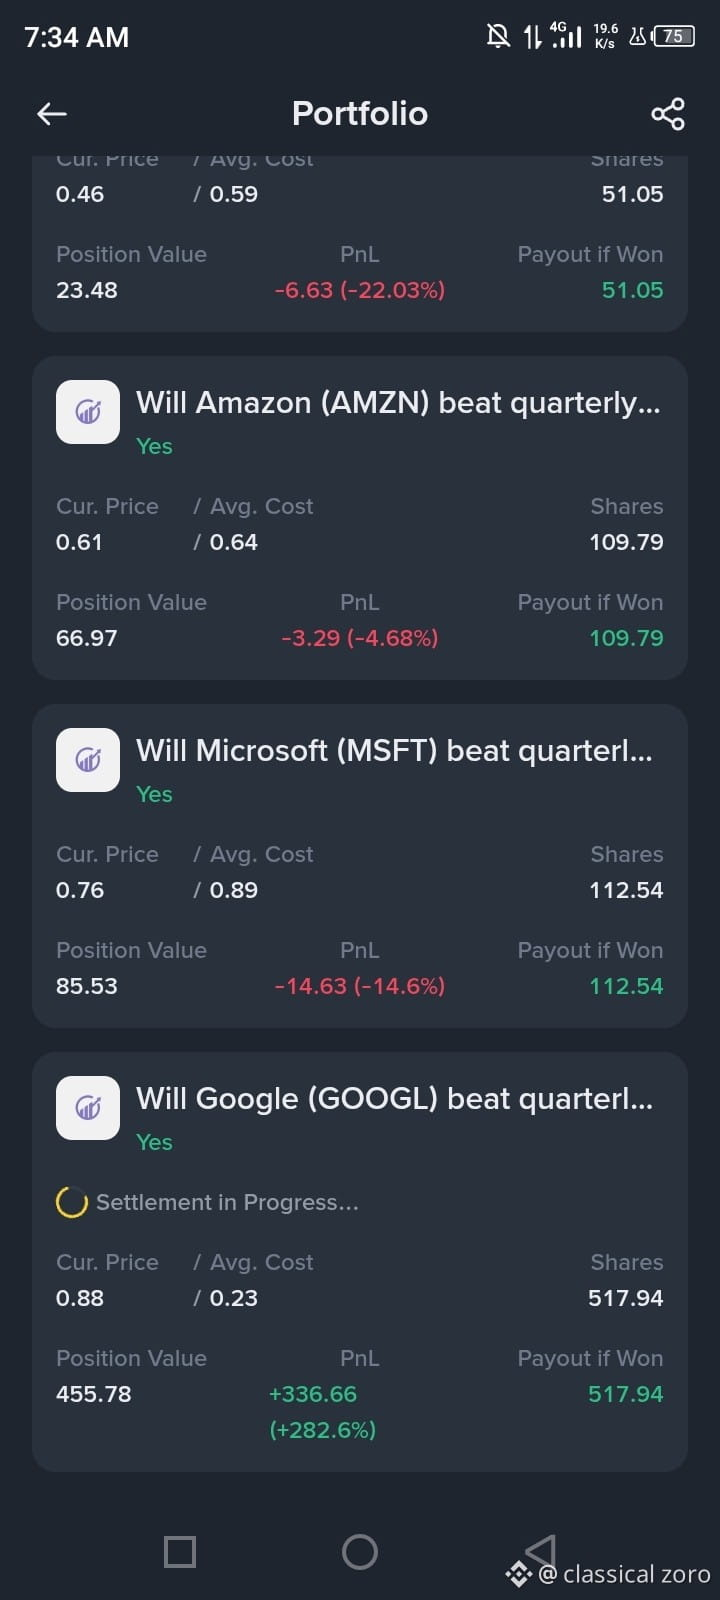
Up +282% on GOOGL Yes – Here's Why I'm Still Holding Until the Print 🚀
Look at this conviction. When the crowd was unsure, I locked in my "Yes" on Google beating quarterly earnings. Now, sitting on a +282% gain with 517 shares and settlement in progress, I'm not flinching.
Here is the data behind the position:
1. Cloud is the Growth Engine
Google Cloud is no longer a side project—it's a monster. Last quarter, Cloud revenue surged 82% YoY to $24.8B, crushing estimates. The backlog is now sitting at $514B, with roughly half expected to convert to revenue over the next 24 months. External TPU sales are just starting to ramp, opening a new multi-billion dollar revenue stream through 2028.
2. The Bar is Low Enough to Clear
Consensus sits around $3.00–$3.02 EPS on roughly $127.9B in revenue. The LSEG StarMine SmartEstimate implies a surprise of just 0.31%—essentially a coin toss. But with 18 analyst upgrades in the past month versus 11 downgrades, the momentum is on the bulls' side.
3. Gemini 4 Argon is a Differentiator
Google's latest model is outscoring leading models from OpenAI and Anthropic on several benchmarks, particularly in cybersecurity. Analysts at Truist note this is evidence Alphabet has "closed the frontier-model gap." Better adoption at competitive prices could pressure margins, but the volume story is intact.
4. Search Isn't Dead
Despite fears of AI eating search, third-party data supports durable Search trends. Search & Other revenue grew 17% last quarter to $63.3B. Google continues to dominate traffic even as AI adoption rises.
The Risk?
Capex. Management raised 2026 guidance to $195–$205B, and free cash flow turned negative for the first time since 2004. If the print shows spending outpacing revenue conversion, the stock could drop—even on a beat. Over the past four quarters, Google beat EPS every time, yet the stock closed higher only twice.
#BinancePick #EarningsSeason