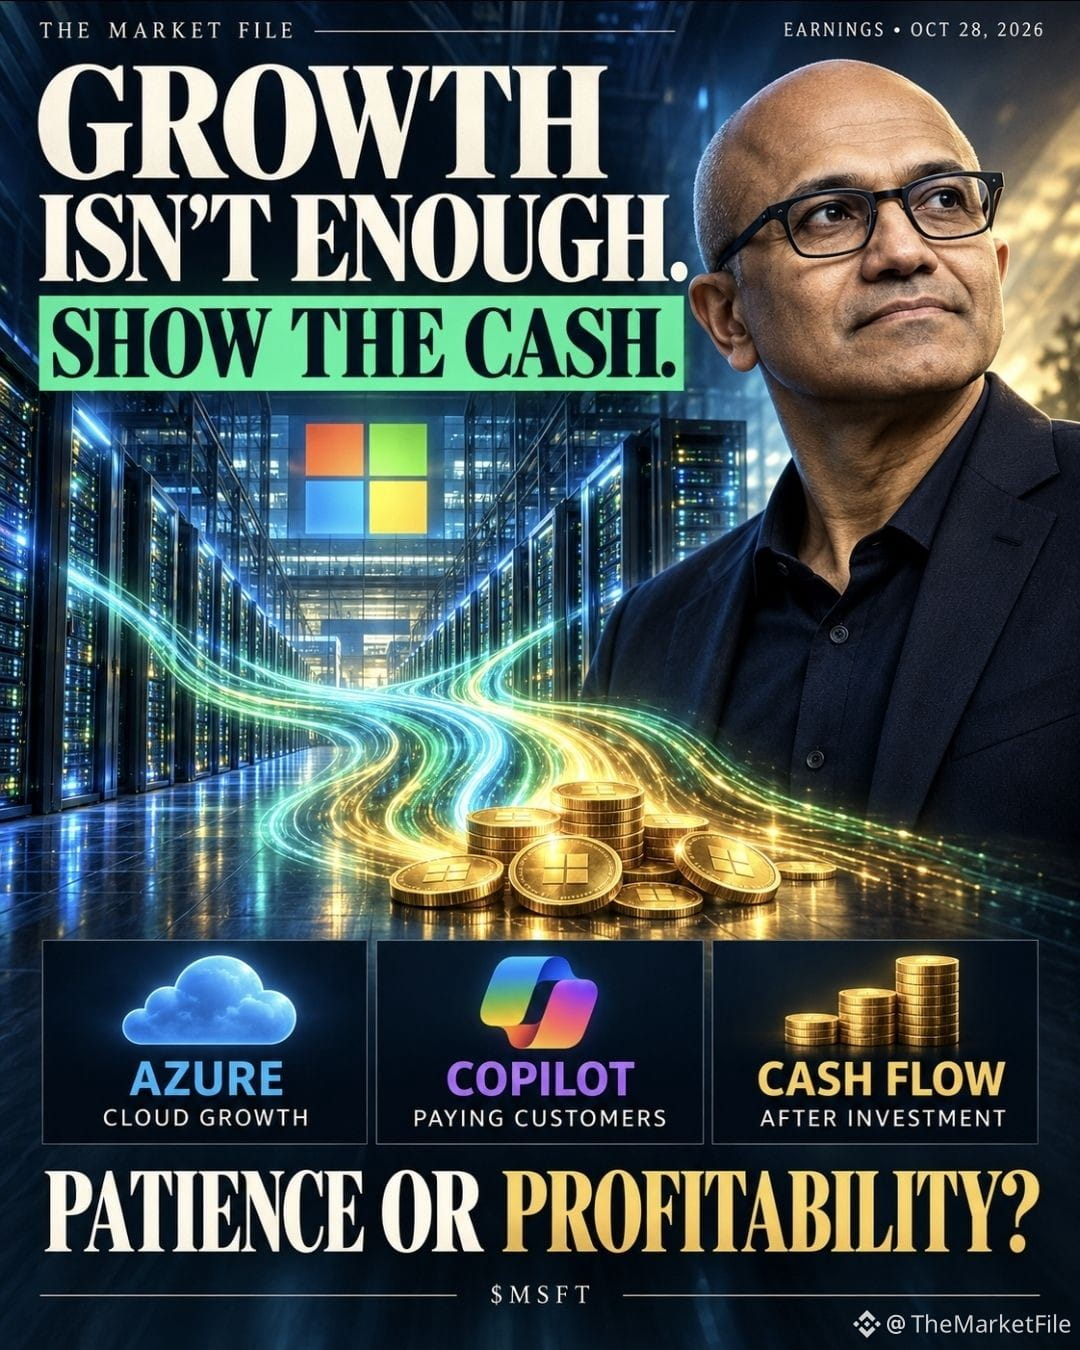
🚨 Microsoft can beat expectations… and still fall.
The question is how fast it must grow to justify the AI bill.
THE MARKET FILE — AI FACES ITS TEST
October 27, 2026
Microsoft reports earnings on October 28. Here are the benchmarks from its own guidance.
☁️ AZURE: IS GROWTH ENOUGH?
The company projected roughly 45% growth in constant currency.
My test: does new capacity translate into revenue, and does the next outlook sustain that momentum?
🤖 COPILOT: PAYING USERS
Microsoft ended fiscal 2026 with over 30 million paid Microsoft 365 Copilot seats.
I want to see growth in those seats and revenue per customer. Adding an AI feature doesn’t automatically mean monetizing it.
💰 THE BILL: OVER $50 BILLION
That was the quarter’s projected CapEx: total capital expenditure, not exclusively AI spending.
I’m watching margins, free cash flow and how much additional investment growth requires.
These are pre-earnings benchmarks, not results for the quarter Microsoft is about to report.
📖 MY POSITION:
Microsoft has an advantage: it can sell infrastructure through Azure and tools built on top through Copilot.
But that advantage must show up in the numbers.
🟢 Strong growth, paying customers and an outlook supporting margins and cash flow would build confidence.
🔴 A growing bill without enough improvement in monetization would concern me.
Results can beat consensus and still disappoint against expectations already reflected in the share price. That’s the risk of buying a great company with enormous expectations.
💬 If Azure grows strongly but investment weakens cash flow, do you give Microsoft more time—or demand results?
Pick: PATIENCE or PROFITABILITY. What number would make you switch sides?
$MSFTB $MSFT
#EarningsSeason #Microsoft
#CanMicrosoftDeliverOnAI