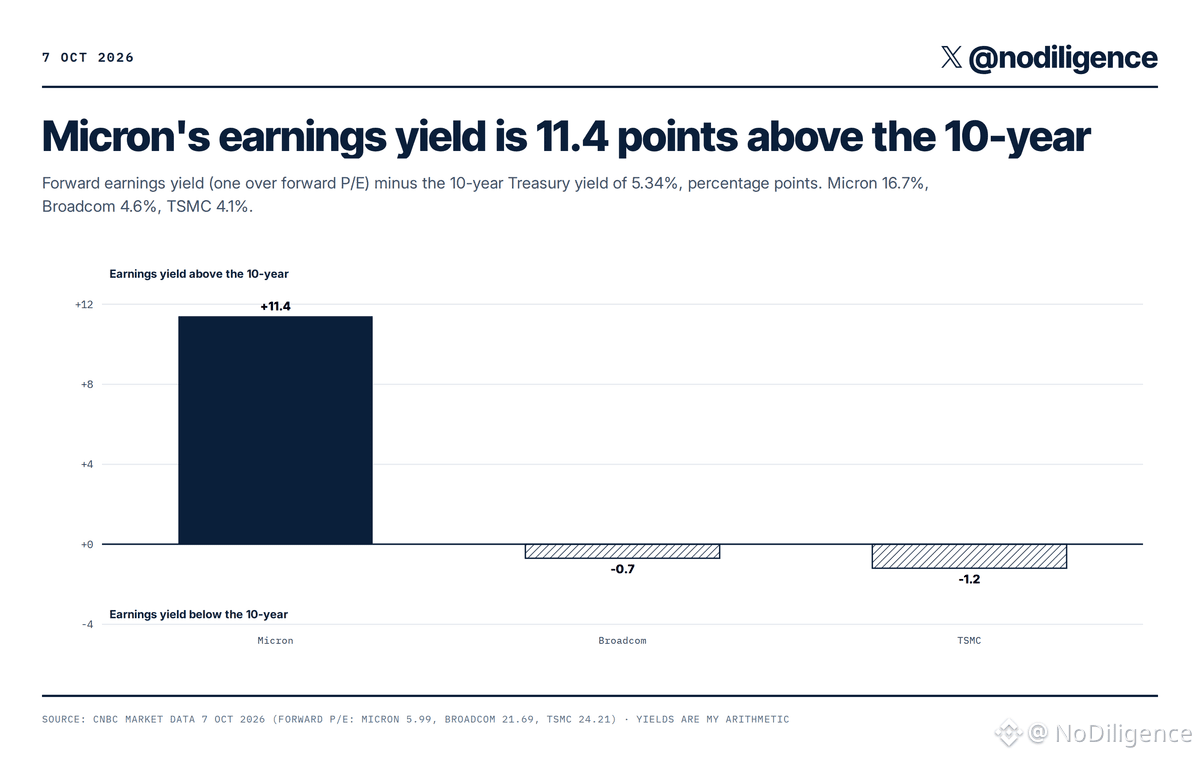
micron trades at about 6x next year's earnings, broadcom at about 22 and TSMC at about 24. turn those into earnings yields and micron's is about 16.7%, broadcom's about 4.6% and TSMC's about 4.1%, both of those below the 10-year at 5.34% this morning.
so the market is pricing broadcom's and TSMC's earnings as safer than a treasury and micron's as a peak that goes away, even though all three are selling into the same AI capex budgets.
a 6x multiple on memory is a bet that memory prices fall hard within a year or two, and right now the talk in korea is HBM prices more than doubling in 2027.
if memory prices hold, micron is the cheapest way to own the exact same spend. and if they don't, it's because the hyperscalers stopped paying up for capacity, which is broadcom's custom chip budget and TSMC's wafer orders too, so a 4% earnings yield isn't as safe as it looks next to a 5.34% treasury.
i'm still bullish. i think market is slowly understanding the economics of memory and how it all works. Micron still is the safest bet out there.
$MUB $AVGOB