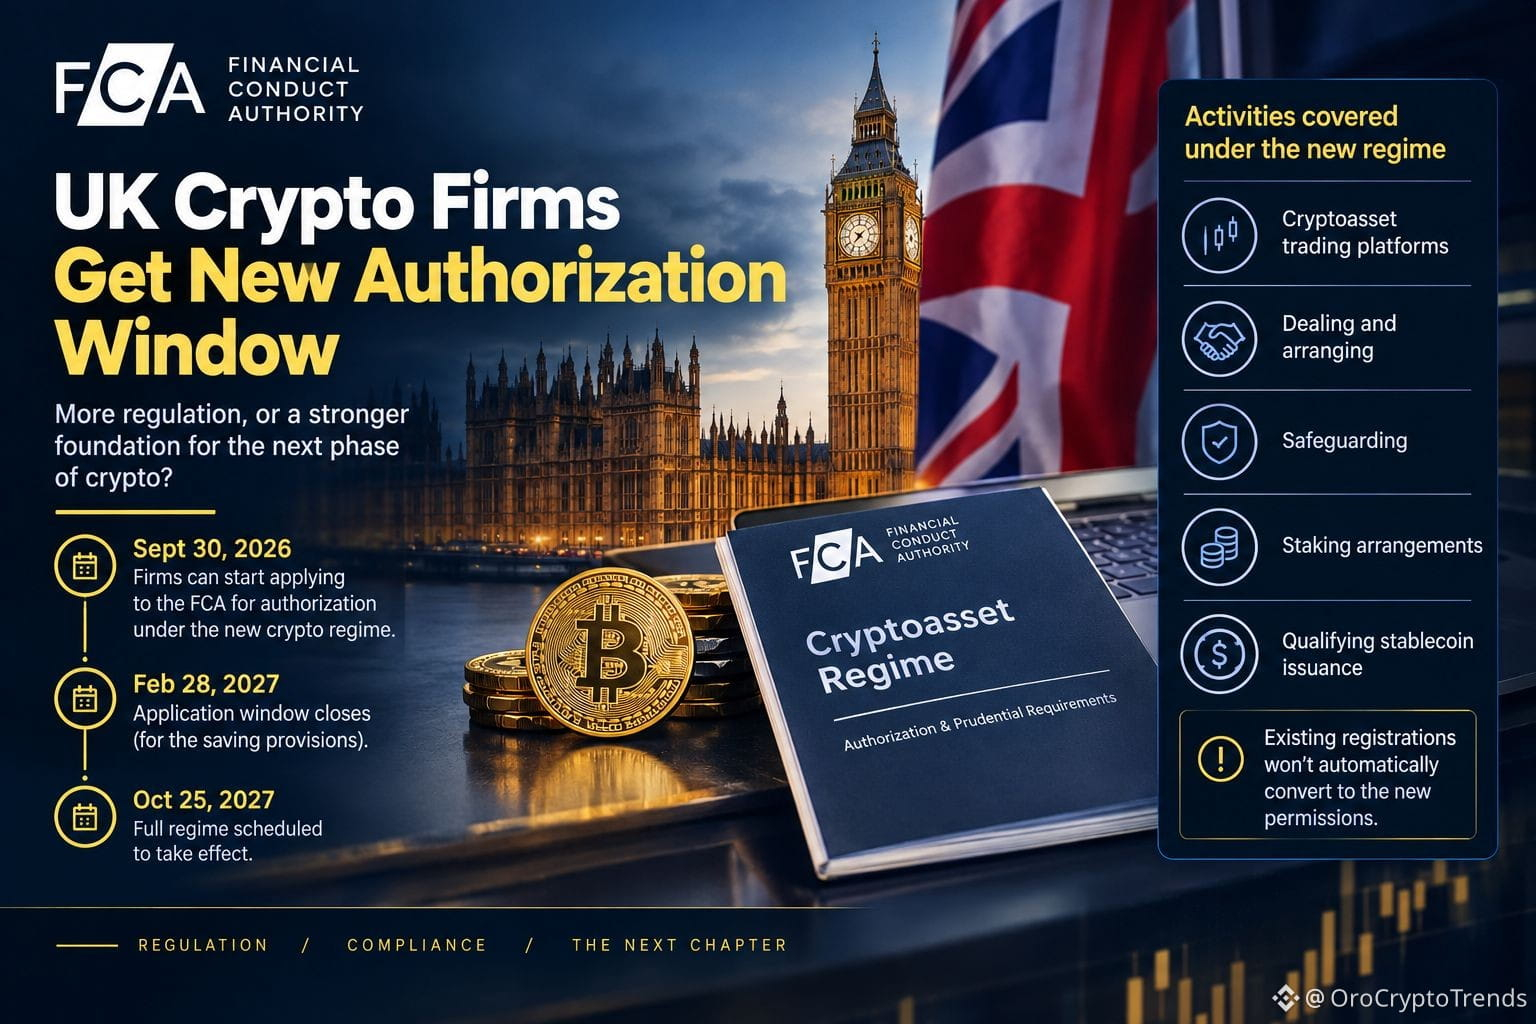
September 30 is a bigger date for UK crypto than the headline makes it sound.
The FCA’s new authorization window opens today, and firms have until February 28, 2027 to apply if they want to use the relevant saving provisions. The wider regime is scheduled to take effect on October 25, 2027.
What catches my attention isn’t simply “more crypto regulation.”
It’s that authorization is becoming part of the actual operating infrastructure.
Trading platforms, dealing and arranging, safeguarding, staking and qualifying stablecoin issuance are among the activities coming inside the new framework. And existing registrations won’t automatically turn into the new permissions.
That changes the economics.
A crypto business operating in the UK will increasingly have to treat compliance, controls, custody and reporting as part of the product itself — not something sitting around the edges of the business.
And there’s a real trade-off here.
Higher standards can strengthen consumer protection and market integrity. But the cost of meeting those standards could also affect which firms can economically serve UK users.
So I’m less interested in whether this is “bullish” or “bearish” for crypto.
The more interesting question is which business models still work when regulation becomes part of the infrastructure stack.
Still trying to figure out what this actually changes.