$QNT The S&P 500 closed at 7,670.84 (-0.16%), the Nasdaq at 26,797.54, and the Dow at 51,349.92. The S&P is roughly flat for September but still up over 12% YTD. VIX is about 16, which is calm relative to the rate stress.
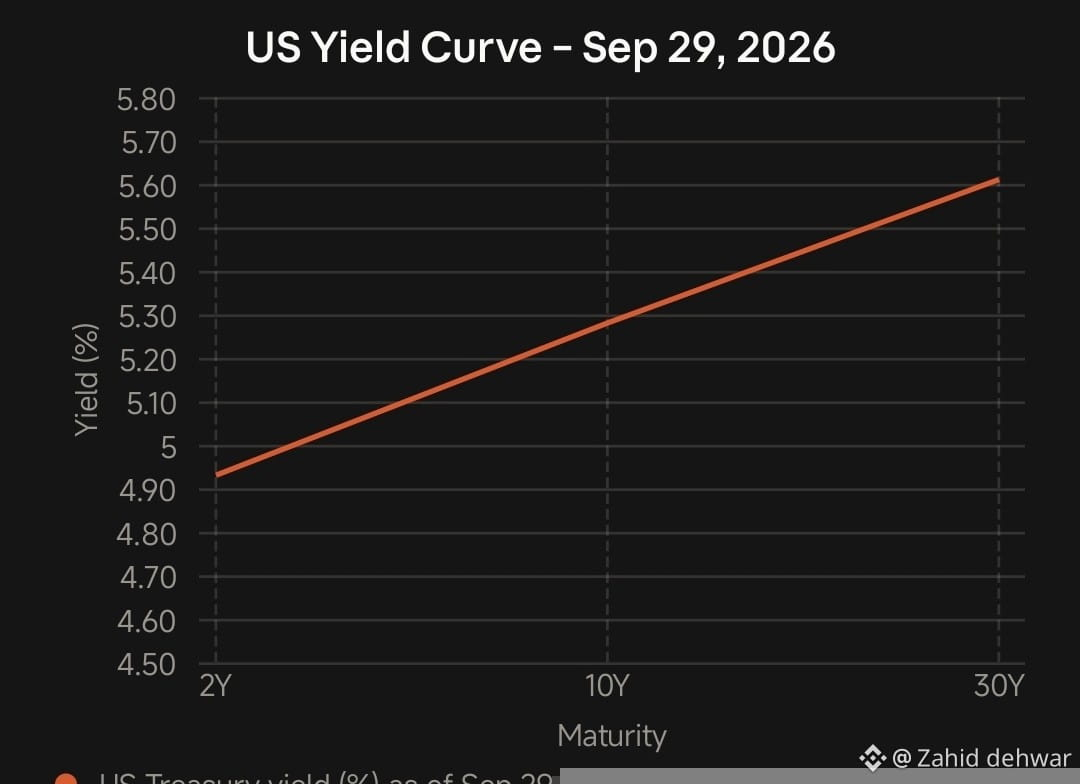
The main driver is rates, not equities: The 10-year yield is at 5.28% and the 30-year at about 5.61%, a 20-year high, while the 2-year is near 4.93%. The curve is upward sloping. That is a term-premium shock, not a recession signal.
Other factors:
Financials: The S&P financials index is down 6.3% in September, its worst month since March 2023. (CNBC)
Breadth: The S&P 500 posted 4 new highs against 29 new lows, and the Nasdaq 40 against 249. Leadership is narrow. The index is held up by a few mega-caps. (Yahoo Finance)
Oil/geopolitics: Crude is near $89, and the Iran/Hormuz talks are moving oil and yields.
Gold: About $4,180–4,210.
Catalysts: PCE and GDP today, ISM on Oct 1, and September payrolls on Oct 2. (Charles Schwab)
Bias: Cautious neutral. Falling breadth, rising long yields, and an oil shock argue for smaller size and hedges. A hot pay rolls print could push yields higher and pressure equity multiples.
@Wolf_king88 @Ihtisham_Ul Haq @Anndy Lian @Zetoshi X @CZ @Ismeidy