#earningsseason 🔥 $MU EARNINGS: BULLISH — BUT THE REAL TEST IS FY2027
Micron reports FY2026 Q4 earnings tomorrow, and the setup is bigger than one earnings beat.
My bias: Fundamentally bullish — but I wouldn’t chase MU blindly before the print.
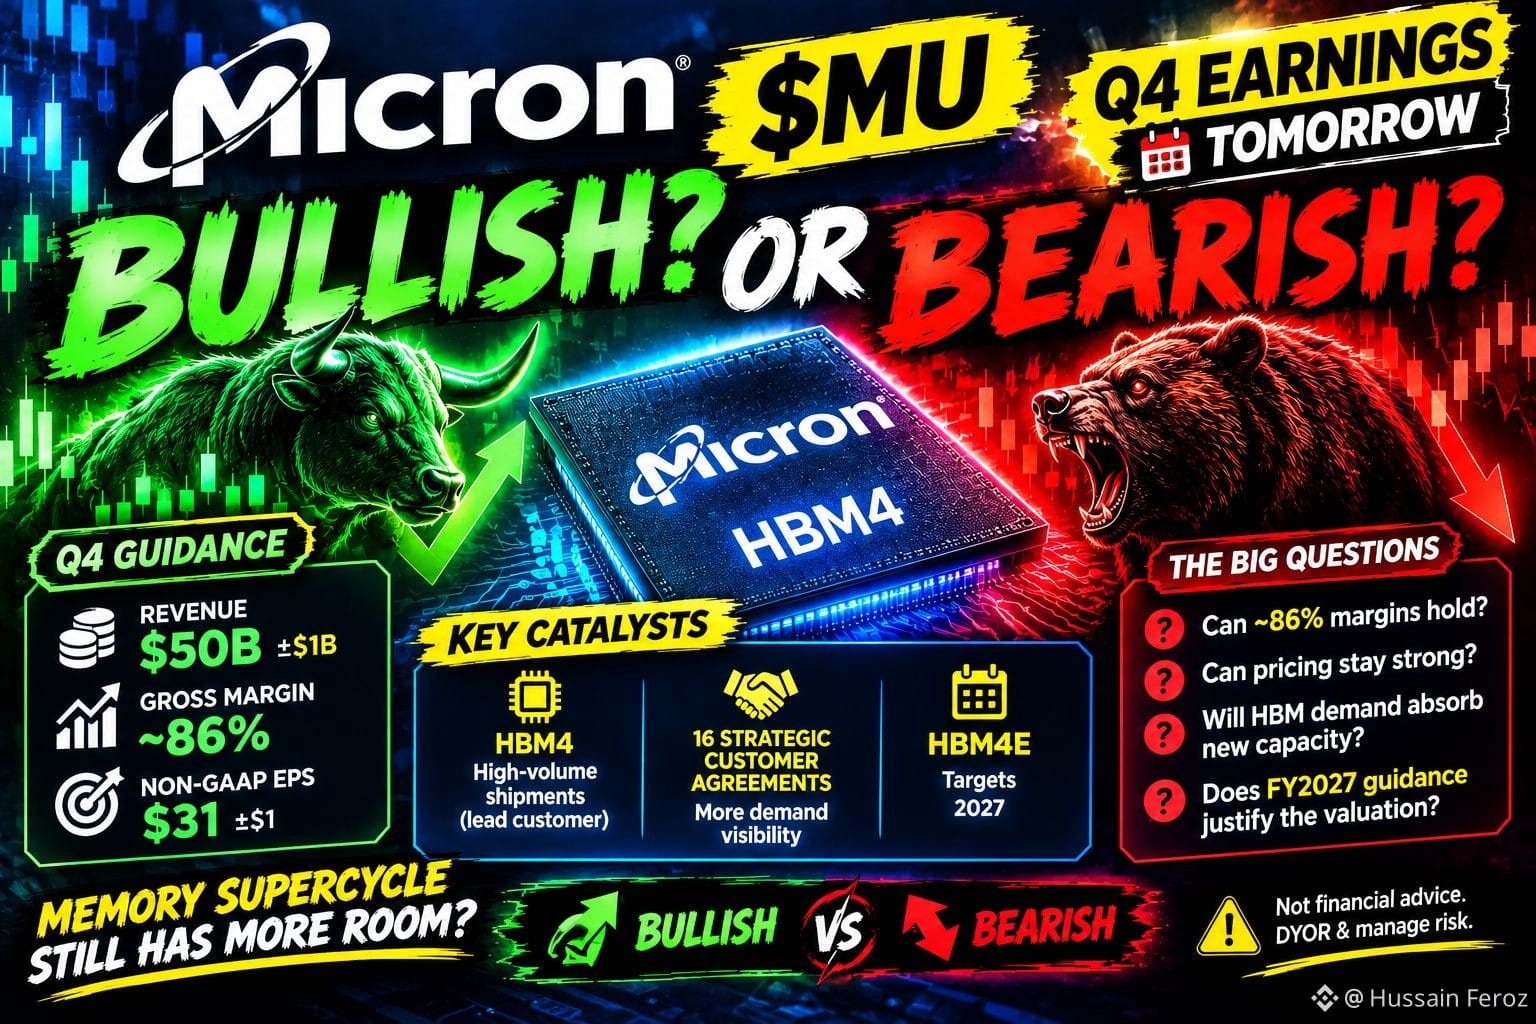
Micron’s Q4 targets are already aggressive:
💰 Revenue: $50B ± $1B
📈 Gross Margin: ~86%
⚡ Non-GAAP EPS: $31 ± $1
Q3 revenue was $41.46B, with 84.6% GAAP gross margin.
🚨 The real catalyst: HBM + forward guidance
Micron says HBM4 is already shipping in high volume to a lead customer, while HBM4E targets 2027 production.
But MU is already up ~269% YTD.
So the market needs more than a beat.
It needs answers:
Can ~86% margins hold?
Can HBM/DRAM pricing stay strong?
Can demand absorb new capacity?
Will FY2027 guidance justify the valuation?
Samsung’s latest outlook adds another twist: HBM could reach nearly 30% of global DRAM wafer capacity next year.
🎯 My setup
🟢 Bullish: Strong Q4 + 86%+ margin + powerful FY2027 outlook
🔴 Bearish: Beat + weaker forward guidance = potential sell-the-news
My view: 🟢 Bullish fundamentals, ⚠️ cautious on chasing the pre-earnings move.
The Q4 beat isn’t the real story.
FY2027 guidance is.
Do you think the memory supercycle still has more room to run? 👇
#EarningsSeason #MU #Micron #AI #HBM
Not financial advice. DYOR & manage risk.