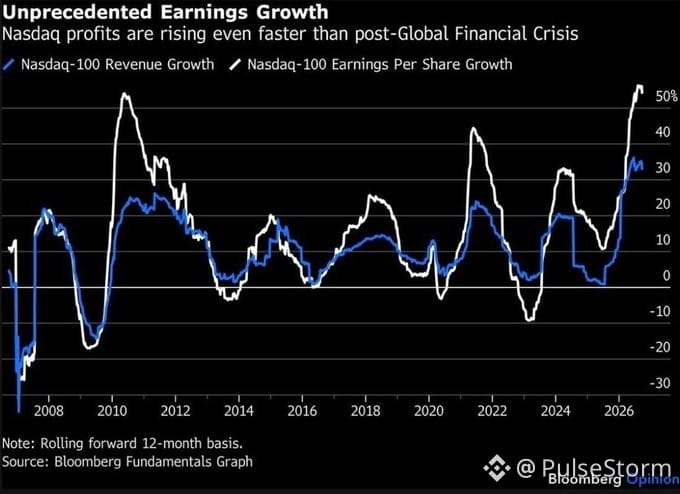
The bubble crowd has one classic test: multiples ripping while earnings sleep. That test is failing hard right now.
Nasdaq-100 Q1 2026 EPS growth: 45.6%. S&P 500: 28.8%. By Q2, Nasdaq's own data shows earnings growth near 80% annualized — strongest since 2010. Revenue growth: 18.6% vs 11.8% for the S&P.
Breadth tells the story. Over half of Nasdaq-100 names reported 20%+ earnings growth. More than four in five posted positive growth. Highest since Q4 2021.
Here's the key difference from 1999: back then, valuations ran miles ahead of earnings. Many companies had zero earnings.
Today, in sectors like semiconductors, P/E multiples are actually falling as earnings grow faster than price. Forward P/E: 25.2. Trailing: 35.2. That gap is what real earnings growth looks like in valuation terms.
The real counterargument: concentration in the top 10 holdings sits well above the dot-com peak. Household equity allocation hit a record 48%.
Fundamentals are moving, not just multiples. Whether earnings can keep compounding fast enough to justify 5% Treasury yields is the actual open question.
For now, this isn't 1999. It's a fundamentals-driven rally with real earnings velocity. The bubble test is failing — and that's bullish until it's not.