

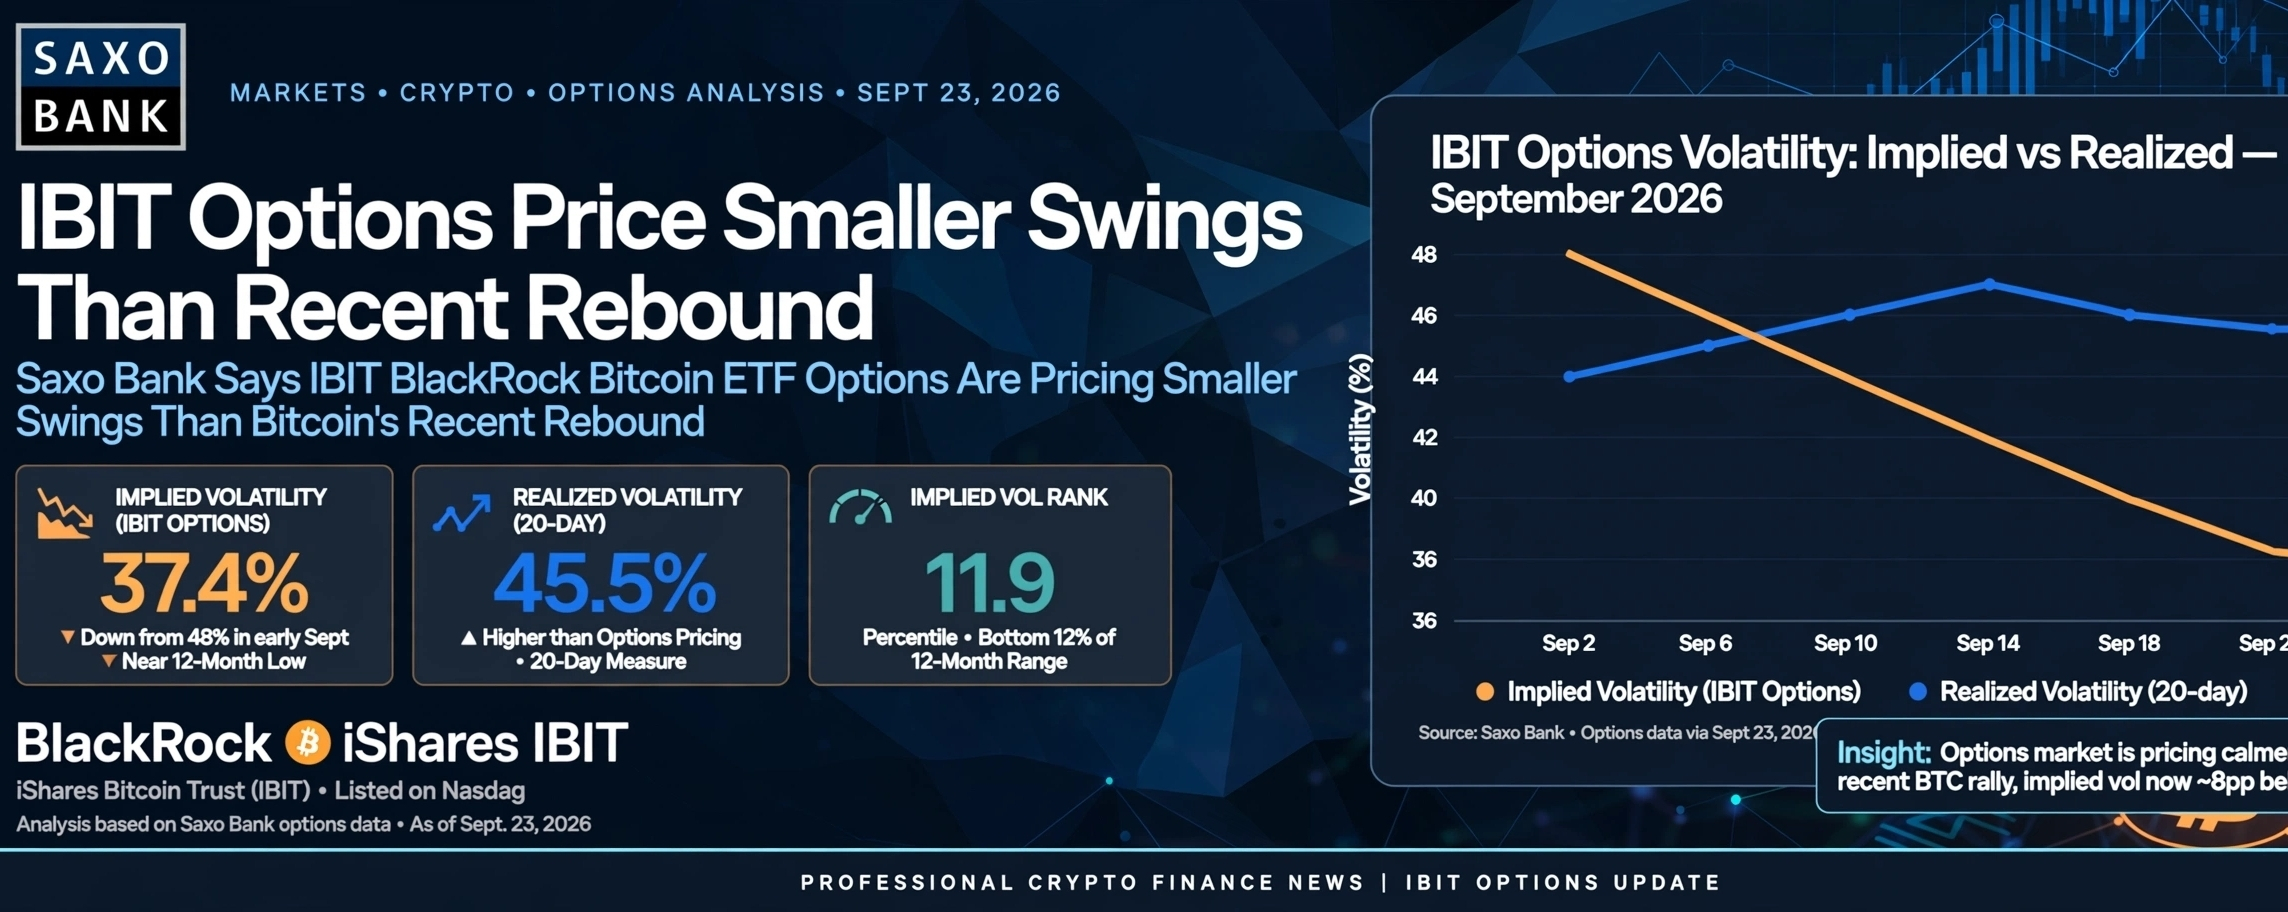
Options on BlackRock's Bitcoin ETF are pricing a calm-down.
According to Saxo Bank's analysis of data from Sept. 23, *iShares Bitcoin Trust (IBIT) options are implying smaller moves than Bitcoin actually made during its rebound.*
Saxo investment and options strategist Koen Hoorelbeke noted Thursday that IBIT's *implied volatility stood at 37.4%*, while *realized volatility over the last 20 trading sessions was 45.5%*. Implied vol is what the options market expects to happen. Realized is what just happened.
"In our view the options market appears to be pricing calmer conditions than the recent past produced," Hoorelbeke wrote.
Even more telling: IBIT's *implied volatility rank is just 11.9* — putting it near the bottom of its 12-month range. That means options are historically cheap right now in terms of expected movement.
This comes as Bitcoin itself has been choppy. BTC stalled around *$87,000 resistance on Sept. 21*, then pulled back. It was trading around *$84,751* on Thursday, up 1.6% on the day, still holding above the $80k breakout zone. Saxo sees next support between *$76k-$77k*.
The context: IBIT is up 11% in the last 5 days and just pulled in over *$1 billion in inflows* over the last four sessions, helping push the whole spot Bitcoin ETF complex back over $100B in assets. Call volume has dominated — IBIT printed a put/call ratio of 0.39 last week, with massive open interest at the $45 calls.
So traders are bullish on direction, but not betting on explosive volatility. That low IV rank at 37.4% is often when options desks start looking at long-vol strategies — LEAPS calls, call spreads — because you're paying less for the swing.
For now, the market message is: The rebound was wild. The next move might be slower.
#GrayscaleZcashETFHits$1BNetAssets #BitcoinSpotETFsNetInflow$191M #CFTCUpdatesGuidanceOnTokenizedAssets #BitgetSays$352MAffectedInHack #BinanceWillListHyperliquid(HYPE)