$AAVE and $ZEC made all the money out of sample, and the strategy still failed.
Backtest Lab #2: when an alt runs away from BTC, does it snap back?
The idea: strip BTC out of each alt (beta from the prior 90 days), add up the leftover move over 5 or 7 days, and when it is stretched 1.5 to 2.5 standard deviations, take the other side against a BTC hedge. Hold 1, 3 or 5 days. Fees and slippage 0.25% per trade.
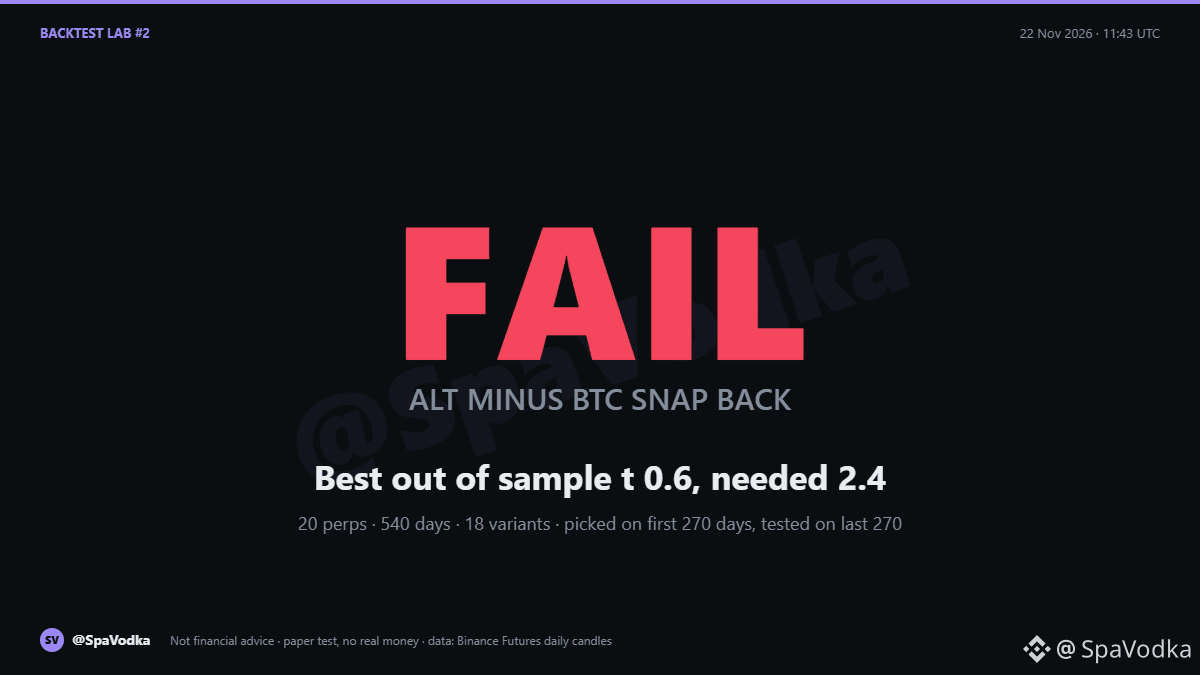
Data: 20 USDT perps, 540 days of daily candles, 18 variants. Settings picked on the first 270 days, tested on the last 270 that the model never saw. With 18 variants a real edge needs t of at least 2.4.
Result: all 18 variants lost money in the first half. The one picked on it (5 day stretch, 2.5 sigma, 5 day hold) made +1.7% a week out of sample (trade returns summed per week), t 0.6, 59% winning trades, 33% chance of a losing 30 day stretch. 9 of 18 variants ended positive out of sample, which is a coin flip. Almost all of it came from two pairs: AAVE and ZEC added 98 points, the other pairs lost 32 together.
Verdict: FAIL. No edge in the first half, and the second half is two lucky coins.
What I do with it: not trading it.
Next on the list: funding extremes, unlock windows, Friday to Monday. Which one should I test next?
Not financial advice.
#Backtesting #TradingStrategy #AAVE
Backtest Lab #2: when an alt runs away from BTC, does it snap back?
The idea: strip BTC out of each alt (beta from the prior 90 days), add up the leftover move over 5 or 7 days, and when it is stretched 1.5 to 2.5 standard deviations, take the other side against a BTC hedge. Hold 1, 3 or 5 days. Fees and slippage 0.25% per trade.
Data: 20 USDT perps, 540 days of daily candles, 18 variants. Settings picked on the first 270 days, tested on the last 270 that the model never saw. With 18 variants a real edge needs t of at least 2.4.
Result: all 18 variants lost money in the first half. The one picked on it (5 day stretch, 2.5 sigma, 5 day hold) made +1.7% a week out of sample (trade returns summed per week), t 0.6, 59% winning trades, 33% chance of a losing 30 day stretch. 9 of 18 variants ended positive out of sample, which is a coin flip. Almost all of it came from two pairs: AAVE and ZEC added 98 points, the other pairs lost 32 together.
Verdict: FAIL. No edge in the first half, and the second half is two lucky coins.
What I do with it: not trading it.
Next on the list: funding extremes, unlock windows, Friday to Monday. Which one should I test next?
Not financial advice.
#Backtesting #TradingStrategy #AAVE