

If you look only at November 21, you might think this was just a sudden crash.
But if we rewind 45 days, we’ll see that things weren’t so simple.
Starting from October 8, let’s take a look at what happened over these 45 days 👇
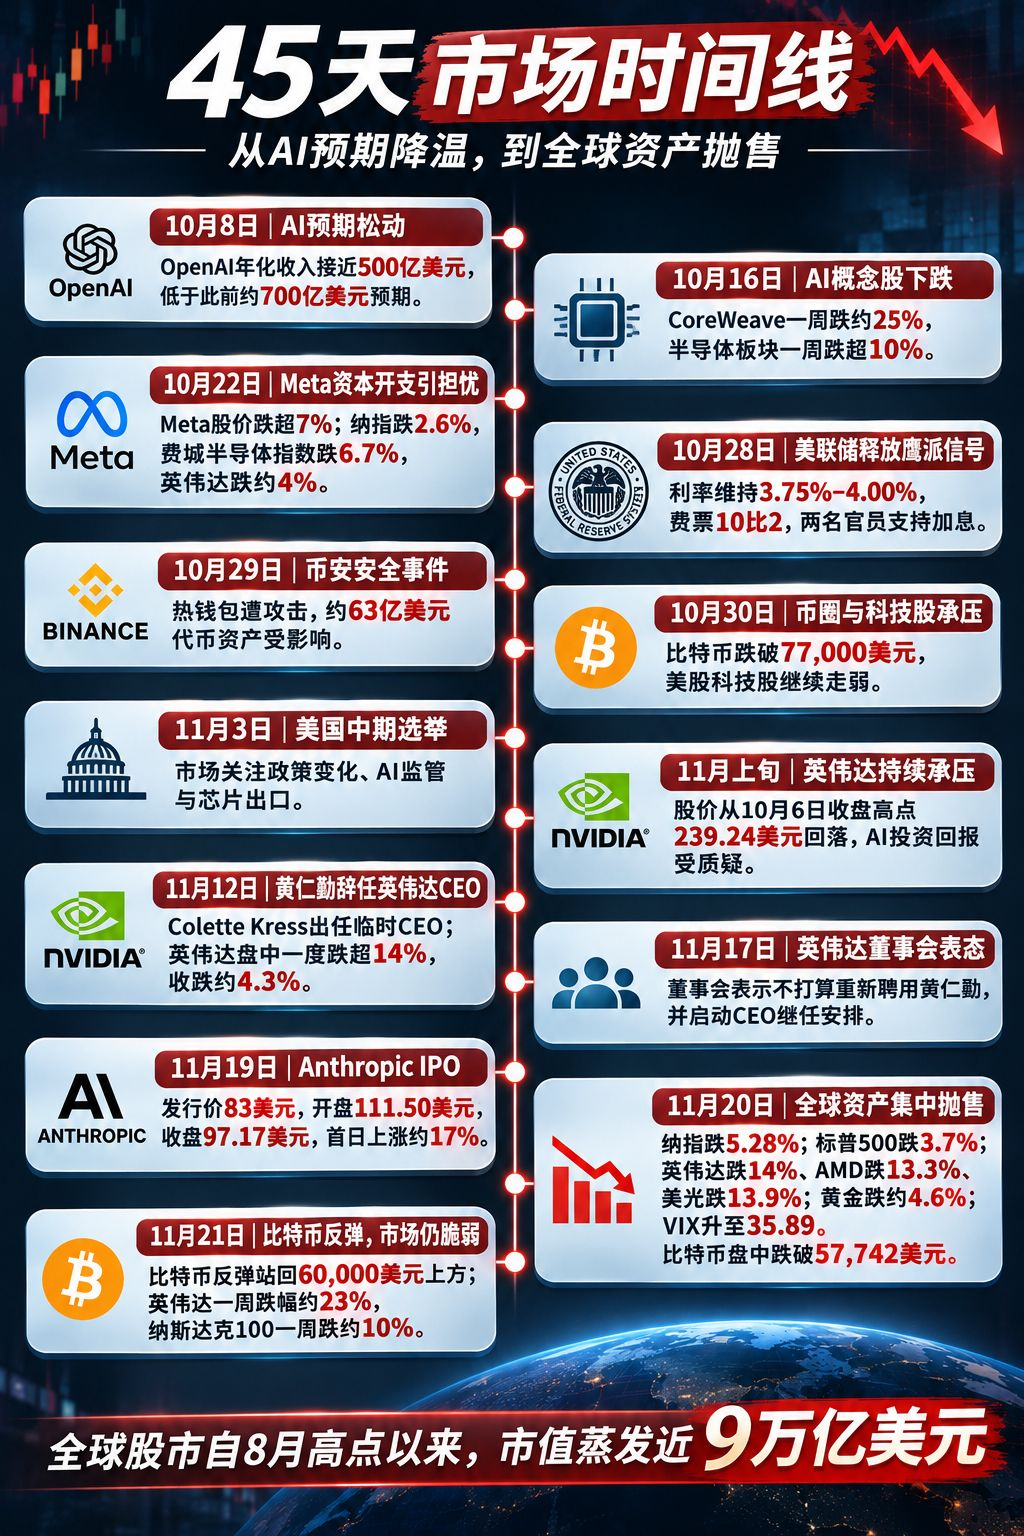
🔷 October 8 | AI expectations begin to soften
OpenAI’s annualized revenue in September was close to $50 billion, but the company had previously given investors expectations closer to $70 billion. The gap drew market attention.
Investors began to worry about whether AI companies’ actual revenue growth could keep up with the lofty expectations set earlier.
🔷 October 16 | AI-related stocks fall across the board
AI cloud computing and chip stocks came under selling pressure. CoreWeave fell about 25% in a week, while the semiconductor sector dropped more than 10%.
The market began to worry that investment in AI data centers was growing rapidly, but how much return would these investments actually generate?
🔷 October 22 | Meta sparks concerns over AI capital spending
Meta’s earnings beat expectations, but the company raised its planned AI capital spending and said it would issue new shares to raise funds.
Its share price fell more than 7% that day, the Nasdaq dropped 2.6%, the Philadelphia Semiconductor Index fell 6.7%, and Nvidia also declined about 4%.
🔷 October 28 | Fed sends a hawkish signal
The Fed held rates at 3.75%–4.00%, but the vote was split 10–2, with two officials supporting a rate hike.
Inflation remains elevated, and market expectations for future rate cuts began to waver, making investors more cautious about riskier assets.
🔷 October 29 | Major security incident at Binance
Binance’s hot wallet was attacked, affecting about $6.3 billion worth of token assets.
Binance said it would cover the related losses rather than make users pay. The incident nevertheless raised concerns about exchange security and risks in the crypto industry.
🔷 October 30 | Crypto and tech stocks come under pressure together
Binance released an update on the security incident, Bitcoin fell below $77,000, and U.S. tech stocks continued to weaken.
The AI sector was already in a correction, and the crypto security incident added to the pressure, further intensifying risk aversion.
🔷 November 3 | U.S. midterm elections
The U.S. midterm elections took place, and the market began to focus on how changes in congressional seats might affect the Trump administration’s policies, including AI regulation, chip exports, and technology industry policy.
🔷 Early November | Nvidia comes under mounting pressure
The investment case for AI continued to face scrutiny, and Nvidia kept falling from its October 6 closing high of $239.24.
The market is no longer focused solely on chip orders and earnings. It has also started to worry about financing across the AI supply chain, customer spending, and investment returns.
🔷 November 12 | Nvidia CEO Jensen Huang suddenly resigns
Nvidia announced that Jensen Huang had resigned as CEO and director, with CFO Colette Kress serving as interim CEO.
The news sent shockwaves through the market. Nvidia shares fell more than 14% at one point intraday, before closing down about 4.3%.
The sudden leadership change at this AI giant has also added new uncertainty to the entire AI sector.
🔷 November 17 | Nvidia board rejects Jensen Huang’s return
The board stated clearly that it would not rehire Huang and had launched an independent investigation into the matter.
Concerns about Nvidia’s future leadership, chip exports, and corporate governance continued to grow.
🔷 November 19 | Anthropic goes public
Anthropic went public at $83 per share, surged to $111.50 at the open, and ultimately closed at $97.17, still up about 17% on its first day.
Although the IPO performed reasonably well, the share price pulled back significantly from its intraday high. Combined with continued declines in AI stocks, this deepened the market’s divisions over AI companies’ valuations and profitability.
🔷 November 20 | Global assets face a wave of selling
News emerged that the U.S. SEC was investigating potential accounting issues at Nvidia. While an investigation does not mean the company did anything wrong, it further undermined market confidence.
U.S. stocks plunged that day, including:
- The Nasdaq fell 5.28%, turning negative for the year.
- The S&P 500 fell 3.7%, entering correction territory.
- Nvidia fell 14%, AMD fell 13.3%, and Micron fell 13.9%.
- Bitcoin slid toward $58,000
- Gold fell to around $3,515, down about 4.6% on the day.
- The VIX fear index rose to 35.89.
U.S. stocks, tech stocks, cryptocurrencies, and gold were all sold off at the same time, as market anxiety escalated noticeably.
🔷 November 21 | Bitcoin falls below $56,000, then rebounds
Bitcoin briefly fell to $55,251, its lowest level in two years, before rebounding more than 8% to around $60,000.
But the impact of the sell-off in U.S. stocks continued, and the market had not truly stabilized.
🔷 November 21 | Nvidia sheds nearly $900 billion in a week
Nvidia extended its losses, falling about 23% for the week and becoming the focus of the semiconductor sell-off. Meanwhile, the Nasdaq 100 fell about 10% for the week, as the AI trade continued to cool.
————————
Over these 45 days, three things were unfolding at the same time:
1️⃣ AI valuations begin to come under pressure
From OpenAI’s revenue outlook to Meta’s capital spending and the broad sell-off in chip stocks, the market began to question whether returns on AI investments could justify current valuations.
2️⃣ The macroeconomic environment becomes increasingly unfavorable
Inflation has not fully come down, and expectations of Fed rate hikes have started to rise again.
Assets that had relied on low interest rates and expectations of future growth began facing greater valuation pressure.
3️⃣ Market liquidity and confidence take a hit
The Binance security incident heightened unease in the crypto market, while declines in U.S. tech stocks further dampened risk appetite.
When investors begin to reduce their risk exposure all at once, selling is no longer confined to any one market.
So I’m more inclined to view this downturn as a repricing of risk.
Some have called this the second 312 sell-off, but I think the two episodes are still different.
The March 12, 2020 crash was mainly triggered by the pandemic, which sparked global panic and a sudden liquidity crunch. Even Bitcoin suffered a sharp, cascading collapse.
This time, concerns about high AI valuations, interest rate expectations, crypto-market risks, and market confidence piled up, eventually leading to a broad decline in global assets.
As for whether this will become a second 312 crash, it’s too early to say.
What matters next may not be which assets rebound first, but when investors are willing to come back!