Around midday Sunday, there are roughly four hours until this round of funding payments at 4 p.m. The broader markets haven’t reopened after the weekend, and fear is still stuck around 11. The market bounced during the day from near its two-year low of about 55.1k, touched the 60k area, then slipped back to around 59.1k. Some are taking one public-chain token turning green by about 7% on the day and another by about 4.2% as proof that the worst is over, the public-chain rebound is underway, and they can call it a day before Monday’s open. The numbers tell a different story: one climbed from an intraday low of about 2.546 to near its intraday high of about 2.932, while its long share fell from roughly 57% to 55%. It’s paying relatively expensive funding, and its contract count is down about 4.1%. It’s still well below its weekly high, having given back about 18%. The other is up about 4.2% in the same sector, but its long share is stuck around 52%, barely moving. It has a deeply negative funding rate, near the limit, and is collecting hefty subsidies; its contract count is up another 3.2%. It has given back about 23% and remains in a deeper weekly trough.
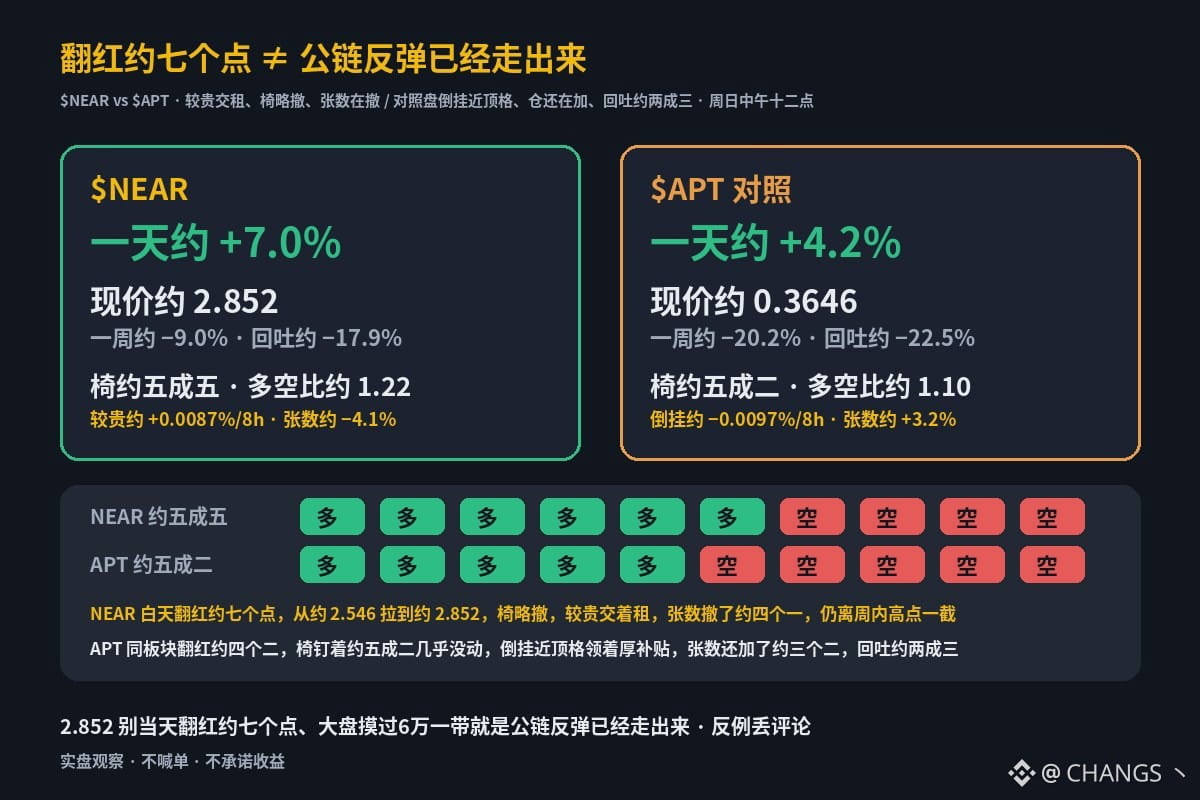
$NEAR : Up about +7.0% on the day and down about −9.0% on the week, with a current price around 2.852. The weekly high was about 3.475, so it has given back about −17.9%. The account long/short ratio is about 1.22 (roughly 55% long; about a day ago it was 1.31/57%, so longs are pulling back). The funding rate is about +0.0087%/8h, relatively expensive to pay. OI contract count is down about −4.1% over the past day (U-margined OI is about +3.8%, mostly because the price rose while the contract count fell). Price bounced from an intraday low of about 2.546 to near the intraday high of about 2.932; it’s now around 2.852, still well below the weekly high. Don’t take 2.852, a roughly 7% daily gain, and the market touching the 60k area as proof that the public-chain rebound is underway. And don’t take a slight pullback in longs, relatively expensive funding still being paid, and the idea that the worst is over as a reason to call it a day before Monday’s open.
Meanwhile, $APT is up about +4.2% on the day and down about −20.2% on the week, with a current price around 0.3646. Its weekly high was about 0.4704, so it has given back about −22.5%. Longs are about 52% (long/short ratio about 1.10; about a day ago it was 1.07/52%, so the long share has barely moved). Its funding rate is deeply negative, about −0.0097%/8h, near the limit, and it’s paying out hefty subsidies. OI contract count is up about +3.2% over the past day (U-margined OI is about +8.8%—genuine position building). Price bounced from an intraday low of about 0.3351 to near the intraday high of about 0.3789; it’s now around 0.3646, still in a weekly trough. Longs are stuck around 52%, barely moving; the deeply negative funding rate is near the limit and paying out hefty subsidies, and positions are still being added.
One is up about 7% on the day, rising from around 2.546 to 2.852, but has given back about 18%. Its long share fell from around 57% to 55%, it’s paying relatively expensive funding, and its contract count is down about 4.1%; it’s still well below its weekly high. The other is up about 4.2% in the same sector but has given back about 23%. Its long share is stuck around 52%, barely moving; its deeply negative funding rate is near the limit and paying out hefty subsidies, and its contract count is up another 3.2%. It remains in a deeper weekly trough. Is this a roughly 7% daily gain and the market touching the 60k area, meaning the public-chain rebound is underway and the worst is over—or is it just one token still in a weekly trough, with longs only pulling back a little, relatively expensive funding still being paid, and contract count falling, compared with another that has given back about 23%, has deeply negative funding near the limit paying out hefty subsidies, and is still seeing positions added? Post a counterexample in the comments.
$NEAR : Up about +7.0% on the day and down about −9.0% on the week, with a current price around 2.852. The weekly high was about 3.475, so it has given back about −17.9%. The account long/short ratio is about 1.22 (roughly 55% long; about a day ago it was 1.31/57%, so longs are pulling back). The funding rate is about +0.0087%/8h, relatively expensive to pay. OI contract count is down about −4.1% over the past day (U-margined OI is about +3.8%, mostly because the price rose while the contract count fell). Price bounced from an intraday low of about 2.546 to near the intraday high of about 2.932; it’s now around 2.852, still well below the weekly high. Don’t take 2.852, a roughly 7% daily gain, and the market touching the 60k area as proof that the public-chain rebound is underway. And don’t take a slight pullback in longs, relatively expensive funding still being paid, and the idea that the worst is over as a reason to call it a day before Monday’s open.
Meanwhile, $APT is up about +4.2% on the day and down about −20.2% on the week, with a current price around 0.3646. Its weekly high was about 0.4704, so it has given back about −22.5%. Longs are about 52% (long/short ratio about 1.10; about a day ago it was 1.07/52%, so the long share has barely moved). Its funding rate is deeply negative, about −0.0097%/8h, near the limit, and it’s paying out hefty subsidies. OI contract count is up about +3.2% over the past day (U-margined OI is about +8.8%—genuine position building). Price bounced from an intraday low of about 0.3351 to near the intraday high of about 0.3789; it’s now around 0.3646, still in a weekly trough. Longs are stuck around 52%, barely moving; the deeply negative funding rate is near the limit and paying out hefty subsidies, and positions are still being added.
One is up about 7% on the day, rising from around 2.546 to 2.852, but has given back about 18%. Its long share fell from around 57% to 55%, it’s paying relatively expensive funding, and its contract count is down about 4.1%; it’s still well below its weekly high. The other is up about 4.2% in the same sector but has given back about 23%. Its long share is stuck around 52%, barely moving; its deeply negative funding rate is near the limit and paying out hefty subsidies, and its contract count is up another 3.2%. It remains in a deeper weekly trough. Is this a roughly 7% daily gain and the market touching the 60k area, meaning the public-chain rebound is underway and the worst is over—or is it just one token still in a weekly trough, with longs only pulling back a little, relatively expensive funding still being paid, and contract count falling, compared with another that has given back about 23%, has deeply negative funding near the limit paying out hefty subsidies, and is still seeing positions added? Post a counterexample in the comments.