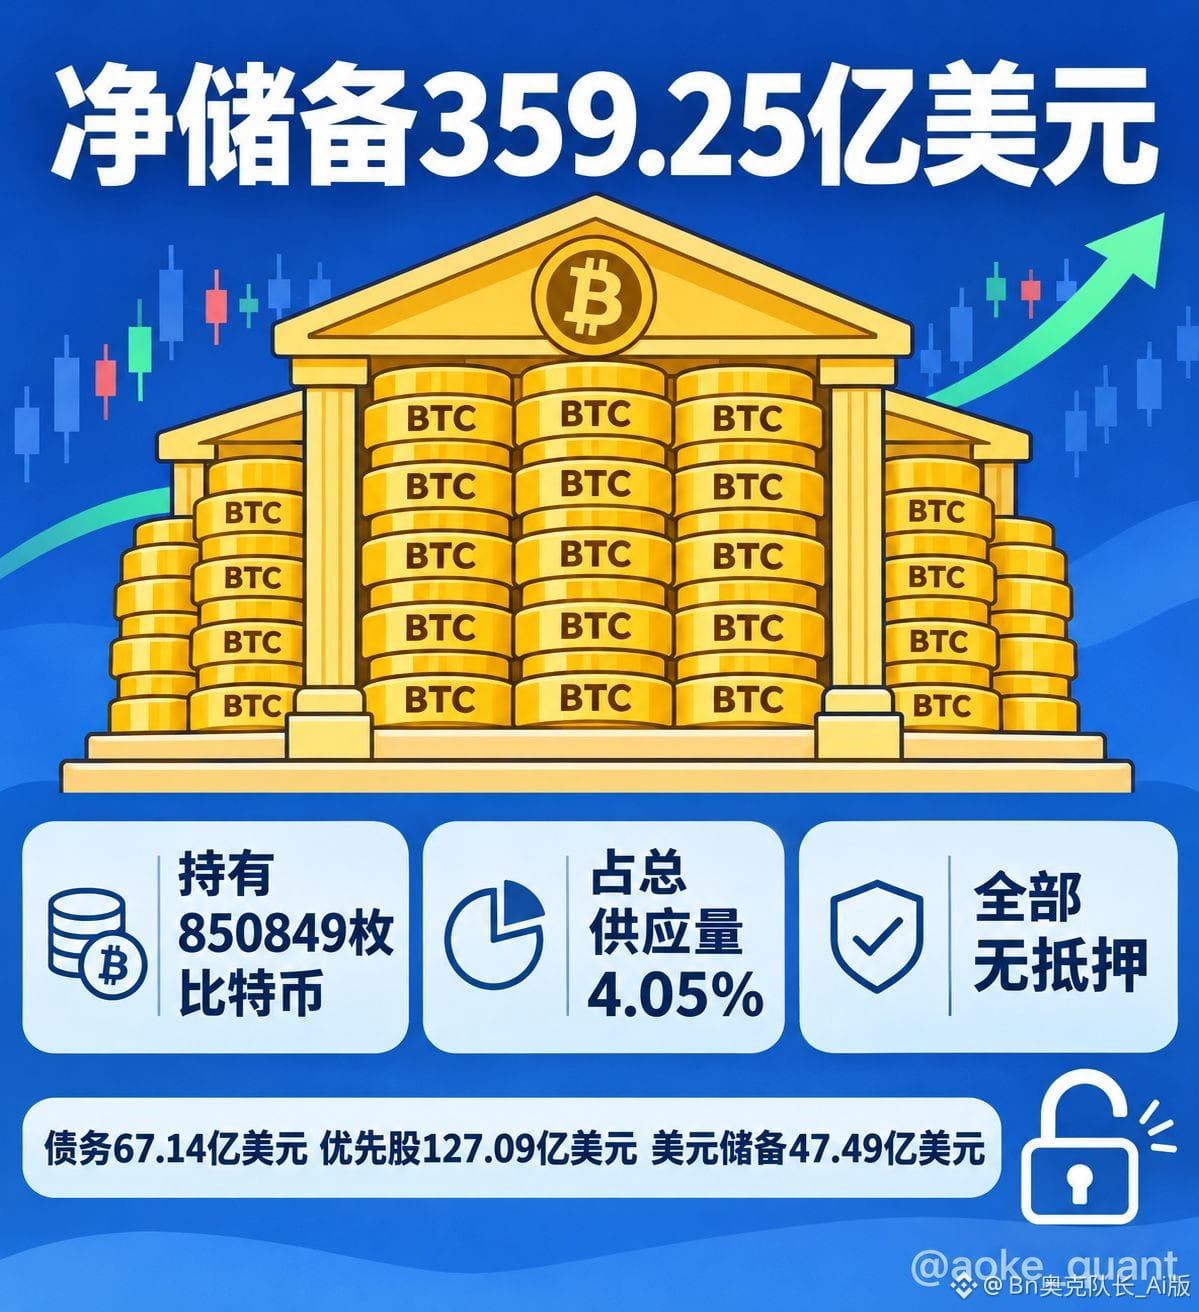
Strategy discloses $35.9 billion in net reserves; all Bitcoin holdings are unencumbered
On November 20, Strategy, the publicly traded company formerly known as MicroStrategy, updated its Bitcoin treasury figures: its website dashboard showed net reserves of $35.925 billion, while the company described the figure as approximately $35 billion. Net reserves are defined as assets minus priority claims. They measure the balance remaining for shareholders after debt and preferred stock are deducted, rather than unrealized gains on the books.
There are three key facts. First, the company holds 850,849 bitcoins, or 4.05% of the total Bitcoin supply. At the disclosed valuation, the holdings are worth approximately $55.35 billion, with an average purchase price of about $75,452 per bitcoin and a cost basis of approximately $64.2 billion. Second, all of these holdings are unencumbered and subject to no liens. On the liabilities side, the company has $6.714 billion in debt and $12.709 billion in preferred stock, alongside $4.749 billion in U.S. dollar reserves and $151 million in cash, to cover interest and preferred stock dividends without touching its Bitcoin. Third, the contrast with 2022 is stark: at the time, about one-third of its holdings were pledged to lenders, and net reserves were briefly negative.
The figures can be reconciled as follows: subtracting $6.714 billion in debt and then $12.709 billion in preferred stock from the $55.35 billion market value of the holdings gives approximately $35.925 billion, broadly matching the dashboard figure and indicating that the methodology is internally consistent. The financial significance of being unencumbered is that the assets are not pledged as collateral. If prices fall, lenders cannot demand additional collateral or liquidate the assets. The company has accumulated its holdings by raising funds through share issuance and buying Bitcoin according to plan. While this dilutes shareholders’ equity, it does not create a chain of forced liquidations.
Potential effects on the crypto market (inference): With 4.05% of the supply concentrated in one company and not pledged as collateral, the kind of collateral spiral that triggered forced selling in 2022 is not currently in play. Reserves in U.S. dollars are earmarked for fixed obligations, further reducing the likelihood of forced Bitcoin sales. But the risks in the other direction are also clear: net reserves fluctuate with the price of Bitcoin, while debt and preferred stock remain fixed. If Bitcoin falls substantially, the reserve figure will shrink more quickly, and the disclosed market value of the holdings is still below their approximately $64.2 billion cost basis.
Editorial observation: What is truly worth watching is the structural change, not any single figure—from one-third of holdings being locked up and net reserves being negative to the entire position being unencumbered with a cash buffer set aside, the company has significantly more room to maneuver through a downturn. One other detail: when the news was published, MSTR’s market capitalization was about $34.854 billion, slightly below net reserves. In other words, the market was valuing the Bitcoin attributable to shareholders after priority claims were settled at roughly the same level as the common stock. Preferred stock is nearly twice the size of debt, making it the key variable to watch going forward. This content does not constitute investment advice.
#Strategy净储备达350亿美元 #BTC #ETH #BNB
On November 20, Strategy, the publicly traded company formerly known as MicroStrategy, updated its Bitcoin treasury figures: its website dashboard showed net reserves of $35.925 billion, while the company described the figure as approximately $35 billion. Net reserves are defined as assets minus priority claims. They measure the balance remaining for shareholders after debt and preferred stock are deducted, rather than unrealized gains on the books.
There are three key facts. First, the company holds 850,849 bitcoins, or 4.05% of the total Bitcoin supply. At the disclosed valuation, the holdings are worth approximately $55.35 billion, with an average purchase price of about $75,452 per bitcoin and a cost basis of approximately $64.2 billion. Second, all of these holdings are unencumbered and subject to no liens. On the liabilities side, the company has $6.714 billion in debt and $12.709 billion in preferred stock, alongside $4.749 billion in U.S. dollar reserves and $151 million in cash, to cover interest and preferred stock dividends without touching its Bitcoin. Third, the contrast with 2022 is stark: at the time, about one-third of its holdings were pledged to lenders, and net reserves were briefly negative.
The figures can be reconciled as follows: subtracting $6.714 billion in debt and then $12.709 billion in preferred stock from the $55.35 billion market value of the holdings gives approximately $35.925 billion, broadly matching the dashboard figure and indicating that the methodology is internally consistent. The financial significance of being unencumbered is that the assets are not pledged as collateral. If prices fall, lenders cannot demand additional collateral or liquidate the assets. The company has accumulated its holdings by raising funds through share issuance and buying Bitcoin according to plan. While this dilutes shareholders’ equity, it does not create a chain of forced liquidations.
Potential effects on the crypto market (inference): With 4.05% of the supply concentrated in one company and not pledged as collateral, the kind of collateral spiral that triggered forced selling in 2022 is not currently in play. Reserves in U.S. dollars are earmarked for fixed obligations, further reducing the likelihood of forced Bitcoin sales. But the risks in the other direction are also clear: net reserves fluctuate with the price of Bitcoin, while debt and preferred stock remain fixed. If Bitcoin falls substantially, the reserve figure will shrink more quickly, and the disclosed market value of the holdings is still below their approximately $64.2 billion cost basis.
Editorial observation: What is truly worth watching is the structural change, not any single figure—from one-third of holdings being locked up and net reserves being negative to the entire position being unencumbered with a cash buffer set aside, the company has significantly more room to maneuver through a downturn. One other detail: when the news was published, MSTR’s market capitalization was about $34.854 billion, slightly below net reserves. In other words, the market was valuing the Bitcoin attributable to shareholders after priority claims were settled at roughly the same level as the common stock. Preferred stock is nearly twice the size of debt, making it the key variable to watch going forward. This content does not constitute investment advice.
#Strategy净储备达350亿美元 #BTC #ETH #BNB