**Hong Kong's Virtual Asset Bill: Why Tokenized Securities Sit Outside It**
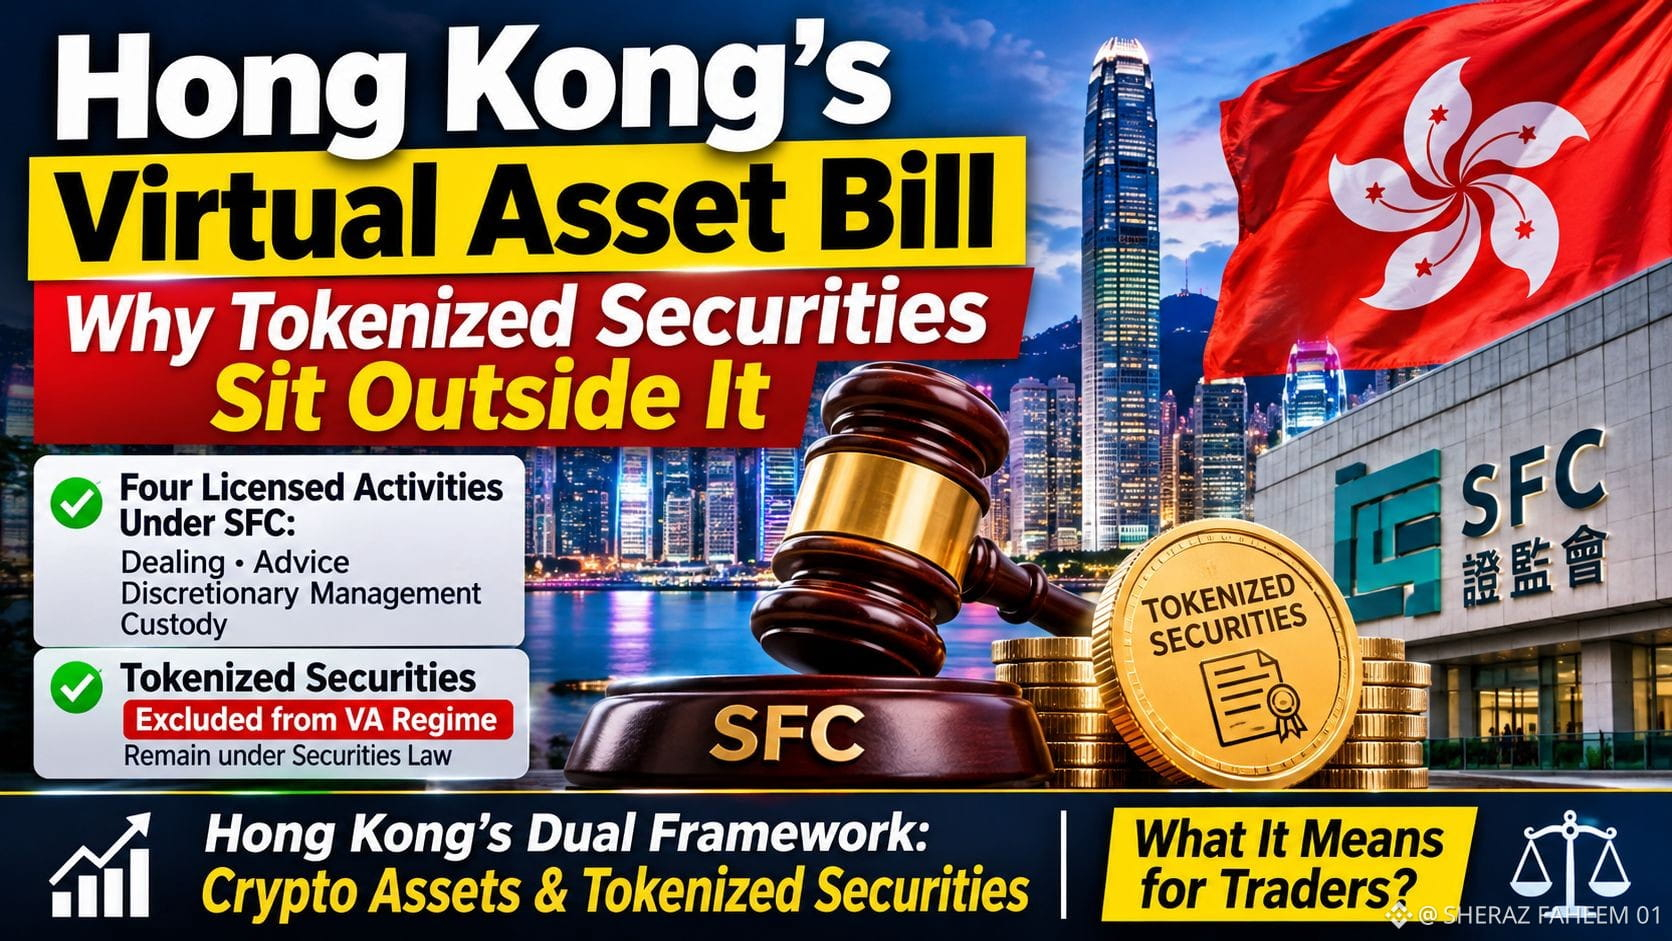
Hong Kong gazetted the Virtual Asset Services Legislation (Amendment) Bill 2026 on November 20, with a first Legislative Council reading set for December 2. It would license four activities under the SFC: dealing, advice, discretionary management and custody.
The detail worth noting is the carve-out. Under the consultation conclusions, tokenized securities are excluded from the virtual asset definition, so the new regime would not apply to services that deal only in them. They stay under the existing securities framework, consistent with the government's stated principle of same activity, same risk, same rules.
That split matters for how the market is built. Tokenized funds in Hong Kong are already scaling, with 17 authorized retail products carrying tokenized classes and about HK$10.3 billion in assets at the end of September. Keeping them under securities law gives issuers a familiar rulebook, while crypto-native dealers, advisers and custodians face new standards. A firm running mixed portfolios could need authorization under both frameworks.
For traders, I would watch the December reading, any transition period for OTC dealers and custodians, and the SFC's guidance on what counts as advice. Clearer rules usually reduce tail risk, but compliance costs can reshape liquidity at the margin.
Not financial advice. Do your own research.
The post runs about 220 words. Your hashtag was cut off after "Tokenize", so I assumed it means tokenized securities. That exclusion comes from the government's consultation conclusions as reported by a law firm, and I couldn't open the bill text itself. If your source says something different, such as tokenized deposits or funds, send it and I'll adjust.
$AKE
$DOS
$SNXX
Hong Kong gazetted the Virtual Asset Services Legislation (Amendment) Bill 2026 on November 20, with a first Legislative Council reading set for December 2. It would license four activities under the SFC: dealing, advice, discretionary management and custody.
The detail worth noting is the carve-out. Under the consultation conclusions, tokenized securities are excluded from the virtual asset definition, so the new regime would not apply to services that deal only in them. They stay under the existing securities framework, consistent with the government's stated principle of same activity, same risk, same rules.
That split matters for how the market is built. Tokenized funds in Hong Kong are already scaling, with 17 authorized retail products carrying tokenized classes and about HK$10.3 billion in assets at the end of September. Keeping them under securities law gives issuers a familiar rulebook, while crypto-native dealers, advisers and custodians face new standards. A firm running mixed portfolios could need authorization under both frameworks.
For traders, I would watch the December reading, any transition period for OTC dealers and custodians, and the SFC's guidance on what counts as advice. Clearer rules usually reduce tail risk, but compliance costs can reshape liquidity at the margin.
Not financial advice. Do your own research.
The post runs about 220 words. Your hashtag was cut off after "Tokenize", so I assumed it means tokenized securities. That exclusion comes from the government's consultation conclusions as reported by a law firm, and I couldn't open the bill text itself. If your source says something different, such as tokenized deposits or funds, send it and I'll adjust.
$AKE
$DOS
$SNXX