
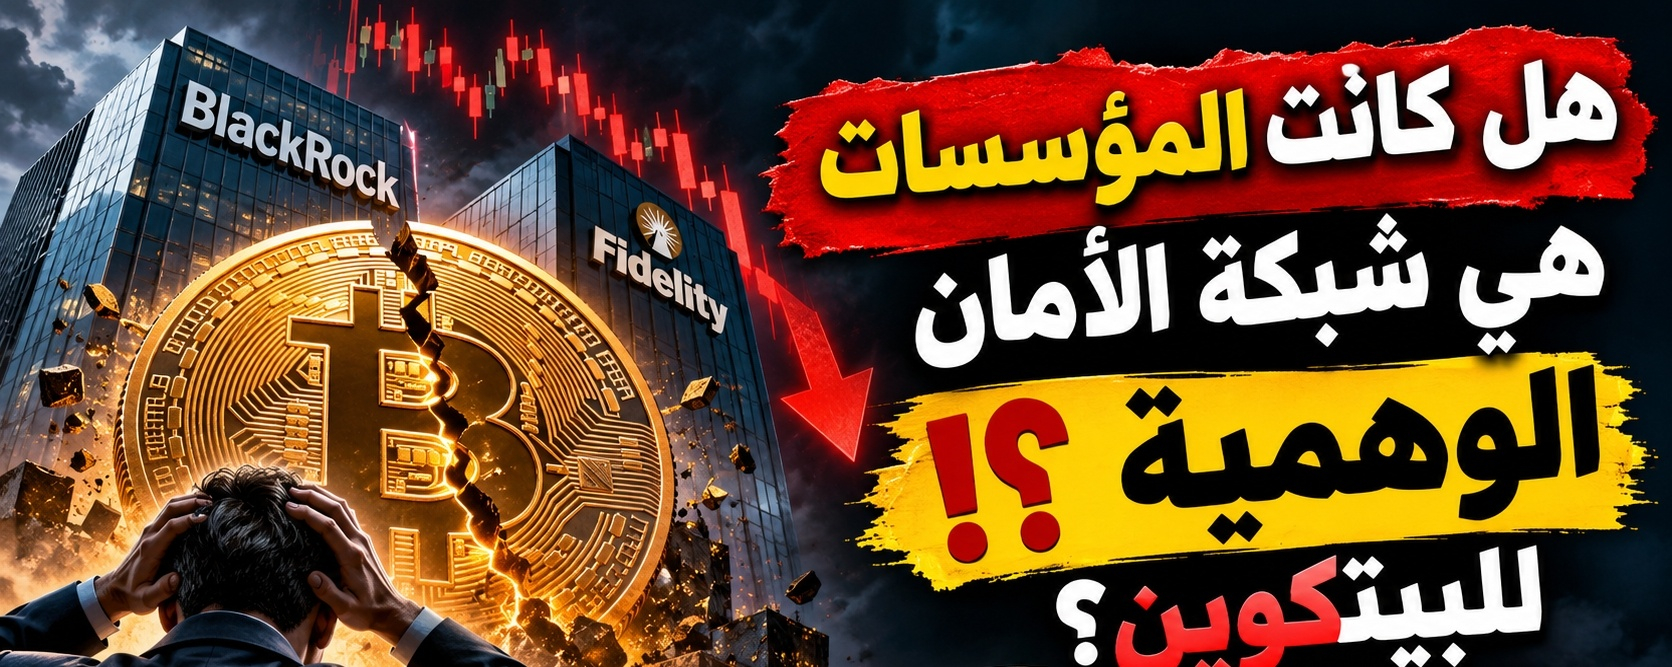
$3.47 billion flowed out of Bitcoin ETFs in November. And here’s a question that institutional adoption advocates may not like: who will buy when institutions stop buying?
Today, I’m going to share an opinion that may unsettle many investors who have built their bullish view of Bitcoin on the entry of major financial institutions.
The market may have overestimated the strength of ETFs as a safety net for Bitcoin’s price.
For years, one of the strongest bullish arguments was that BlackRock, Fidelity, and Morgan Stanley entering the Bitcoin market would change the game.
Bitcoin is no longer just an asset bought by individuals and speculative traders; it’s now available through regulated financial products that traditional investors can use.
But there’s a question that hasn’t received enough attention:
What happens when this same institutional demand turns into outflows?
Have we just discovered that institutions aren’t permanent Bitcoin investors, but capital that can enter and exit according to market conditions, just like with any other asset?
Let’s look at the numbers.
1. One number that should give us pause: $3.47 billion
According to The Block’s November 20 report, U.S. Bitcoin Spot ETFs recorded net outflows of about $3.47 billion in November, through the close of the November 19 session.
But the most striking detail is this:
Only two sessions recorded positive flows across 14 trading sessions.
On November 19 alone, about $582.2 million flowed out.
BlackRock’s IBIT fund recorded daily outflows of $541.1 million, its largest daily outflow since launch.
The Morgan Stanley MSBT fund recorded inflows of about $49.6 million in the same session.
Source: The Block, based on SoSoValue data.
And here lies the irony.
BlackRock, which has become a symbol of institutional adoption of Bitcoin, saw its fund record its largest daily outflow since launch.
Does this mean institutions have abandoned Bitcoin?
No.
But does the presence of institutions mean there will always be a buyer at every dip?
Absolutely not.
And that is the difference I think many traders have overlooked.
2. The problem isn’t that institutions are selling... it’s that the market assumed they wouldn’t
A belief has spread in recent times:
Whenever Bitcoin falls, institutions will step in to buy the dip.
This idea helped build strong investor confidence, but it contains a fundamental flaw.
Institutions don’t buy Bitcoin out of loyalty to the crypto community.
They manage portfolios, balance risk, and deal with liquidity and return expectations.
When conditions become unfavorable for risk-taking, their decisions can change.
That doesn’t make institutions enemies of Bitcoin; it makes them investors with their own interests.
More controversially, Wall Street’s entry into Bitcoin may make capital flows more closely tied to risk cycles in traditional markets.
In other words:
Has institutional adoption made Bitcoin more legitimate, but also more sensitive to the decisions of traditional investors?
That question deserves serious discussion.
3. There’s a second problem: Has the spot buyer disappeared?
Look at how trading volume has evolved.
According to The Block data, monthly spot trading volume on centralized crypto exchanges fell from about $1.69 trillion in September to $1.02 trillion in October.
That’s a decline of nearly 40%.
A drop in trading volume alone doesn’t mean that money has left the market entirely, but it does reveal a significant decline in spot activity.
And here I see a bigger problem than just a price correction.
The market can withstand heavy selling when there is enough demand to absorb it.
But what happens when selling coincides with a decline in spot activity, outflows from funds, and weaker risk appetite?
Liquidity may become less capable of absorbing shocks.
This is the scenario that worries me more than simply breaking below $60,000.
4. Have we seen the beginning of long-position capitulation?
Data from CoinDesk and CoinGlass published on November 20 revealed a grim picture in the derivatives market.
Over 24 hours:
Crypto liquidations exceeded $718 million.
Long positions accounted for about 86.2% of liquidations.
Futures trading volume rose 31.7%.
Open interest fell 2.5% to about $109.9 billion.
These aren’t just red candles.
It’s a deleveraging process in the market.
Positions betting on rising prices were forcibly closed, and some traders lost their positions without choosing when to exit.
But here’s another possibility we shouldn’t ignore:
These liquidations may be exactly what cleanses the market of excessive leverage and paves the way for a strong rebound.
That makes the situation more complicated.
A decline doesn’t automatically mean more declines are coming, just as long liquidations don’t mean a bottom has formed.
Source: CoinDesk, CoinGlass data published on November 20, 2026.
5. The scenario the bulls may not want to hear
Let’s assume Bitcoin fails to sustainably reclaim the $60,000 level.
What could happen?
The bearish scenario I’m watching consists of four stages:
Stage one: Continued weakness in ETF inflows, with temporary outflows turning into a sustained trend.
Stage two: Failed attempts to reclaim broken price levels, turning rebounds into exit opportunities for late buyers.
Stage three: A new wave of liquidations, particularly if traders rebuild leveraged long positions before the market regains its balance.
Stage four: A decline in spot liquidity to a level where large sell orders have a greater impact on price.
In this scenario, the question won’t be whether Bitcoin can fall a few thousand dollars.
It will be:
Where will the real demand emerge that can stop the selling wave?
I’m not setting a firm price target, because identifying a future bottom without confirmation from flows and liquidity would be mere guesswork.
But losing $60,000 without reclaiming it, alongside continued ETF outflows, would make a test of lower levels a possibility that can’t be ignored.
6. But before the bears declare victory... there’s a fact that could turn the analysis on its head
There’s an important piece of information that keeps me from adopting the narrative that institutions have abandoned Bitcoin.
Even after these outflows, SoSoValue data cited by The Block showed that U.S. Bitcoin funds held about $76.6 billion in assets.
Cumulative net inflows since launch also reached about $53.5 billion.
In other words, November’s outflows don’t erase the fact that these products have attracted substantial inflows since launch.
In fact, the Morgan Stanley fund recorded a positive inflow on November 19, while Hong Kong spot Bitcoin funds saw modest inflows during the month.
So perhaps this is a shift in allocation and risk appetite, not a full-scale institutional retreat.
That’s why I consider the current phase a real test for the market, not a declaration of Bitcoin’s demise.
7. The question I want to leave with the Bitcoin community
Today we have two conflicting narratives:
The first narrative:
Bitcoin is going through a deleveraging phase and a sharp correction. ETFs still hold substantial assets, and current outflows don’t erase long-term institutional adoption.
Therefore, what’s happening may be an opportunity to rebuild the uptrend.
The second narrative:
The market built much of its confidence on the assumption that institutions would continue pouring money in at every dip.
But current data shows that this demand isn’t guaranteed, and Bitcoin could face a real demand crisis if spot activity declines and redemptions continue.
Therefore, a break below $60,000 could mark the start of a tougher test than most buyers expect.
I want an honest answer, not just a bullish or bearish vote:
Was the Bitcoin community wrong to view BlackRock’s and other financial institutions’ entry as a guarantee of a price floor?
Choose a position and support it with an argument:
A — Institutions haven’t abandoned Bitcoin. This is just a deleveraging event, and the bottom may be near.
B — The myth of the permanent institutional buyer is over. Bitcoin is now more closely tied to traditional capital fluctuations, and we may see a deeper downturn.
C — Both interpretations are incomplete. The real problem isn’t institutions, but declining spot demand and liquidity across the entire market.
I think the third option deserves more attention than it’s currently getting.
But I want to hear the case from those who disagree, especially anyone who believes ETF outflows pose no threat to Bitcoin’s bullish structure.
Defend your position with numbers, not emotional predictions.
#BTC走势分析 #cryptouniverseofficial #BTC突破7万大关
