Late Friday night, the midnight rent-settlement has arrived. The U.S. cash market has been open for about an hour and a half, the broader market has plunged below 60,000, and BlackRock’s Bitcoin spot ETF just reported its latest daily net outflow at about $541 million, a record for the fund. Some are taking the public chain’s roughly 7% daytime drop, its price near the intraday low, and the approaching settlement point as signs this round has already been cleared out—that once this round’s rent is paid, they can take a break. But the ledger tells a different story: on one side, the chairs are pinned at about 62% and have barely moved, while the inverted funding rate is paying an unusually hefty subsidy, far beyond the typical cap; the contract count is also slightly up, and the price has slid from the intraday high and remains in the weekly hole. On the other side, the L2 chairs are already bearish at about 47%, and are also receiving an even heftier subsidy from inverted funding; the weekly retracement is about 27%, and the price is near the intraday low.
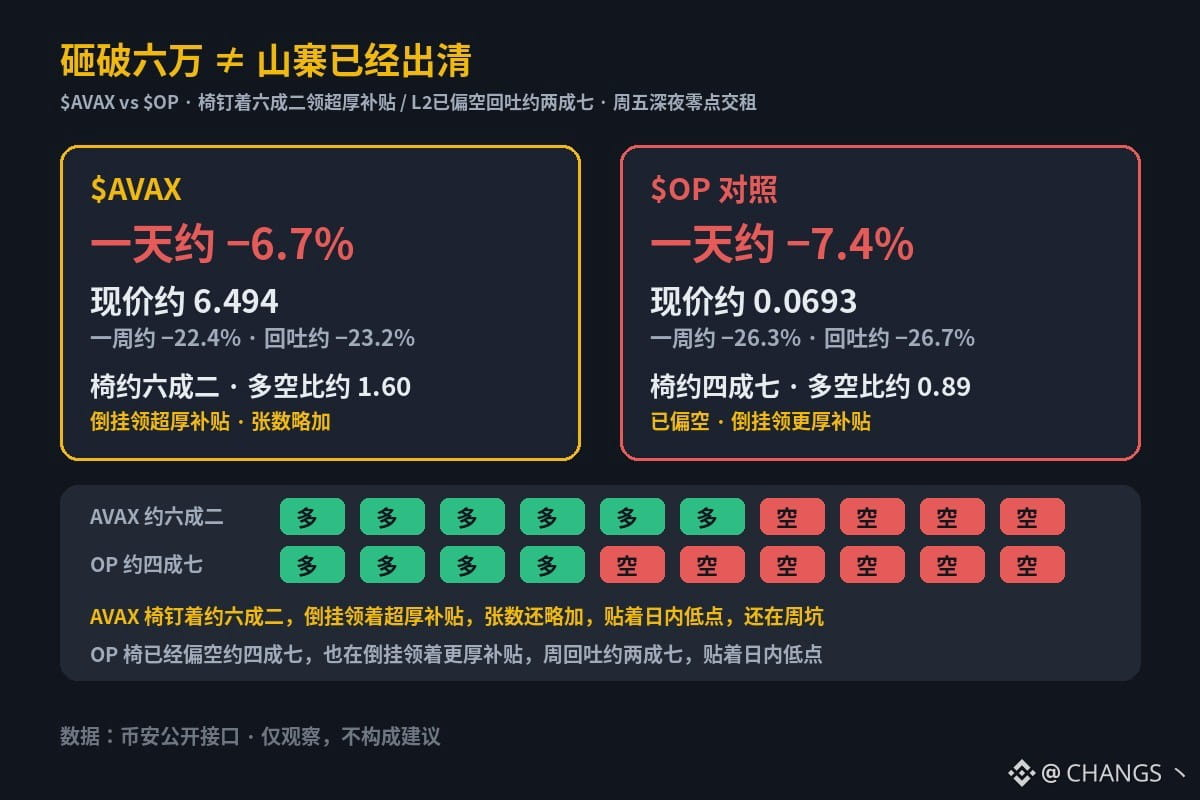
$AVAX: down about −6.7% on the day and −22.4% on the week, with the current price around 6.494. The weekly high was about 8.452, for a retracement of about −23.2%. The account long/short ratio is about 1.60 (about 62% long; about 1.62/62% long roughly a day ago, so the chairs have barely moved). Funding is inverted at about −0.0179%/8h, paying an unusually hefty subsidy far beyond the typical cap. Open interest contract count is up about +2.8% over the past day (about +0.2% in USD-margined terms; the contract count is rising). The price has slid from the intraday high of about 7.093 and is near the intraday low of about 6.428, still in the weekly hole. The chairs are pinned at about 62%, inverted funding is paying an unusually hefty subsidy, and the contract count is still slightly up—don’t take 6.494, a roughly 6.7% daytime drop, a plunge below 60,000, and the midnight settlement as proof this round has already been cleared out. And don’t take chairs pinned at about 62% while still collecting an unusually hefty subsidy as a sign that once this round’s rent is paid, you can take a break.
In the same session, $OP was down about −7.4% on the day and −26.3% on the week, with the current price around 0.0693. The weekly high was about 0.09454, for a retracement of about −26.7%. The chairs are at about 47% (long/short ratio about 0.89; about 0.91/48% roughly a day ago, so barely changed). Funding is inverted at about −0.0203%/8h, paying an unusually hefty subsidy far beyond the typical cap. Open interest contract count is down about −1.5% over the past day (about −4.0% in USD-margined terms, mostly due to the price drop, with a slight reduction in contract count). The price has slid from the intraday high of about 0.0764 and is near the intraday low of about 0.06837. It dropped about 7.4% during the day, the chairs are already leaning bearish, inverted funding is paying an even heftier subsidy, the retracement is about 27%, and the price is still near the intraday low.
On one side, the chairs are pinned at about 62%, inverted funding is paying an unusually hefty subsidy, the contract count is still slightly up, and the price remains in the weekly hole. On the other, the L2 chairs are already bearish at about 47%, also collecting an even heftier subsidy from inverted funding; the weekly retracement is about 27%, and the price is near the intraday low. Does a plunge below 60,000, record outflows, and the midnight rent settlement mean this round has already been cleared out and that once this round’s rent is paid, you can take a break—or are the chairs simply still pinned at about 62%, with both sides collecting unusually hefty subsidies and the price not yet out of the hole? Post counterexamples in the comments.
$AVAX: down about −6.7% on the day and −22.4% on the week, with the current price around 6.494. The weekly high was about 8.452, for a retracement of about −23.2%. The account long/short ratio is about 1.60 (about 62% long; about 1.62/62% long roughly a day ago, so the chairs have barely moved). Funding is inverted at about −0.0179%/8h, paying an unusually hefty subsidy far beyond the typical cap. Open interest contract count is up about +2.8% over the past day (about +0.2% in USD-margined terms; the contract count is rising). The price has slid from the intraday high of about 7.093 and is near the intraday low of about 6.428, still in the weekly hole. The chairs are pinned at about 62%, inverted funding is paying an unusually hefty subsidy, and the contract count is still slightly up—don’t take 6.494, a roughly 6.7% daytime drop, a plunge below 60,000, and the midnight settlement as proof this round has already been cleared out. And don’t take chairs pinned at about 62% while still collecting an unusually hefty subsidy as a sign that once this round’s rent is paid, you can take a break.
In the same session, $OP was down about −7.4% on the day and −26.3% on the week, with the current price around 0.0693. The weekly high was about 0.09454, for a retracement of about −26.7%. The chairs are at about 47% (long/short ratio about 0.89; about 0.91/48% roughly a day ago, so barely changed). Funding is inverted at about −0.0203%/8h, paying an unusually hefty subsidy far beyond the typical cap. Open interest contract count is down about −1.5% over the past day (about −4.0% in USD-margined terms, mostly due to the price drop, with a slight reduction in contract count). The price has slid from the intraday high of about 0.0764 and is near the intraday low of about 0.06837. It dropped about 7.4% during the day, the chairs are already leaning bearish, inverted funding is paying an even heftier subsidy, the retracement is about 27%, and the price is still near the intraday low.
On one side, the chairs are pinned at about 62%, inverted funding is paying an unusually hefty subsidy, the contract count is still slightly up, and the price remains in the weekly hole. On the other, the L2 chairs are already bearish at about 47%, also collecting an even heftier subsidy from inverted funding; the weekly retracement is about 27%, and the price is near the intraday low. Does a plunge below 60,000, record outflows, and the midnight rent settlement mean this round has already been cleared out and that once this round’s rent is paid, you can take a break—or are the chairs simply still pinned at about 62%, with both sides collecting unusually hefty subsidies and the price not yet out of the hole? Post counterexamples in the comments.