On Friday evening, the latest figures show spot Ethereum ETFs had net outflows of about $131 million in a single day—the fourth consecutive day of outflows this week. Some people are treating Ethereum’s roughly 3% drop during the day as proof that institutions have finished selling and the weekend is already priced in. The positioning data tell a different story: on one side, the long share rose from about 68% to about 72%; longs are still paying funding, the price slid from its intraday high and remains near the weekly low, and open-interest contracts barely changed. On the other side, the leveraged market dropped about 7% during the day; the long share fell from about 56% to about 54%; longs are still paying funding, the price is near its intraday low, and open-interest contracts increased by about 3.4%.
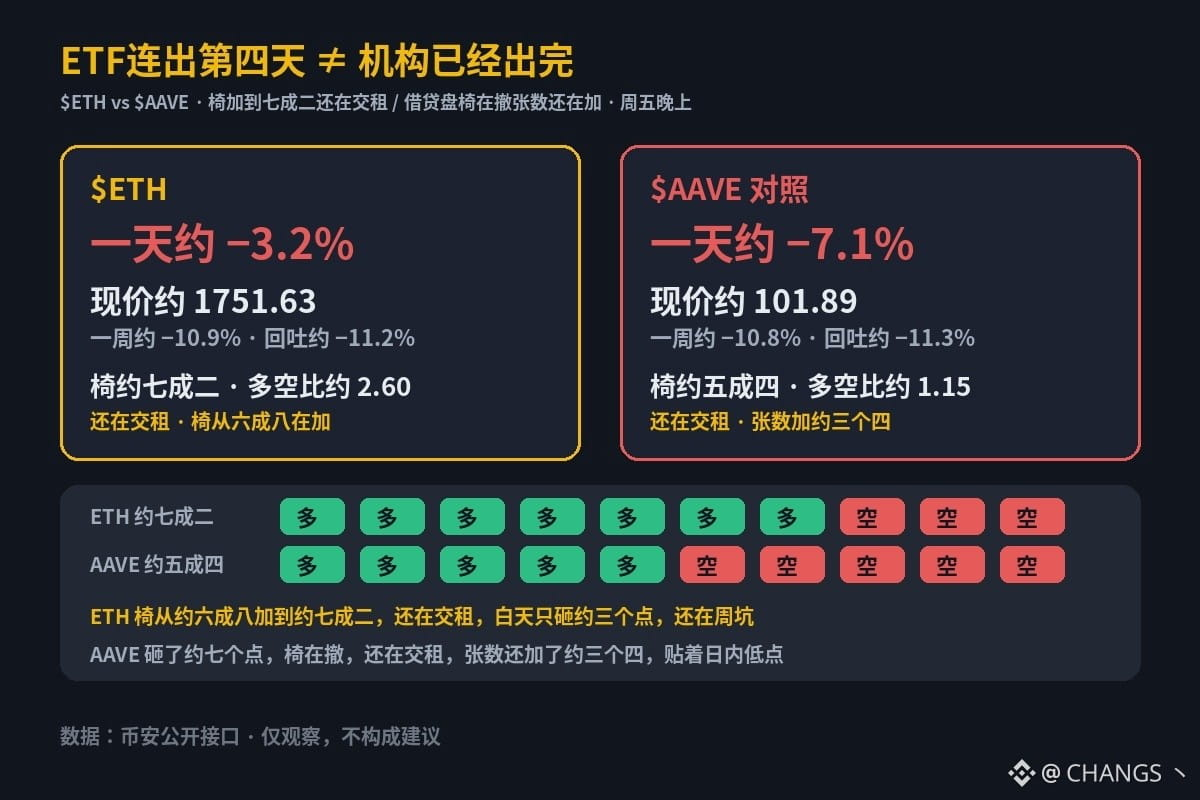
$ETH: down about −3.2% in a day / about −10.9% in a week, current price about 1751.63. Weekly high about 1972.36, down about −11.2% from that peak. Account long/short ratio about 2.60 (about 72% long; about a day ago it was about 2.17 / 68%, with longs adding). Funding rate about +0.0062%/8h, so longs are paying funding. OI contract count over the past day about +0.4% (coin-margined about −3.7%, mostly due to the price drop; contract count barely changed). Price slid from the intraday high of about 1816.95; the day’s low reached about 1717.12, and it remains near the weekly low. Longs rose from about 68% to about 72%, and are still paying funding—don’t take 1751.63, a drop of about 3.2% on the day, and a fourth straight day of ETF outflows as proof that institutions have finished selling; and especially don’t assume that longs adding while still paying funding means the weekend is already priced in.
At the same time, $AAVE was down about −7.1% in a day / about −10.8% in a week, with a current price of about 101.89. Weekly high about 114.85, down about −11.3% from that peak. Long share about 54% (long/short ratio about 1.15; about a day ago it was about 1.29 / 56%, with longs pulling back). Funding rate about +0.0058%/8h, so longs are paying funding. OI contract count over the past day about +3.4% (coin-margined about −4.5%, mostly due to the price drop; contract count is increasing). Price slid from the intraday high of about 109.99 and is near the intraday low of about 100.71. It dropped about 7.1% during the day, longs are pulling back but still paying funding, contract count is up about 3.4%, and the price is still near its intraday low.
On one side, the long share rose from about 68% to about 72%; longs are still paying funding, and the price is near the weekly low after dropping only about 3% during the day. On the other, the leveraged market dropped about 7%; longs are pulling back but still paying funding, contract count is still rising, and the price is near its intraday low. Does a fourth straight day of ETF outflows, a drop of only about 3% during the day, mean institutions have finished selling and the weekend is already priced in—or are longs simply still adding toward 72% while paying funding, as contract count in the leveraged market keeps rising? Post counterexamples in the comments.
$ETH: down about −3.2% in a day / about −10.9% in a week, current price about 1751.63. Weekly high about 1972.36, down about −11.2% from that peak. Account long/short ratio about 2.60 (about 72% long; about a day ago it was about 2.17 / 68%, with longs adding). Funding rate about +0.0062%/8h, so longs are paying funding. OI contract count over the past day about +0.4% (coin-margined about −3.7%, mostly due to the price drop; contract count barely changed). Price slid from the intraday high of about 1816.95; the day’s low reached about 1717.12, and it remains near the weekly low. Longs rose from about 68% to about 72%, and are still paying funding—don’t take 1751.63, a drop of about 3.2% on the day, and a fourth straight day of ETF outflows as proof that institutions have finished selling; and especially don’t assume that longs adding while still paying funding means the weekend is already priced in.
At the same time, $AAVE was down about −7.1% in a day / about −10.8% in a week, with a current price of about 101.89. Weekly high about 114.85, down about −11.3% from that peak. Long share about 54% (long/short ratio about 1.15; about a day ago it was about 1.29 / 56%, with longs pulling back). Funding rate about +0.0058%/8h, so longs are paying funding. OI contract count over the past day about +3.4% (coin-margined about −4.5%, mostly due to the price drop; contract count is increasing). Price slid from the intraday high of about 109.99 and is near the intraday low of about 100.71. It dropped about 7.1% during the day, longs are pulling back but still paying funding, contract count is up about 3.4%, and the price is still near its intraday low.
On one side, the long share rose from about 68% to about 72%; longs are still paying funding, and the price is near the weekly low after dropping only about 3% during the day. On the other, the leveraged market dropped about 7%; longs are pulling back but still paying funding, contract count is still rising, and the price is near its intraday low. Does a fourth straight day of ETF outflows, a drop of only about 3% during the day, mean institutions have finished selling and the weekend is already priced in—or are longs simply still adding toward 72% while paying funding, as contract count in the leveraged market keeps rising? Post counterexamples in the comments.