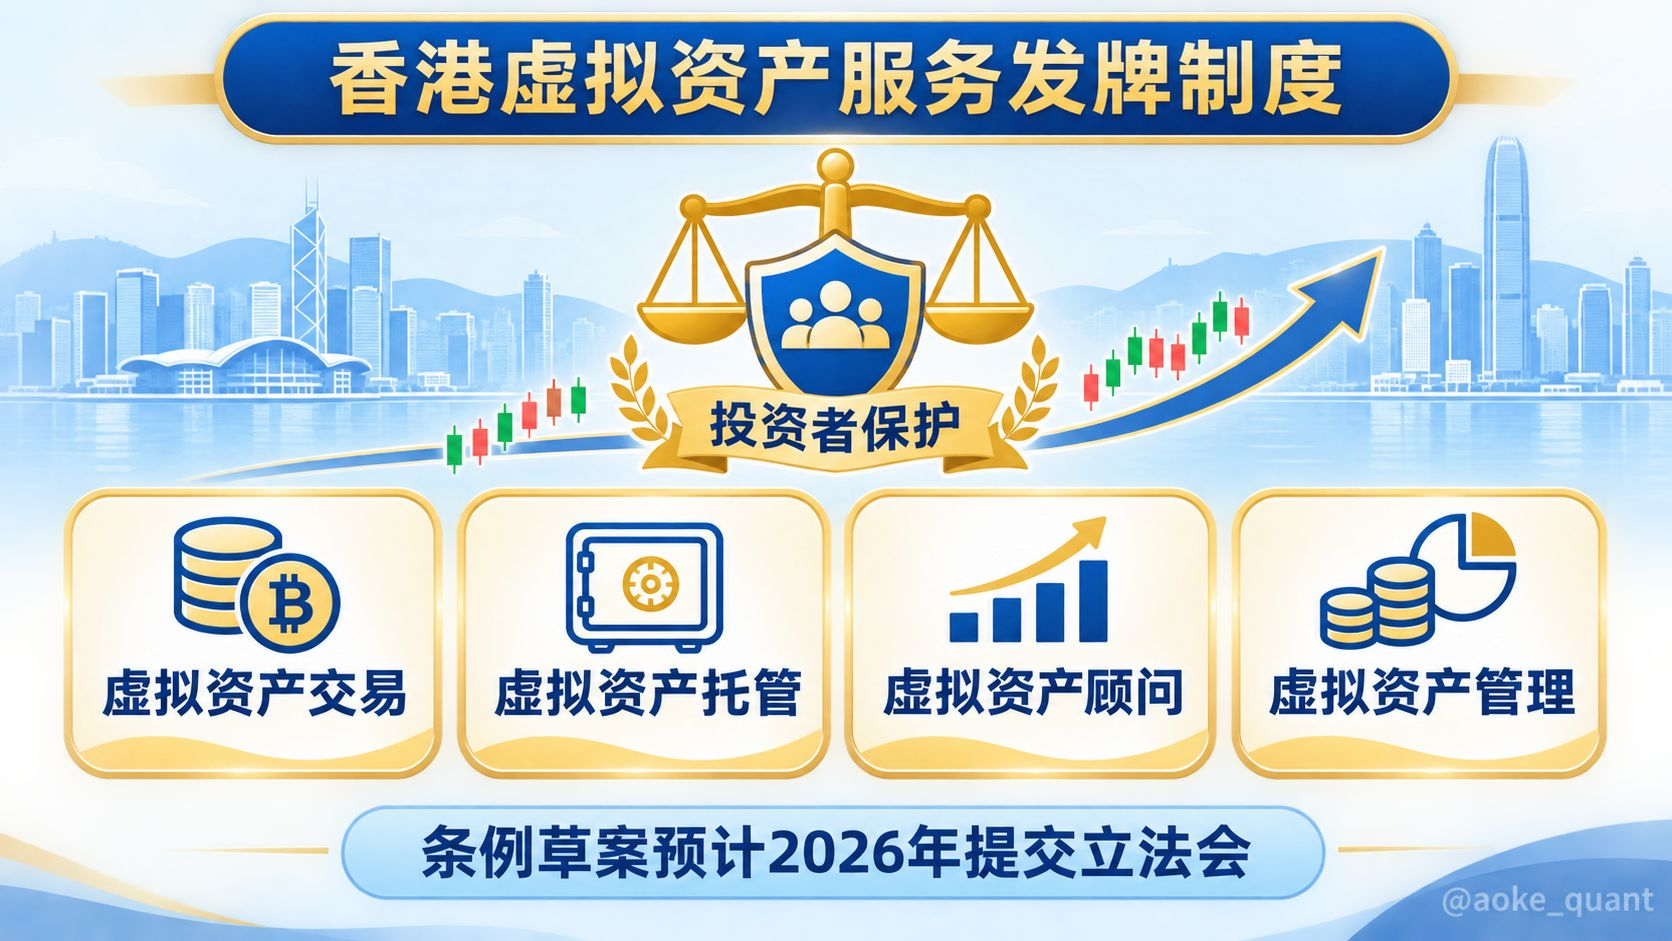
Hong Kong plans licensing for four types of virtual asset services: trading, custody, advisory and asset management
Hong Kong’s virtual asset regulation is moving from a focus on exchanges to coverage of the entire value chain. First, some background: in 2021, the Financial Services and the Treasury Bureau (FSTB) consulted the market on a licensing regime for virtual asset service providers. The regime took effect on June 1, 2023, under the Anti-Money Laundering and Counter-Terrorist Financing Ordinance. Exchanges must be licensed by the Securities and Futures Commission (SFC), and subsequent amendments also allowed overseas companies registered under the Companies Ordinance to apply for licences. Intermediaries, meanwhile, have been able to expand their business by upgrading their Type 1, 4 or 9 licences under the Securities and Futures Ordinance. But over-the-counter exchange, research and asset management firms that deal exclusively in virtual assets and do not touch securities have long operated in a regulatory gap. The key facts are these: on December 24, 2025, the FSTB and the SFC published consultation conclusions on licensing for virtual asset trading, while launching further consultations on two new licences—for providing advice on virtual assets and for managing virtual assets. Together with the previously published consultation conclusions on virtual asset custody services, this means Hong Kong plans to establish separate licences for four types of services: trading, custody, advice and asset management. The bill is expected to be submitted to the Legislative Council for consideration in 2026. Three aspects of the regime’s design merit closer examination. First, the boundaries are clear: derivatives and structured products linked to virtual assets, as well as tokenised securities, are excluded from the new licences and will remain regulated under Types 1, 2 and 11 licences under the Securities and Futures Ordinance, avoiding duplicate licensing. Second, custody requirements are being tightened: dealers must place client assets with custodians regulated by the SFC. Third, regulatory arbitrage is being blocked: the proposed virtual asset management regime will have no exemption based on a minimum investment threshold, so a licence will be required regardless of the size of a firm’s exposure, preventing firms from deliberately keeping allocations low to evade regulation. None of the three new licences will have a transition period or deemed-licence arrangements. Firms already holding upgraded Type 1, 4 or 9 licences, as well as entities affiliated with licensed platforms, may qualify for expedited approval. The impact on the crypto market can be viewed on two levels. As a matter of fact, recognised institutions such as banks will not be exempt: they must register with the SFC and be subject to frontline supervision by the Hong Kong Monetary Authority. Street-level money changers, over-the-counter exchange platforms, firms conducting research solely on virtual assets, and managers whose portfolios consist entirely of digital assets are all explicitly included within the scope of licensing. As for potential effects, the licensing threshold may drive smaller service providers out of the market and concentrate activity among larger firms. Demand for specialised services such as compliant custody and anti-money-laundering systems may emerge first. If execution channels are permitted to extend beyond licensed exchanges to other approved platforms, liquidity and service costs could improve, but this depends on assessments of the credibility of overseas platforms and remains undecided. Editorial assessment: this framework continues the principle of “same business, same risks, same rules.” In the short term, it will test the industry’s ability to comply; in the long term, it will provide the institutional foundation for an orderly entry of institutional capital. The real variables are the legislative timetable and how the detailed rules are implemented. The original regulatory documents should be treated as authoritative, and settled measures distinguished from matters still under consultation.
#香港拟对四类虚拟资产服务发牌 #BTC #ETH #BNB
Hong Kong’s virtual asset regulation is moving from a focus on exchanges to coverage of the entire value chain. First, some background: in 2021, the Financial Services and the Treasury Bureau (FSTB) consulted the market on a licensing regime for virtual asset service providers. The regime took effect on June 1, 2023, under the Anti-Money Laundering and Counter-Terrorist Financing Ordinance. Exchanges must be licensed by the Securities and Futures Commission (SFC), and subsequent amendments also allowed overseas companies registered under the Companies Ordinance to apply for licences. Intermediaries, meanwhile, have been able to expand their business by upgrading their Type 1, 4 or 9 licences under the Securities and Futures Ordinance. But over-the-counter exchange, research and asset management firms that deal exclusively in virtual assets and do not touch securities have long operated in a regulatory gap. The key facts are these: on December 24, 2025, the FSTB and the SFC published consultation conclusions on licensing for virtual asset trading, while launching further consultations on two new licences—for providing advice on virtual assets and for managing virtual assets. Together with the previously published consultation conclusions on virtual asset custody services, this means Hong Kong plans to establish separate licences for four types of services: trading, custody, advice and asset management. The bill is expected to be submitted to the Legislative Council for consideration in 2026. Three aspects of the regime’s design merit closer examination. First, the boundaries are clear: derivatives and structured products linked to virtual assets, as well as tokenised securities, are excluded from the new licences and will remain regulated under Types 1, 2 and 11 licences under the Securities and Futures Ordinance, avoiding duplicate licensing. Second, custody requirements are being tightened: dealers must place client assets with custodians regulated by the SFC. Third, regulatory arbitrage is being blocked: the proposed virtual asset management regime will have no exemption based on a minimum investment threshold, so a licence will be required regardless of the size of a firm’s exposure, preventing firms from deliberately keeping allocations low to evade regulation. None of the three new licences will have a transition period or deemed-licence arrangements. Firms already holding upgraded Type 1, 4 or 9 licences, as well as entities affiliated with licensed platforms, may qualify for expedited approval. The impact on the crypto market can be viewed on two levels. As a matter of fact, recognised institutions such as banks will not be exempt: they must register with the SFC and be subject to frontline supervision by the Hong Kong Monetary Authority. Street-level money changers, over-the-counter exchange platforms, firms conducting research solely on virtual assets, and managers whose portfolios consist entirely of digital assets are all explicitly included within the scope of licensing. As for potential effects, the licensing threshold may drive smaller service providers out of the market and concentrate activity among larger firms. Demand for specialised services such as compliant custody and anti-money-laundering systems may emerge first. If execution channels are permitted to extend beyond licensed exchanges to other approved platforms, liquidity and service costs could improve, but this depends on assessments of the credibility of overseas platforms and remains undecided. Editorial assessment: this framework continues the principle of “same business, same risks, same rules.” In the short term, it will test the industry’s ability to comply; in the long term, it will provide the institutional foundation for an orderly entry of institutional capital. The real variables are the legislative timetable and how the detailed rules are implemented. The original regulatory documents should be treated as authoritative, and settled measures distinguished from matters still under consultation.
#香港拟对四类虚拟资产服务发牌 #BTC #ETH #BNB