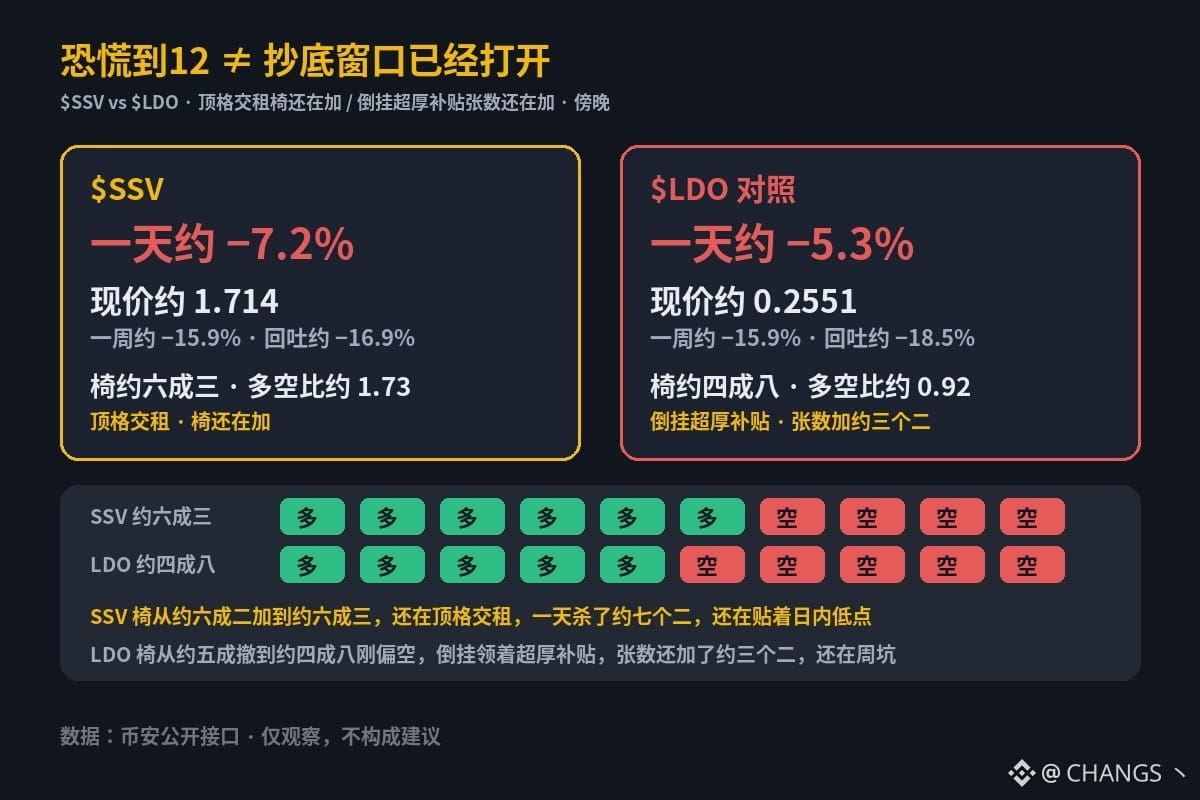
By Friday evening, the Fear & Greed Index was still stuck around 12 in extreme fear, Nasdaq futures were still down about 1.6% from the previous close, and the U.S. cash session hadn’t opened yet. Some are treating a roughly 7% drop in staking tokens during the day and fear this extreme as proof that the dip-buying window is open and this round of risk has been fully priced in. The ledger says otherwise: on one side, the long share rose from about 62% to about 63%, still paying at the funding-rate cap; price plunged about 7.2% in a day and remains near the intraday low. On the other, the long share fell from about 50% to around 48%, just turning bearish; the inverted funding rate is paying an unusually hefty subsidy, far beyond the typical cap, and open-interest contract count is up about 3.2%.
$SSV: down about 7.2% in a day / 15.9% in a week, currently around 1.714. Weekly high around 2.061, a pullback of about 16.9%. Account long/short ratio around 1.73 (about 63% long; around a day ago it was about 1.61 / 62% long, so longs are adding). Funding is at the cap, around +0.010%/8h, meaning longs are paying. OI contract count over the past day is down about 3.0% (coin-margined OI down about 9.9%, mostly due to the price drop, with contract count slightly lower). Price slid from an intraday high around 1.849 and is near the intraday low around 1.703, still in the weekly trough. Longs rose from about 62% to about 63%, and are still paying at the funding cap—don’t take 1.714, a roughly 7.2% daily drop, and fear at 12 as proof that the dip-buying window is open; even less so while longs are still adding and paying at the cap, as proof that this round of risk has been fully priced in.
Also in the same session, $LDO was down about 5.3% in a day / 15.9% in a week, currently around 0.2551. Weekly high around 0.3125, a pullback of about 18.5%. Longs are around 48% (long/short ratio around 0.92; around a day ago it was about 1.01 / 50% long, so longs are pulling back). The inverted funding rate is around −0.0190%/8h, paying an unusually hefty subsidy, far beyond the typical cap. OI contract count over the past day is up about 3.2% (coin-margined OI down about 2.6%, mostly due to the price drop, while contract count is rising). Price slid from an intraday high around 0.2701 and is near the intraday low around 0.251, still in the weekly trough. Longs fell from about 50% to around 48%, just turning bearish; the inverted funding rate is paying an unusually hefty subsidy, and contract count is up about 3.2%.
On one side, longs rose from about 62% to about 63%, still paying at the funding-rate cap; price plunged about 7.2% in a day and remains near the intraday low. On the other, longs fell from about 50% to around 48%, just turning bearish; the inverted funding rate is paying an unusually hefty subsidy, far beyond the typical cap, and contract count is up about 3.2%. Does fear at 12 and a roughly 7% plunge in staking tokens mean the dip-buying window is open and this round of risk has been fully priced in—or are we simply still in the weekly trough, with the U.S. session not yet open, longs still adding while paying at the cap on one side, and positions still growing while receiving an unusually hefty subsidy on the other? Post counterexamples in the comments.
$SSV: down about 7.2% in a day / 15.9% in a week, currently around 1.714. Weekly high around 2.061, a pullback of about 16.9%. Account long/short ratio around 1.73 (about 63% long; around a day ago it was about 1.61 / 62% long, so longs are adding). Funding is at the cap, around +0.010%/8h, meaning longs are paying. OI contract count over the past day is down about 3.0% (coin-margined OI down about 9.9%, mostly due to the price drop, with contract count slightly lower). Price slid from an intraday high around 1.849 and is near the intraday low around 1.703, still in the weekly trough. Longs rose from about 62% to about 63%, and are still paying at the funding cap—don’t take 1.714, a roughly 7.2% daily drop, and fear at 12 as proof that the dip-buying window is open; even less so while longs are still adding and paying at the cap, as proof that this round of risk has been fully priced in.
Also in the same session, $LDO was down about 5.3% in a day / 15.9% in a week, currently around 0.2551. Weekly high around 0.3125, a pullback of about 18.5%. Longs are around 48% (long/short ratio around 0.92; around a day ago it was about 1.01 / 50% long, so longs are pulling back). The inverted funding rate is around −0.0190%/8h, paying an unusually hefty subsidy, far beyond the typical cap. OI contract count over the past day is up about 3.2% (coin-margined OI down about 2.6%, mostly due to the price drop, while contract count is rising). Price slid from an intraday high around 0.2701 and is near the intraday low around 0.251, still in the weekly trough. Longs fell from about 50% to around 48%, just turning bearish; the inverted funding rate is paying an unusually hefty subsidy, and contract count is up about 3.2%.
On one side, longs rose from about 62% to about 63%, still paying at the funding-rate cap; price plunged about 7.2% in a day and remains near the intraday low. On the other, longs fell from about 50% to around 48%, just turning bearish; the inverted funding rate is paying an unusually hefty subsidy, far beyond the typical cap, and contract count is up about 3.2%. Does fear at 12 and a roughly 7% plunge in staking tokens mean the dip-buying window is open and this round of risk has been fully priced in—or are we simply still in the weekly trough, with the U.S. session not yet open, longs still adding while paying at the cap on one side, and positions still growing while receiving an unusually hefty subsidy on the other? Post counterexamples in the comments.