$AAVE liquidity: should large borrowings be slowed down? In its November 11 proposal for dynamic borrow caps, LlamaRisk turned this risk-management trade-off into an executable rule: the total limit remains subject to a hard governance cap, but borrowable capacity is replenished in batches, allowing time to respond to unusual outflows.
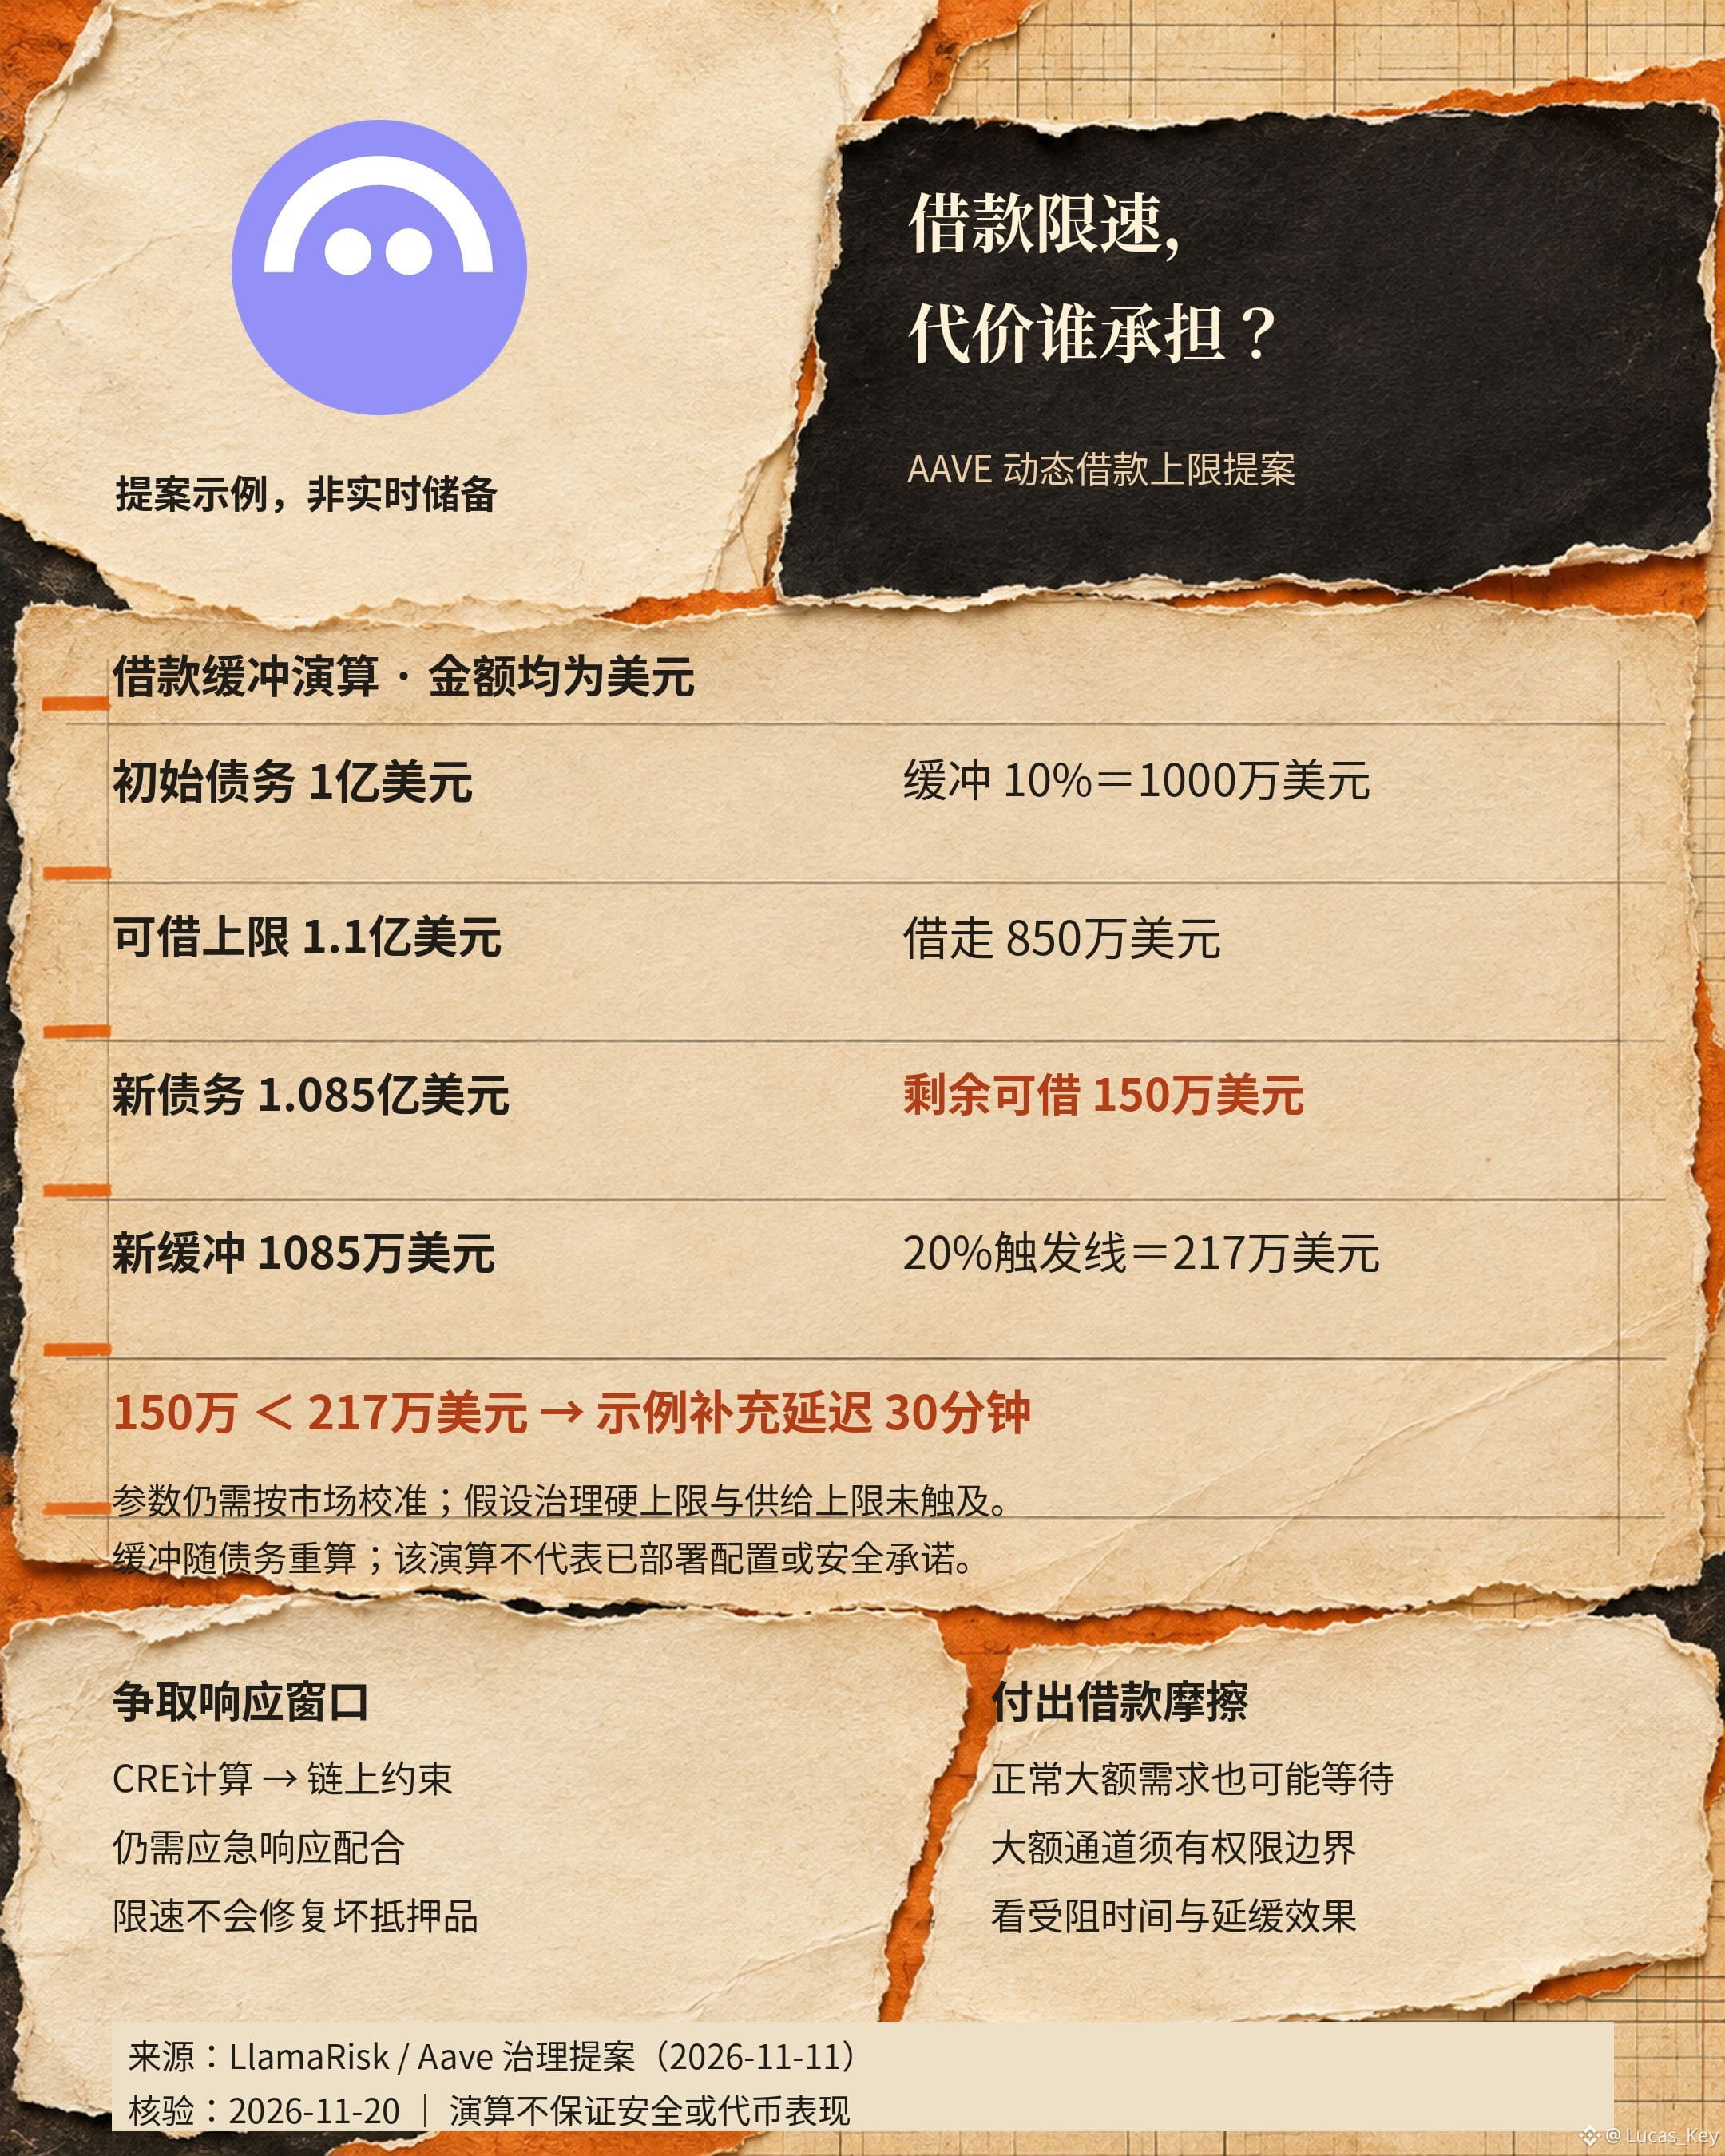
The proposal’s example starts with $100 million in debt and a 10% buffer, giving a borrow cap of $110 million. After $8.5 million is borrowed, debt rises to $108.5 million, leaving $1.5 million in borrowable capacity; the buffer grows with the debt to $10.85 million, and the 20% trigger is $2.17 million. The $1.5 million is below the trigger, so replenishment must wait through the illustrative 30-minute delay. These are example parameters for calculation; they still need to be calibrated to market conditions before deployment and should not be treated as real-time reserve data.
The case for rate limits is straightforward: a static cap limits how much can be borrowed, but not how quickly it can be taken. Once unusual collateral enters the system, automatic replenishment intervals could leave a window for emergency response. In the proposal, Chainlink CRE handles the cap-increase calculation, while on-chain checks constrain how much can be added each time; this limits the pace of borrowing, but does not fix the collateral or its price.
There are also valid reasons to oppose adding friction: legitimate large borrowings, leverage adjustments, and unusual outflows may all be equally urgent. Tightening capacity could leave ordinary users waiting; creating a separate channel for approved large borrowers would require clear explanations of authorization, auditing, and revocation boundaries.
This naturally connects WETH borrowing demand on $ETH , the CRE calculation process associated with $LINK , and AAVE governance—but each plays a different role. My criteria for evaluating the proposal are whether future calibration reports can disclose, all at once, how long normal borrowing is impeded, how much unusual outflows are delayed, and what permissions the large-borrower channel carries. Without this data, the words “automated risk management” alone aren’t enough to judge the net benefit. Source: Aave governance proposal and example, verified November 20, 2026. Risk notice: This post discusses the proposal’s design and does not guarantee safety or token performance. This post may receive platform creator rewards.
The proposal’s example starts with $100 million in debt and a 10% buffer, giving a borrow cap of $110 million. After $8.5 million is borrowed, debt rises to $108.5 million, leaving $1.5 million in borrowable capacity; the buffer grows with the debt to $10.85 million, and the 20% trigger is $2.17 million. The $1.5 million is below the trigger, so replenishment must wait through the illustrative 30-minute delay. These are example parameters for calculation; they still need to be calibrated to market conditions before deployment and should not be treated as real-time reserve data.
The case for rate limits is straightforward: a static cap limits how much can be borrowed, but not how quickly it can be taken. Once unusual collateral enters the system, automatic replenishment intervals could leave a window for emergency response. In the proposal, Chainlink CRE handles the cap-increase calculation, while on-chain checks constrain how much can be added each time; this limits the pace of borrowing, but does not fix the collateral or its price.
There are also valid reasons to oppose adding friction: legitimate large borrowings, leverage adjustments, and unusual outflows may all be equally urgent. Tightening capacity could leave ordinary users waiting; creating a separate channel for approved large borrowers would require clear explanations of authorization, auditing, and revocation boundaries.
This naturally connects WETH borrowing demand on $ETH , the CRE calculation process associated with $LINK , and AAVE governance—but each plays a different role. My criteria for evaluating the proposal are whether future calibration reports can disclose, all at once, how long normal borrowing is impeded, how much unusual outflows are delayed, and what permissions the large-borrower channel carries. Without this data, the words “automated risk management” alone aren’t enough to judge the net benefit. Source: Aave governance proposal and example, verified November 20, 2026. Risk notice: This post discusses the proposal’s design and does not guarantee safety or token performance. This post may receive platform creator rewards.