Market got the China NAND selloff completely wrong.
Everyone panicked over $SNDK / Kioxia after Trendforce revisions on Chinese enterprise SSD cuts. Street read it as demand destruction + oversupply spiral.
But Phison CEO just clarified what's actually happening:
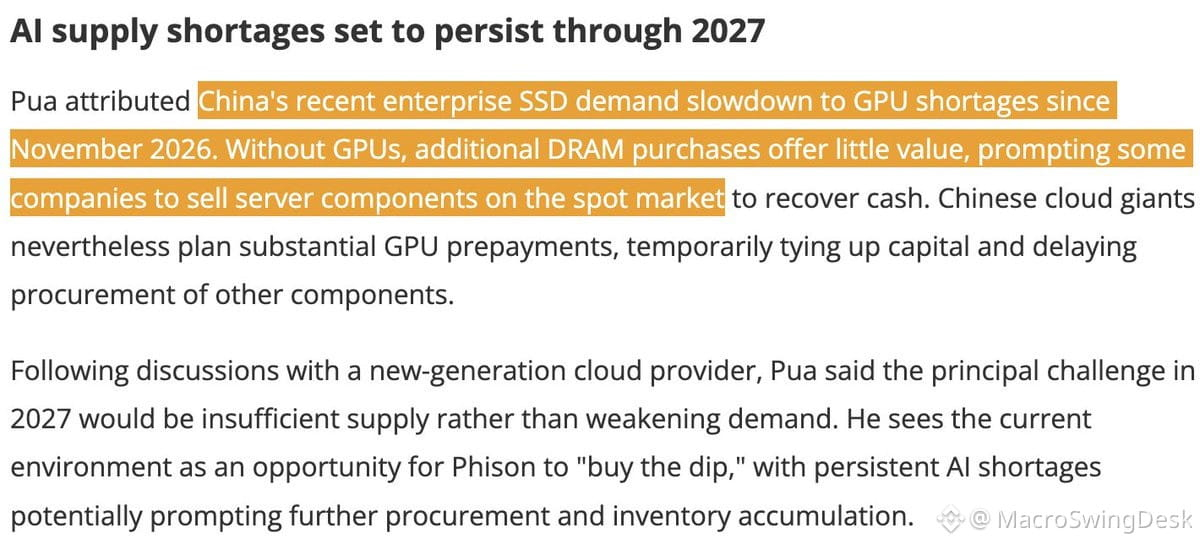
• China's enterprise SSD slowdown = GPU shortage since Nov 2024
• Without GPUs, buying more SSDs is pointless
• Chinese cloud giants are liquidating server components (including SSDs) on spot market to free up cash
• Why? They need capital for massive GPU prepayments
• This creates procurement timing mismatch — not structural demand collapse
So the NAND "weakness" is:
→ Inventory liquidation to raise cash for GPU orders
→ Deferred procurement, not canceled orders
→ Spot price volatility from temporary supply dump
Phison CEO's actual take: "The principal challenge in 2027 would be insufficient supply rather than weakening demand."
He's saying inventories are too low for anticipated 2027 demand and sees this as a NAND accumulation opportunity.
TLDR: This isn't demand destruction. It's a capital rotation bottleneck. Chinese CSPs are shuffling budgets to secure GPUs first, then they'll come back for storage.
Market sold the headline. Reality is a procurement queue reshuffle.
Ironic that the bottleneck in China cycled back to GPUs again.
Everyone panicked over $SNDK / Kioxia after Trendforce revisions on Chinese enterprise SSD cuts. Street read it as demand destruction + oversupply spiral.
But Phison CEO just clarified what's actually happening:
• China's enterprise SSD slowdown = GPU shortage since Nov 2024
• Without GPUs, buying more SSDs is pointless
• Chinese cloud giants are liquidating server components (including SSDs) on spot market to free up cash
• Why? They need capital for massive GPU prepayments
• This creates procurement timing mismatch — not structural demand collapse
So the NAND "weakness" is:
→ Inventory liquidation to raise cash for GPU orders
→ Deferred procurement, not canceled orders
→ Spot price volatility from temporary supply dump
Phison CEO's actual take: "The principal challenge in 2027 would be insufficient supply rather than weakening demand."
He's saying inventories are too low for anticipated 2027 demand and sees this as a NAND accumulation opportunity.
TLDR: This isn't demand destruction. It's a capital rotation bottleneck. Chinese CSPs are shuffling budgets to secure GPUs first, then they'll come back for storage.
Market sold the headline. Reality is a procurement queue reshuffle.
Ironic that the bottleneck in China cycled back to GPUs again.