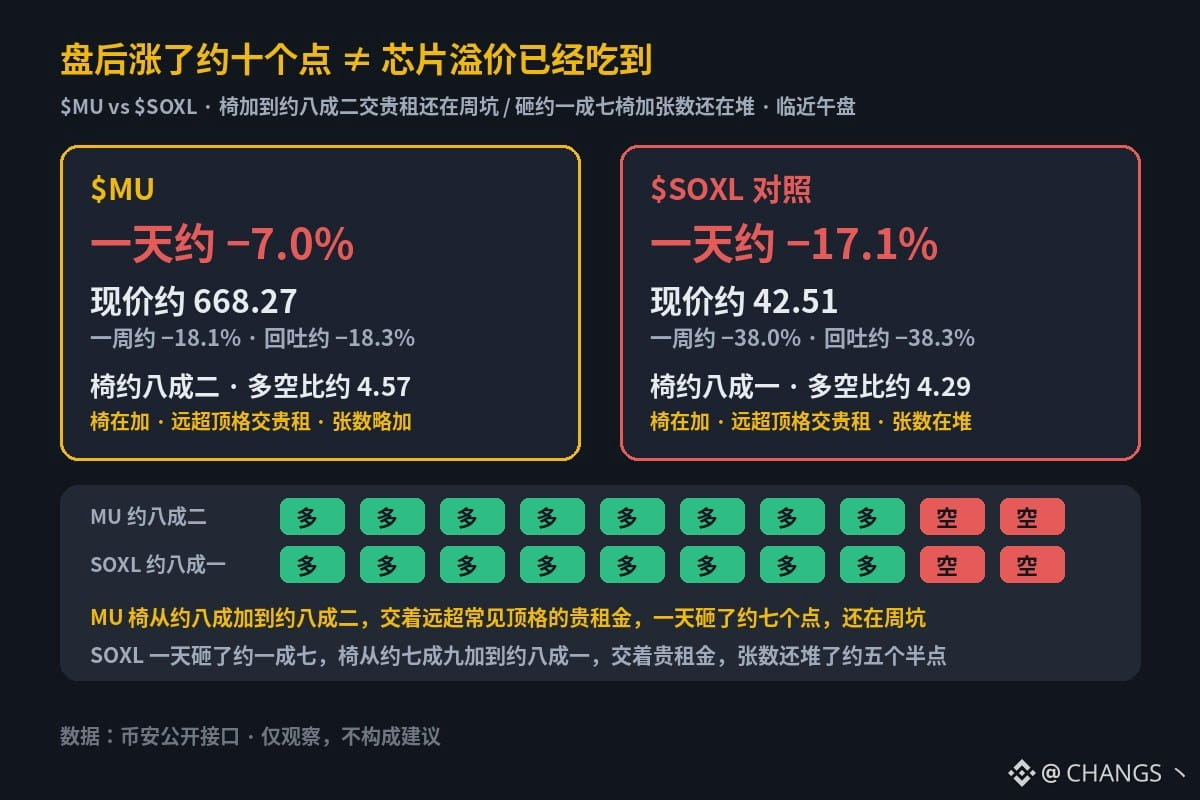
Around midday, the plaza was still buzzing about Micron rising roughly ten points after hours. Some took the chip basket touching its intraday high during the day, with the after-hours gain still trending, as proof that the chip premium had already been captured and they could clock out for the weekend. The ledger tells a different story: on one side, longs rose from about 80% to about 82%, paying funding far above the usual cap, while the asset plunged about 7% in a day, sliding from an intraday high near 761 to near the intraday low and still stuck in its weekly trough; on the other, a leveraged chip basket plunged about 17% in a day, with longs rising from about 79% to about 81%. It too was paying funding far above the usual cap, while open interest grew by about 5.5% and the price gave back about 38%.
$MU : down about 7.0% in a day and 18.1% in a week; current price about 668.27. Weekly high about 817.83, a pullback of about 18.3%. The account long/short ratio is about 4.57 (about 82% long; about a day ago it was about 4.08/80%, with longs adding). Funding is about +0.0290%/8h, far above the usual cap. OI contracts are up about 1.1% over the past day (U-margined OI about −4.7%, mostly due to the price drop, with contract count slightly higher). Price slid from an intraday high near 761.21 to near the intraday low around 667.67, and is still in its weekly trough. Longs rose from about 80% to about 82%, while still paying funding far above the usual cap—so don’t take 668.27, the after-hours gain of roughly ten points still trending, or the daytime touch of the intraday high as proof that the chip premium has already been captured. And don’t take longs still adding and paying expensive funding as a reason to clock out for the weekend.
In the same session, $SOXL was down about 17.1% in a day and 38.0% in a week; current price about 42.51. Weekly high about 68.87, a pullback of about 38.3%. Longs were about 81% (long/short ratio about 4.29; about a day ago it was about 3.67/79%, with longs adding). Funding was about +0.0537%/8h, far above the usual cap. OI was up about 5.5% over the past day (U-margined OI about −11.1%, mostly due to the price drop, while contract count kept piling up). Price slid from an intraday high around 56.47 to near the intraday low around 42.39, and is still in its weekly trough. Longs rose from about 79% to about 81%, while still paying funding far above the usual cap, and contract count was up about 5.5%.
On one side, Micron longs rose from about 80% to about 82%, paying funding far above the usual cap, while the asset plunged about 7% in a day and remained in its weekly trough. On the other, the leveraged chip basket plunged about 17% in a day, longs rose from about 79% to about 81%, funding was also far above the usual cap, contract count piled up by about 5.5%, and the price gave back about 38%. Does the after-hours gain of roughly ten points still trending mean the chip premium has already been captured and it’s safe to clock out for the weekend—or are longs simply still adding and paying expensive funding on one side, while the other plunged about 17% with contract count still piling up, and neither has climbed out of the hole? Post counterexamples in the comments.
$MU : down about 7.0% in a day and 18.1% in a week; current price about 668.27. Weekly high about 817.83, a pullback of about 18.3%. The account long/short ratio is about 4.57 (about 82% long; about a day ago it was about 4.08/80%, with longs adding). Funding is about +0.0290%/8h, far above the usual cap. OI contracts are up about 1.1% over the past day (U-margined OI about −4.7%, mostly due to the price drop, with contract count slightly higher). Price slid from an intraday high near 761.21 to near the intraday low around 667.67, and is still in its weekly trough. Longs rose from about 80% to about 82%, while still paying funding far above the usual cap—so don’t take 668.27, the after-hours gain of roughly ten points still trending, or the daytime touch of the intraday high as proof that the chip premium has already been captured. And don’t take longs still adding and paying expensive funding as a reason to clock out for the weekend.
In the same session, $SOXL was down about 17.1% in a day and 38.0% in a week; current price about 42.51. Weekly high about 68.87, a pullback of about 38.3%. Longs were about 81% (long/short ratio about 4.29; about a day ago it was about 3.67/79%, with longs adding). Funding was about +0.0537%/8h, far above the usual cap. OI was up about 5.5% over the past day (U-margined OI about −11.1%, mostly due to the price drop, while contract count kept piling up). Price slid from an intraday high around 56.47 to near the intraday low around 42.39, and is still in its weekly trough. Longs rose from about 79% to about 81%, while still paying funding far above the usual cap, and contract count was up about 5.5%.
On one side, Micron longs rose from about 80% to about 82%, paying funding far above the usual cap, while the asset plunged about 7% in a day and remained in its weekly trough. On the other, the leveraged chip basket plunged about 17% in a day, longs rose from about 79% to about 81%, funding was also far above the usual cap, contract count piled up by about 5.5%, and the price gave back about 38%. Does the after-hours gain of roughly ten points still trending mean the chip premium has already been captured and it’s safe to clock out for the weekend—or are longs simply still adding and paying expensive funding on one side, while the other plunged about 17% with contract count still piling up, and neither has climbed out of the hole? Post counterexamples in the comments.