#IsAnthropic’s$1.5TMarketCapJustified?
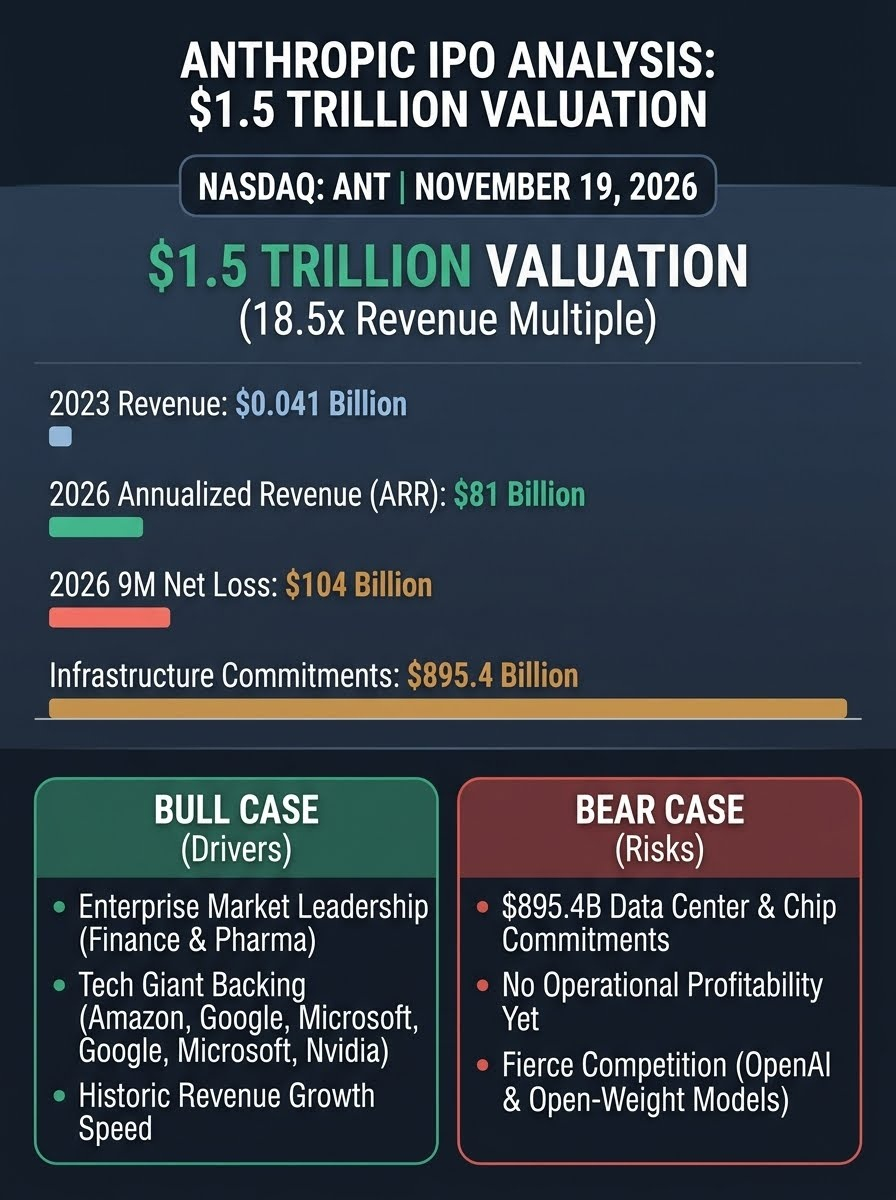
Anthropic’s $1.5 trillion IPO valuation, while supported by one of the fastest revenue growth rates in history, has divided Wall Street because of its massive infrastructure costs and lack of profitability. 🚀⚖️
Here’s the key picture behind the company’s price tag, as it began trading on Nasdaq under the ticker ANT on November 19, 2026:
📈 The Case for the Valuation (Bull Case)
Head-Spinning Growth: Revenue rose from $41 million in 2023 to an annualized run rate (ARR) of $81 billion as of October 2026.Enterprise Strength: Critical sectors such as finance and pharmaceuticals are prioritizing Claude because of its focus on security.Support from Giants: Tech giants such as Amazon, Google, Microsoft, and Nvidia are both investors in and strategic partners of the company.A Reasonable Multiple: Compared with an $81 billion revenue run rate, a $1.5 trillion valuation represents an 18.5x revenue multiple, considered reasonable for a leader in a hypergrowth phase.
⚠️ Risks and Open Questions (Bear Case)
Massive Infrastructure Commitments: Long-term payment commitments to data center and chip suppliers have reached $895.4 billion.Net Loss: The company reported a net loss of $104 billion in the first nine months of 2026 (mostly accounting-related), and has yet to achieve operating profitability.Fierce Competition: OpenAI’s new models and lower-cost open-source competitors are putting pressure on profit margins.
⚖️ Summary Table
MetricStatus (November 2026)ImpactValuation~$1.5 trillion📊 The largest tech IPO in historyAnnual Revenue Run Rate~$81 billion🟢 Support from massive growthInfrastructure Commitments~$895.4 billion🔴 Major pressure on cash flow
In short, $1.5 trillion reflects not today’s profits, but the expectation that Anthropic will become the new operating system of the AI era. 🎯
$ANTHROPIC $IDOL $UAI
Anthropic’s $1.5 trillion IPO valuation, while supported by one of the fastest revenue growth rates in history, has divided Wall Street because of its massive infrastructure costs and lack of profitability. 🚀⚖️
Here’s the key picture behind the company’s price tag, as it began trading on Nasdaq under the ticker ANT on November 19, 2026:
📈 The Case for the Valuation (Bull Case)
Head-Spinning Growth: Revenue rose from $41 million in 2023 to an annualized run rate (ARR) of $81 billion as of October 2026.Enterprise Strength: Critical sectors such as finance and pharmaceuticals are prioritizing Claude because of its focus on security.Support from Giants: Tech giants such as Amazon, Google, Microsoft, and Nvidia are both investors in and strategic partners of the company.A Reasonable Multiple: Compared with an $81 billion revenue run rate, a $1.5 trillion valuation represents an 18.5x revenue multiple, considered reasonable for a leader in a hypergrowth phase.
⚠️ Risks and Open Questions (Bear Case)
Massive Infrastructure Commitments: Long-term payment commitments to data center and chip suppliers have reached $895.4 billion.Net Loss: The company reported a net loss of $104 billion in the first nine months of 2026 (mostly accounting-related), and has yet to achieve operating profitability.Fierce Competition: OpenAI’s new models and lower-cost open-source competitors are putting pressure on profit margins.
⚖️ Summary Table
MetricStatus (November 2026)ImpactValuation~$1.5 trillion📊 The largest tech IPO in historyAnnual Revenue Run Rate~$81 billion🟢 Support from massive growthInfrastructure Commitments~$895.4 billion🔴 Major pressure on cash flow
In short, $1.5 trillion reflects not today’s profits, but the expectation that Anthropic will become the new operating system of the AI era. 🎯
$ANTHROPIC $IDOL $UAI