
A roughly $1 BILLION cryptocurrency.
⠀
Approximately 3.79 BILLION tokens circulating.
⠀
Around 2.9 MILLION tokens unlocking daily under the published schedule.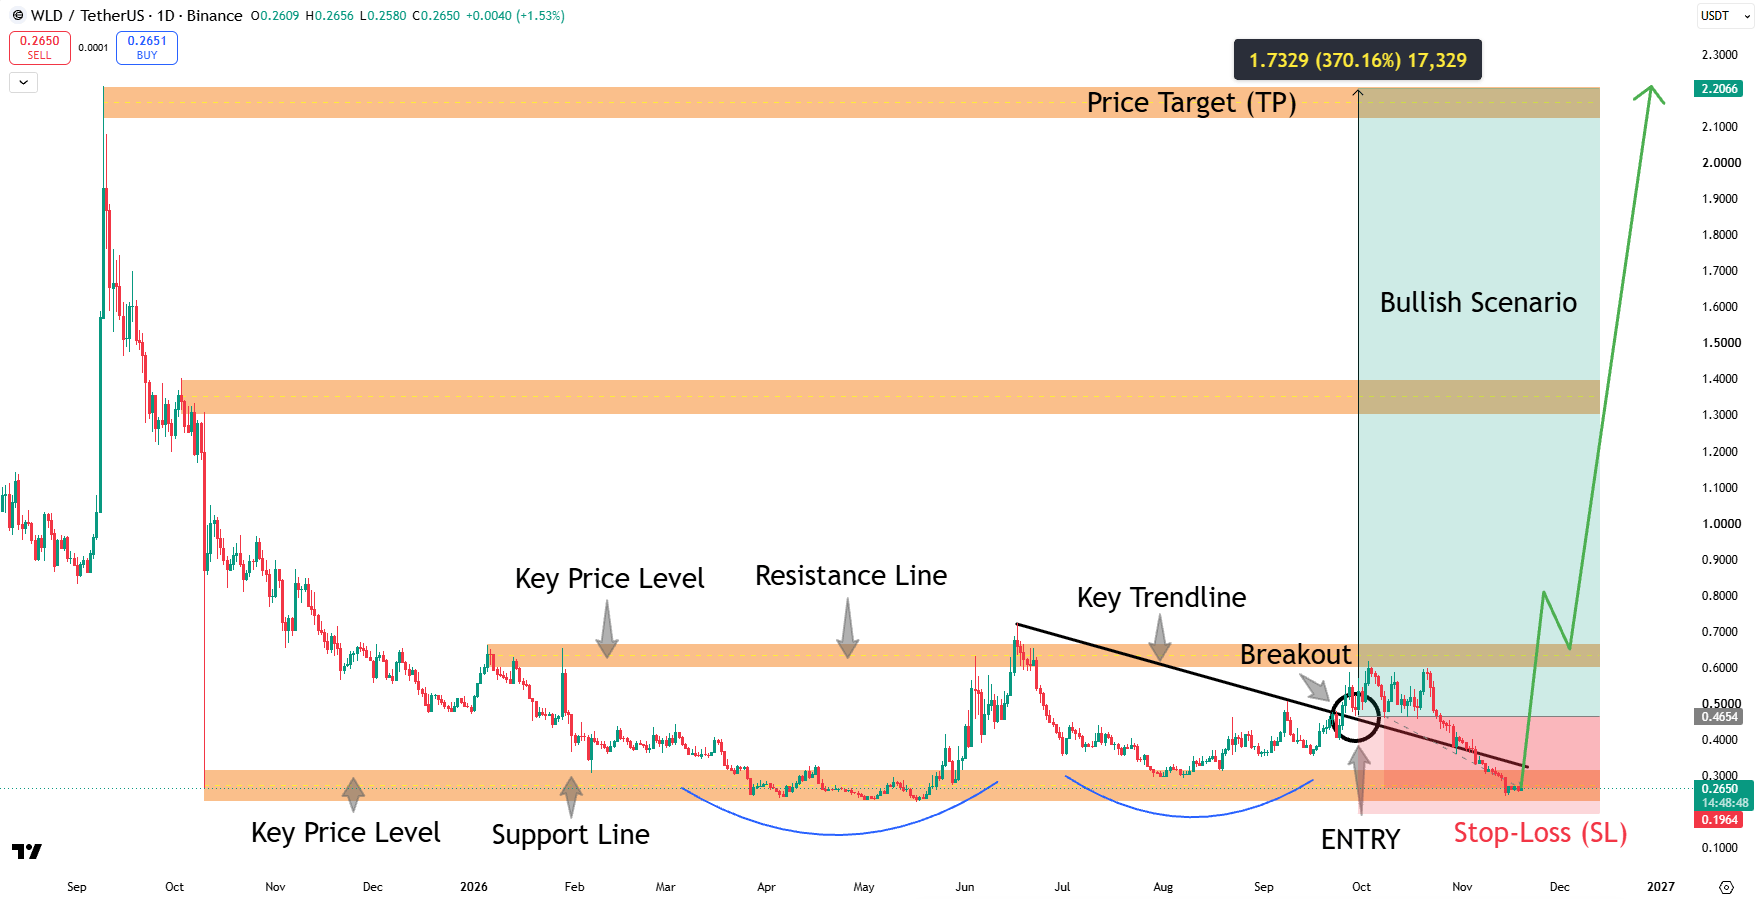
⠀
And a token trading approximately 97.8% below its all-time high.
⠀
But here's the contradiction.
⠀
Proving that someone is human could become valuable internet infrastructure.
⠀
That does not automatically make the associated token a valuable investment.
⠀
Is $WLD an overlooked bet on identity in an AI-driven world?

⠀
Or can World ID succeed while token holders face difficult supply economics?
⠀
Let's examine the numbers.
⠀
01 | WHAT IS WORLD?
⠀
World is building an identity and financial network.
⠀
World ID provides credentials that applications can use to verify attributes such as unique humanness.
⠀
The Orb supports its biometric verification process.
⠀
World Chain provides blockchain infrastructure.
⠀
WLD is the associated token.
⠀
These components are related.
⠀
They are not interchangeable.
⠀
A successful identity product can create useful services without automatically producing proportional demand for WLD.
⠀
The investment thesis needs a clear connection between adoption, payments, and token economics.
⠀
A large problem establishes an opportunity.
⠀
The payment mechanism determines what holders capture.
⠀
02 | THE NUMBERS THAT MATTER
⠀
November 19, 2026 snapshot:
⠀
WLD Price: ~$0.2646
Market Cap: ~$1.00B
Initial-Supply FDV: ~$2.65B
Circulating Supply: ~3.792B WLD
Initial Token Supply: 10B WLD
Circulating / Initial Supply: ~37.9%
24H WLD Trading Volume: ~$205.82M
All-Time High: ~$11.82
Decline From ATH: ~97.8%
⠀
SUPPLY FRAMEWORK:
⠀
Published Aggregate Unlock Rate: ~2.9M WLD per day
Approximate 30-Day Unlock Amount: ~87M WLD
Illustrative Value at Snapshot Price: ~$23M
⠀
The FDV is calculated against the initial 10 billion tokens.
⠀
That figure should not be described as an unconditional lifetime maximum.
⠀
Unlocking also does not mean every token immediately enters the market.
⠀
Eligibility, distribution, and selling are different events.
⠀
03 | THE AI THESIS NEEDS A SECOND STEP
⠀
Bots, synthetic accounts, and impersonation create a potential market for human verification.
⠀
But identifying a problem does not establish that one solution will dominate.
⠀
Applications can evaluate multiple approaches.
⠀
Users can reject additional onboarding friction.
⠀
And customers can integrate a service without accepting every proposed price.
⠀
For WLD, the relevant sequence is:
⠀
Applications need verification.
⠀
They choose World ID.
⠀
They continue using it.
⠀
They pay under a working fee model.
⠀
And those payments create an identifiable benefit for the token.
⠀
Skipping the last steps turns an investment thesis into a narrative.
⠀
04 | VERIFIED PEOPLE ARE NOT PAYING CUSTOMERS
⠀
A cumulative verification count measures enrollment.
⠀
It does not establish monthly active usage.
⠀
App downloads do not establish retained users.
⠀
And users claiming distributed tokens do not establish that third-party applications are paying for verification.
⠀
The stronger commercial evidence would include:
⠀
Active verified users.
⠀
Repeat authentication.
⠀
Applications with recurring paid usage.
⠀
And customer retention after incentives.
⠀
These measurements answer different questions.
⠀
A growing identity network can be valuable.
⠀
Its commercial value becomes clearer when outside customers repeatedly pay for the service.
⠀
05 | THE WORLD ID FEE MODEL
⠀
Official materials describe World ID fees payable in WLD.
⠀
The intended structure charges applications while keeping protocol usage free for end users.
⠀
Credential issuers can receive credential fees.
⠀
A separate protocol fee supports the protocol.
⠀
That provides a potential connection between useful identity services and token demand.
⠀
But capability is not the same as activation.
⠀
A published pricing framework is not evidence of collected revenue.
⠀
The retrieved materials did not establish a current, verified recurring fee total.
⠀
Therefore, projected monetization should remain a future opportunity rather than be presented as existing earnings.
⠀
06 | FEES DO NOT AUTOMATICALLY MEAN BURNS
⠀
World's published framework allows different uses for fee income.
⠀
Credential issuers can determine how to use their portion.
⠀
Protocol fees may support operations or include a burn allocation.
⠀
That does not establish that every fee is destroyed.
⠀
It also does not create an automatic dividend for WLD holders.
⠀
The relevant verification is the active allocation mechanism.
⠀
How much was collected?
⠀
Who received it?
⠀
What was retained, distributed, or burned?
⠀
A potential burn mechanism improves the range of possible outcomes.
⠀
Executed, recurring burns establish the actual supply effect.
⠀
07 | THE JULY UNLOCK REDUCTION
⠀
The official schedule reduced aggregate daily unlocks by approximately 43% on July 24, 2026.
⠀
The published rate moved from around 5.1 million WLD to around 2.9 million.
⠀
That is a meaningful reduction in the pace of newly transferable supply.
⠀
It is not the end of vesting.
⠀
The reduced rate still represents approximately 87 million tokens over 30 days.
⠀
Investors should evaluate the remaining rate against demand rather than only celebrate the percentage reduction.
⠀
A smaller supply flow can improve conditions.
⠀
Its importance depends on how much of that flow becomes liquid and how buyers respond.
⠀
08 | UNLOCKED SUPPLY IS NOT CIRCULATING SUPPLY
⠀
World's official disclosures distinguish unlocked tokens from tokens in circulation.
⠀
An allocation can become transferable while remaining under an organization's control.
⠀
Tokens can then be distributed over time for different purposes.
⠀
That makes a single unlock percentage an incomplete picture of potential supply.
⠀
For investors, the useful monitoring includes treasury distributions, recipient balances, exchange-bound transfers, and changes in reported circulation.
⠀
An exchange transfer is not proof of a completed sale.
⠀
But it can change the immediate market context.
⠀
The correct approach follows actual movements.
⠀
It does not assume either that every unlock is sold or that retained allocations are irrelevant.
⠀
09 | TEN BILLION IS THE INITIAL FRAMEWORK
⠀
The whitepaper specifies an initial supply of 10 billion WLD.
⠀
Additional inflation can begin no earlier than July 24, 2038.
⠀
The default rate is zero.
⠀
Any future rate and allocation are subject to governance, with an annual limit of 1.5%.
⠀
That is different from a permanent, immutable 10 billion lifetime ceiling.
⠀
For the current investment horizon, the more immediate issue is distribution from the initial supply.
⠀
Only approximately 37.9% is classified as circulating in the quoted snapshot.
⠀
A long-term inflation provision and near-term circulating-supply growth are separate considerations.
⠀
Both need the correct timeframe.
⠀
10 | THE CHAIN AND VALUATION QUESTIONS
⠀
World Chain uses ETH as its native asset.
⠀
Payment conveniences involving WLD should not be confused with making WLD the underlying native gas asset.
⠀
Likewise, network transactions do not automatically create equivalent WLD purchases.
⠀
Using the initial 10 billion supply:
⠀
$0.50 WLD implies a $5B valuation.
$1.00 implies $10B.
$2.00 implies $20B.
$5.00 implies $50B.
$11.82 implies $118.2B.
⠀
These are initial-supply valuation illustrations, not price targets.
⠀
They show why returning to an old price requires more analysis than measuring the drawdown.
⠀
The denominator and circulating supply have changed.
⠀
The valuation needs demand capable of supporting them.
⠀
11 | THE BULL AND BEAR CASE
⠀
THE BULL CASE:
⠀
World ID becomes a useful verification layer.
⠀
Applications retain active verified users.
⠀
A working fee model attracts paying customers.
⠀
Protocol income produces measurable token demand.
⠀
And that demand grows faster than liquid supply.
⠀
THE BEAR CASE:
⠀
Enrollment produces limited repeat usage.
⠀
Applications resist fees or choose alternatives.
⠀
Hardware-based onboarding limits distribution.
⠀
User incentives support activity without establishing commercial demand.
⠀
And ongoing distributions outweigh the token's economic benefits.
⠀
A useful identity network can succeed operationally while its token remains a difficult investment.
⠀
The connection between the two must be demonstrated.
⠀
12 | THE FINAL VERDICT
⠀
World has an identifiable opportunity.
⠀
Human verification.
⠀
Identity credentials.
⠀
Application integrations.
⠀
And a proposed fee model connecting usage to WLD.
⠀
But the investment case remains conditional.
⠀
A roughly $1 billion market capitalization.
⠀
Approximately $2.65 billion against the initial supply.
⠀
Less than 40% of that supply classified as circulating.
⠀
And continuing daily unlocks alongside monetization that needs clearer evidence.
⠀
My assessment:
⠀
WLD is a proof-of-human commercialization thesis with a substantial supply-absorption test.
⠀
More verified people create network reach.
⠀
Repeated use demonstrates usefulness.
⠀
Paying applications establish commercial demand.
⠀
The active fee allocation determines how that demand benefits the token.
⠀
The decisive question is whether those benefits can grow faster than liquid supply.
⠀
A 97.8% drawdown does not answer it.
⠀
Neither does an AI headline.
⠀
Bookmark this analysis before the next identity and AI rotation.
⠀
Would you rather invest in the identity application, the verification infrastructure, or the associated token?
⠀
And what evidence would convince you that World ID adoption is becoming sustainable WLD demand?
⠀
Drop your view below.