Wall Street Closed Mixed as Investors Looked Past Nvidia’s Beat, Hawkish Fed Minutes & Anthropic IPO
Nvidia beat Wall Street’s numbers, guided above consensus, and still finished the day lower. Shares rose early on the report, then reversed. Hawkish Federal Reserve minutes and an Anthropic IPO that priced after the closing bell left the rest of the tape mixed and jumpy.
The minutes of the Fed’s October 27 to 28 meeting said almost all participants saw further rate hikes as likely appropriate, and the dollar climbed to a 19-month high. After the close, Anthropic priced its offering at $83 a share, above the $70 to $78 range it had marketed. The deal is roughly $81 billion, the largest IPO on record. Investors keep asking for proof that the AI trade has staying power, and this week handed them evidence for both answers.
A Mixed Tape With a Hole in the Dow
The Dow Jones Industrial Average lost 561.25 points, or 1.11%, to close at 50,198.17, its lowest finish in about three months. The S&P 500 slipped 0.23% to 7,323.63. That made five straight losing sessions, the longest run since June. The Nasdaq Composite rose 0.42% to 24,429.88, and the Russell 2000 gained roughly half a percent.
Nvidia Beats, Then Fades
Third-quarter revenue came in at $115.8 billion, up 103% from a year earlier and well above the $109.1 billion LSEG estimate. Nvidia guided the fourth quarter to $130 billion, plus or minus 3%, against a consensus of $125.1 billion. The stock still closed down 2.89% at $150.96.
Leadership is part of the story. Jensen Huang resigned as CEO on November 12, and CFO Colette Kress is running the company on an interim basis while the board looks for a successor. Analysts quoted by CNBC expect that uncertainty to linger even after a clean quarter.
Anthropic’s Orbit Gets a Bid
Anthropic proxies caught buyers ahead of the debut. Amazon rose 3.82% to $267.74, and Alphabet’s Class A shares (GOOGL) gained 0.58% to $282.44. Both companies hold direct stakes through their own investments. Amazon agreed in April to invest up to $25 billion, and Google committed up to $40 billion days later.
AMD gained about 5% and Broadcom about 3.7%, while the wider chip group finished mixed. Broadcom’s link to Anthropic is concrete. In late October, Bank of America, Blackstone, Citi and Morgan Stanley committed $63 billion to a special purpose vehicle that buys Broadcom chips and networking gear and leases them to Anthropic.
A Federal Warning Lights Up Cyber Stocks
Cybersecurity names were among the Nasdaq’s biggest winners after the Cybersecurity and Infrastructure Security Agency urged organizations to patch a critical Java flaw. The bug, nicknamed Java4Shell, can let an attacker run code remotely without logging in. Palo Alto Networks (PANW) jumped nearly 10%, CrowdStrike (CRWD) rose about 8%, and Fortinet (FTNT) gained roughly 6%. Palo Alto reported results after the bell and raised its annual forecast, so the run-up came before the numbers.
Quiet Support, Loud Small Caps
Mega-caps cushioned the AI-infrastructure pullback. Tesla (TSLA) gained 0.95% to $383.72, Microsoft (MSFT) added 0.40% to $508.29, and Apple (AAPL) edged up 0.15% to $352.45.
Smaller-cap names produced the louder moves. Midera Food Processing (MFP), the food-equipment maker spun out of Middleby in July, was up about 11.5% at midday, per Benzinga, after Baird raised its price target to $43 from $40 and kept a neutral rating. The company had reported a third-quarter beat and raised its full-year guidance a day earlier.
Bullish (BLSH) climbed roughly 5% to about $21 by midday. Adjusted third-quarter revenue of $84.4 million beat estimates. The board also approved a buyback of up to $300 million.
Target Finds Its Traffic
Target (TGT) closed up 4.01% at $165.93 after spiking as much as 7% earlier in the session. Third-quarter net sales rose 7.1% to $27.07 billion, the retailer’s best growth since the fourth quarter of 2021. Comparable sales climbed 5.6%, powered by a 5% rise in comparable traffic.
Price cuts helped. Target trimmed prices on nearly 2,000 more items during the quarter, and it raised its full-year sales growth outlook to about 6%, one point higher than its previous guide. One caveat on the earnings line: about 50 cents of the $2.65 per share came from tariff refunds.
Take-Two Trades the Launch
Take-Two Interactive (TTWO) rose 6.22% to close at $216.61 as the first Grand Theft Auto VI reviews landed ahead of the November 19 release. Critics were effusive, and estimates put digital preorders above $1.5 billion. The stock still sits about 15% lower for the year after a stretch of delays and volatility.
UnitedHealth Takes the Dow Down
UnitedHealth fell about 10% on Wednesday, its second straight drop, after the Centers for Medicare and Medicaid Services proposed tougher audits of Medicare Advantage insurers. In a price-weighted index where the stock carries roughly 4.3% of the weight, that hurts. Caterpillar lost more than 2%.
Oil Slips, Drags Energy Stocks Down
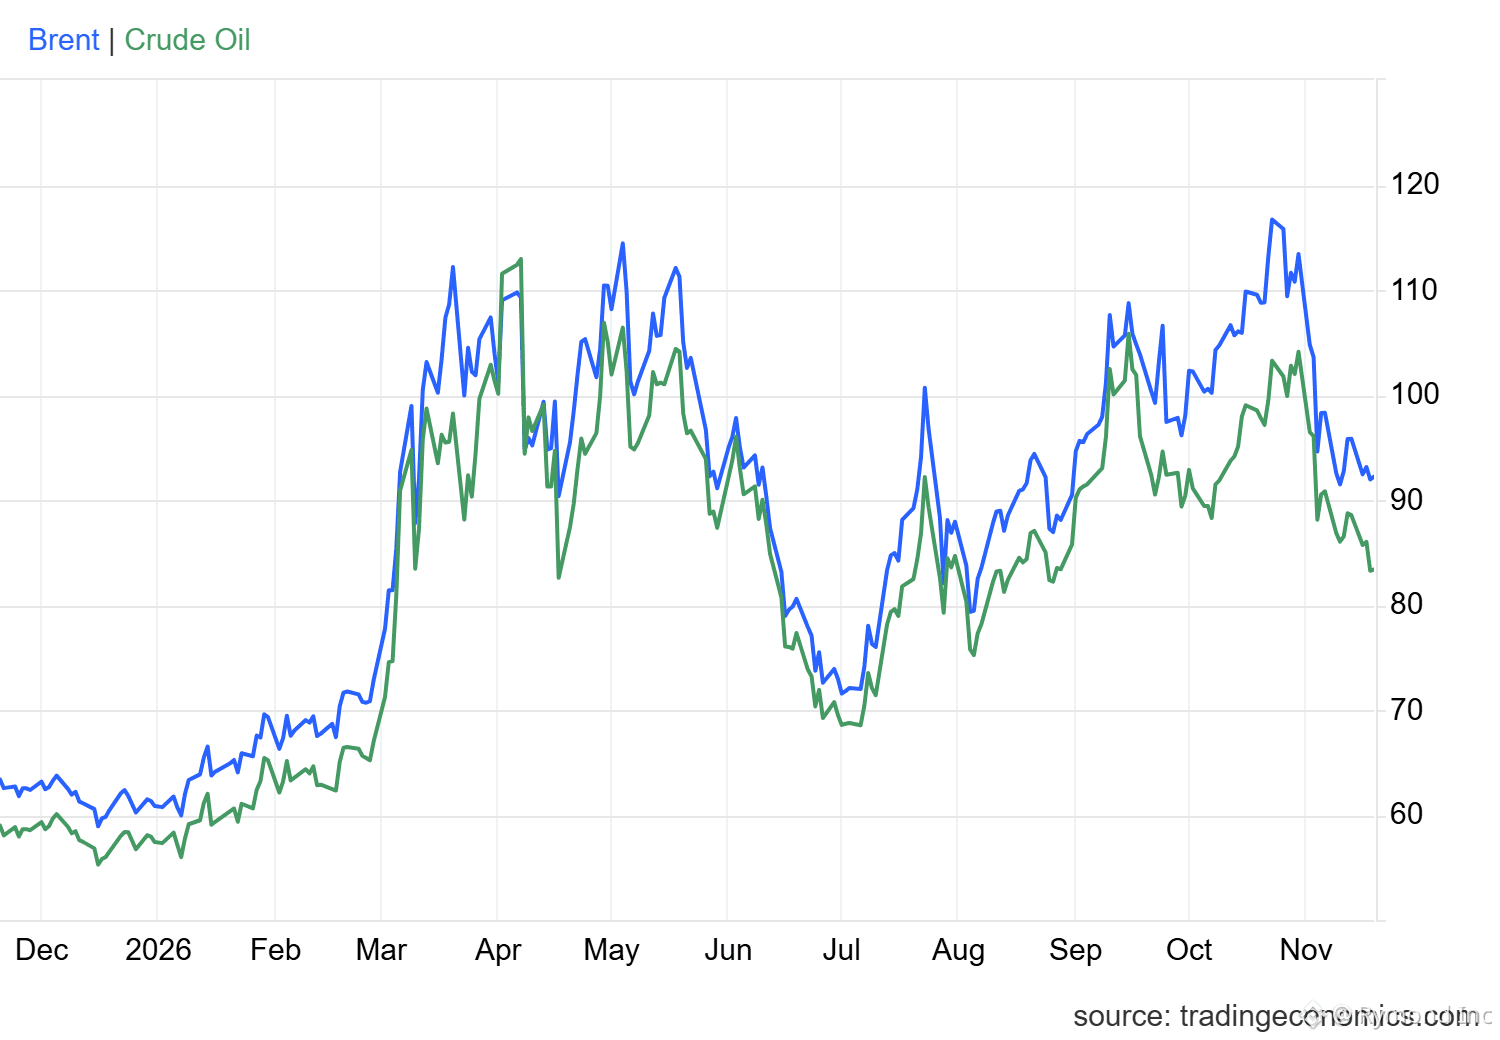
WTI futures fell more than 4% to $82.19 a barrel in afternoon trading, and Brent slid more than 2% to $90.83. US-Iran fighting and attacks on shipping near the Strait of Hormuz kept the drop from going deeper.
ExxonMobil and Chevron each dropped more than 3% in afternoon trading, and ConocoPhillips and EOG Resources lost more than 2%. Oil dropped alongside after the EIA reported larger-than-expected builds in US crude and gasoline stockpiles.
Sector Performance Summary
Best-Performing Sectors
Five of the S&P 500’s 11 sectors finished higher, and Consumer Discretionary led with a 2.24% gain on the back of retail earnings. Target’s comparable sales rose 5.6% against 3.8% expected, driven by traffic rather than price, and TJX raised its full-year comp forecast, with its shares jumping at the open.
Communication Services (+0.39%) and Utilities (+0.26%) edged higher with no single dominant driver. Disney extended its run after Tuesday’s earnings beat, and slightly lower Treasury yields gave rate-sensitive utilities a small lift.
Worst-Performing Sectors
Energy fell 3.51%, the steepest drop, and crude was the cause. WTI settled 3.2% lower near $83 after inventory data fed expectations of a supply surplus, and Chevron lost nearly 4%. It was a commodity move felt across the sector, not company news.
Health Care slid 2.18%, and at a 10% weight it erased most of Consumer Discretionary’s contribution. The trigger was CMS’s CRUSH anti-fraud proposal, released November 16 and targeting nearly $90 billion in federal savings. It would revive extrapolated Medicare Advantage audits reaching back to 2018. UnitedHealth, already down about 5% Tuesday, lost another 10% and accounted for nearly half the Dow’s point drop.
Materials fell 1.19% as metals buckled under a firmer dollar. Gold, already at a one-year low on yields and dollar strength, slid further as the dollar index touched a 19-month high and copper and silver fell too.
Thursday brings the next test. Anthropic is set to begin trading on the Nasdaq under the ticker ANT after pricing above its range, and the Fed meets again December 15 and 16 with a rate hike openly on the table. A strong debut would hand the AI trade the fresh evidence it went looking for this week. A weak one would make Nvidia’s fade look like an early warning.