
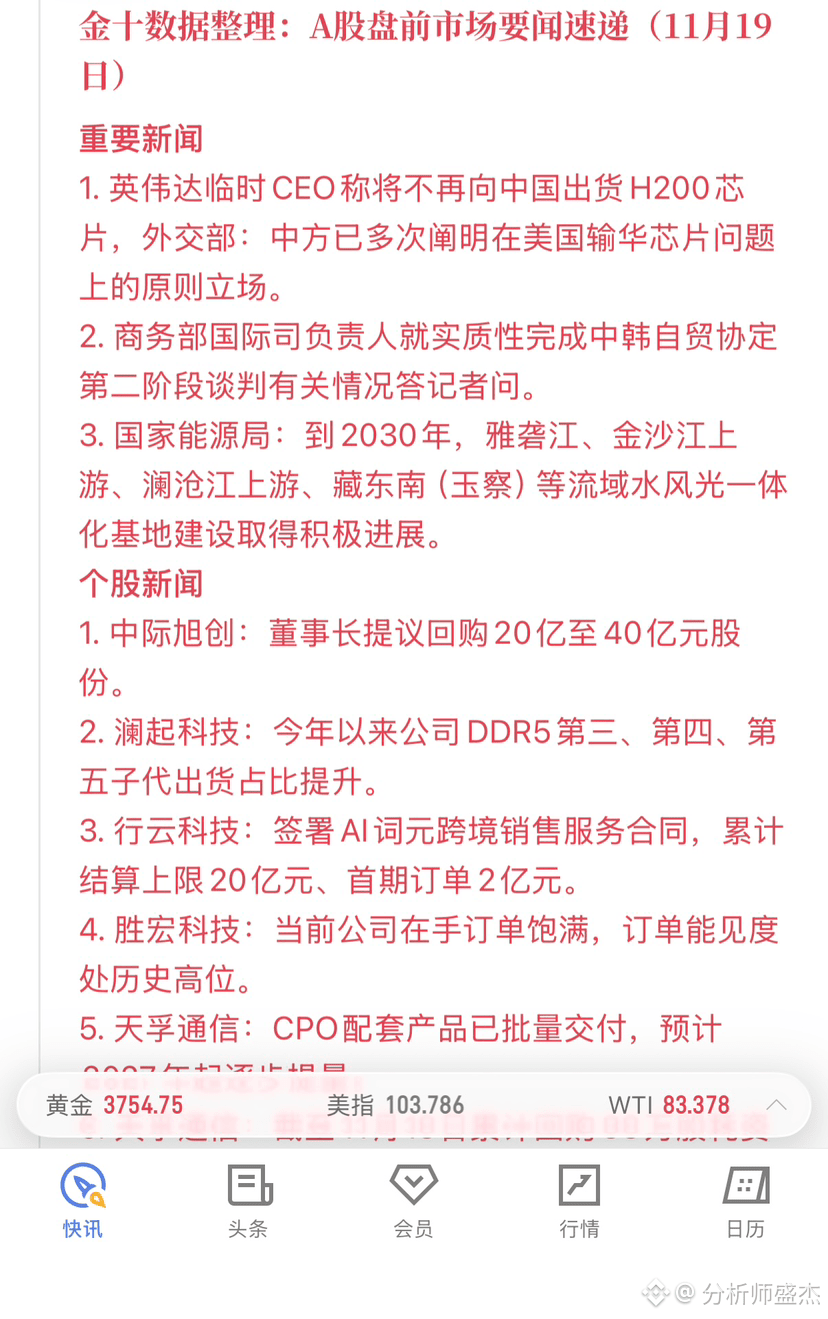
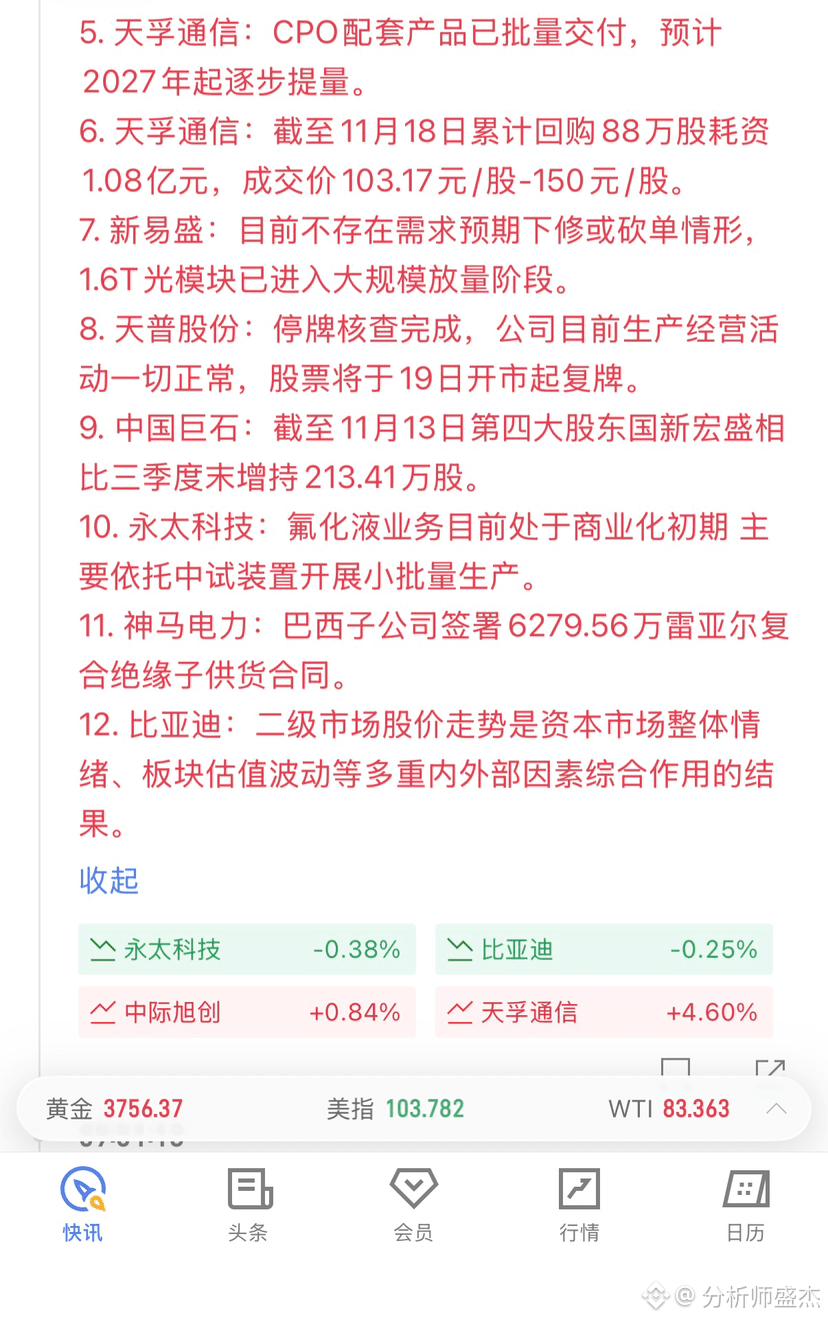
Ahead of the market open on November 19, domestic and international developments are converging. Overseas, restrictions on Nvidia H200 shipments to China, alongside the Bank of Japan’s comments on inflation, are affecting sentiment toward semiconductors and risk assets. Domestically, the second-phase China–South Korea free trade negotiations have concluded, while the National Energy Administration’s integrated hydro, wind, and solar planning is supporting new-energy infrastructure. At the company level, Zhongji Innolight’s proposed buyback worth around 4 billion, Tianfu Communication’s CPO deliveries alongside a buyback, Eoptolink’s ramp-up in 1.6T products, Montage Technology’s DDR5 upgrades, and strong orders at Victory Giant all point to solid fundamentals across the AI computing hardware chain. Ahead of the open, gold is at 3756, the U.S. Dollar Index at 103.78, and WTI at 83.36. Strategically, watch how the computing hardware chain holds up after a higher open, and how the hedge of domestic chip substitution performs.#英伟达财报大超预期,Q4营收展望1300亿美元
Join global crypto users on Binance Square
⚡️ Get latest and useful information about crypto.
💬 Trusted by the world’s largest crypto exchange.
👍 Discover real insights from verified creators.
Email / Phone number