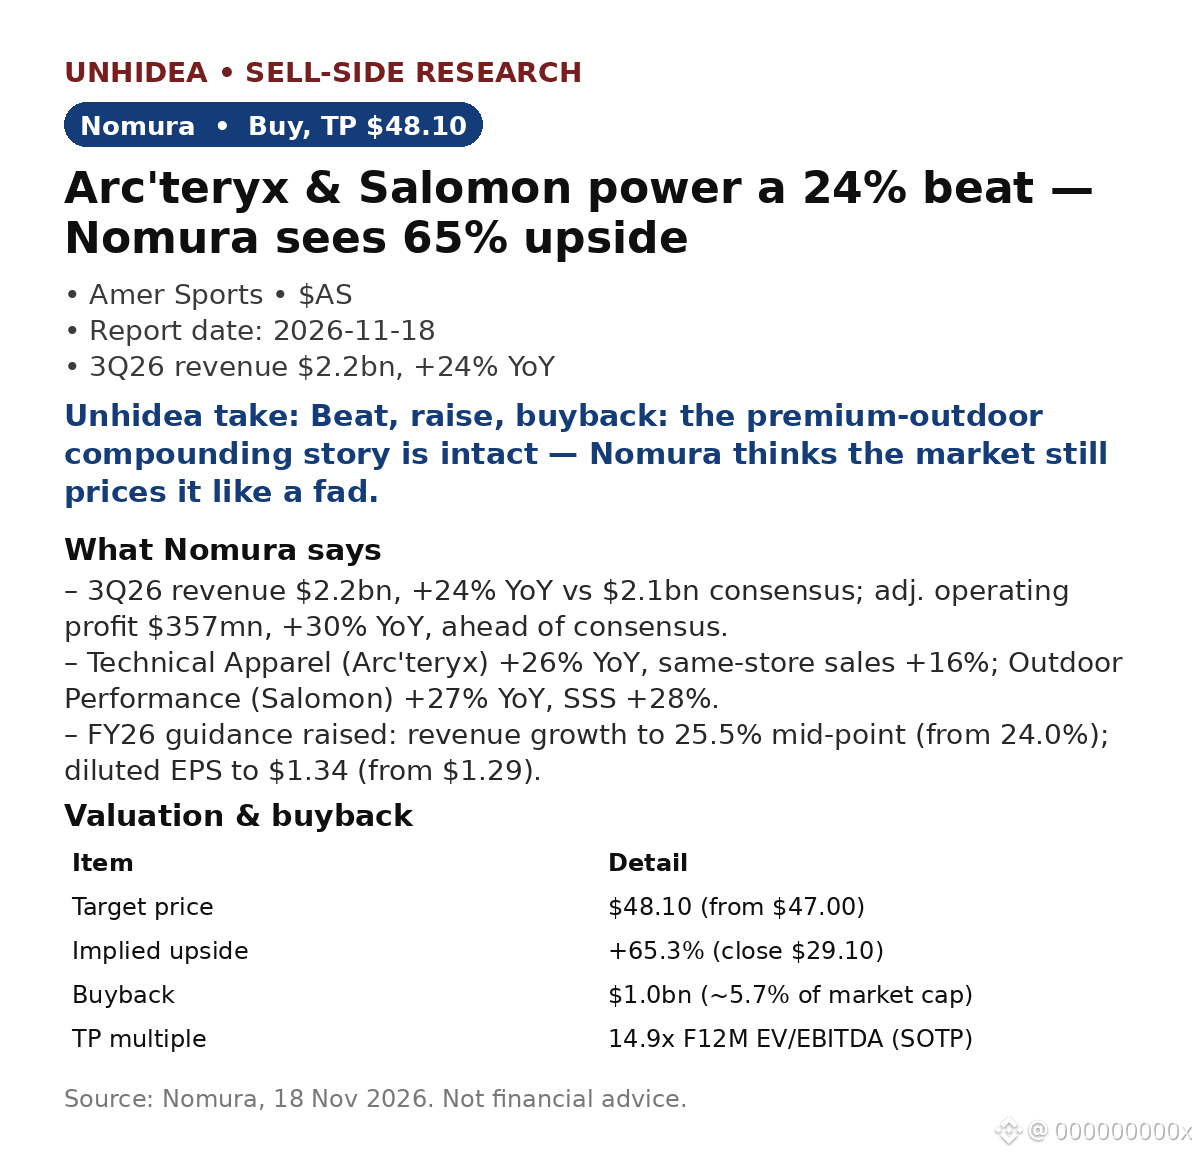
$AS: Arc'teryx & Salomon power a 24% beat — Nomura reiterates Buy, TP $48.10 (+65% upside)
- 3Q26 revenue $2.2bn, +24% YoY, vs $2.1bn consensus. Adj. operating profit $357mn, +30% YoY, ahead of consensus. Adj. EPS $0.42 vs $0.35 expected.
- Technical Apparel (Arc'teryx) +26% YoY, same-store sales +16%; Outdoor Performance (Salomon) +27% YoY, SSS +28%. Ball & Racquet +12%, but margin fell 2.1pp on Wilson investment.
- Guidance raised: FY26 revenue growth to 25.5% (from 24.0%); diluted EPS to $1.34 (from $1.29). A $1bn buyback (~5.7% of market cap) adds a floor.
- Shares +3.9% to $30.24 on 17 Nov while the S&P fell ~1%, then +2.3% to $30.95 on 18 Nov (post-report market data). SOTP target implies 14.9x forward EV/EBITDA.
Unhidea take: two brands growing 26–27% with DTC pricing power, plus a buyback floor — the market still prices Amer like a cyclical retailer; Nomura's 65% upside says brand platform.
Unhidea take: the Street is split — UBS cut its target to $56, Nomura holds $48.10, both Buy. That gap is the debate: what multiple for a 25% grower at 59.3% gross margin?
Risks: Wilson drag, DTC execution, tariffs/FX, premium-consumer slowdown.
Source: Nomura, 18 Nov 2026. Post-report prices: Finnhub/market data. Not financial advice.
- 3Q26 revenue $2.2bn, +24% YoY, vs $2.1bn consensus. Adj. operating profit $357mn, +30% YoY, ahead of consensus. Adj. EPS $0.42 vs $0.35 expected.
- Technical Apparel (Arc'teryx) +26% YoY, same-store sales +16%; Outdoor Performance (Salomon) +27% YoY, SSS +28%. Ball & Racquet +12%, but margin fell 2.1pp on Wilson investment.
- Guidance raised: FY26 revenue growth to 25.5% (from 24.0%); diluted EPS to $1.34 (from $1.29). A $1bn buyback (~5.7% of market cap) adds a floor.
- Shares +3.9% to $30.24 on 17 Nov while the S&P fell ~1%, then +2.3% to $30.95 on 18 Nov (post-report market data). SOTP target implies 14.9x forward EV/EBITDA.
Unhidea take: two brands growing 26–27% with DTC pricing power, plus a buyback floor — the market still prices Amer like a cyclical retailer; Nomura's 65% upside says brand platform.
Unhidea take: the Street is split — UBS cut its target to $56, Nomura holds $48.10, both Buy. That gap is the debate: what multiple for a 25% grower at 59.3% gross margin?
Risks: Wilson drag, DTC execution, tariffs/FX, premium-consumer slowdown.
Source: Nomura, 18 Nov 2026. Post-report prices: Finnhub/market data. Not financial advice.