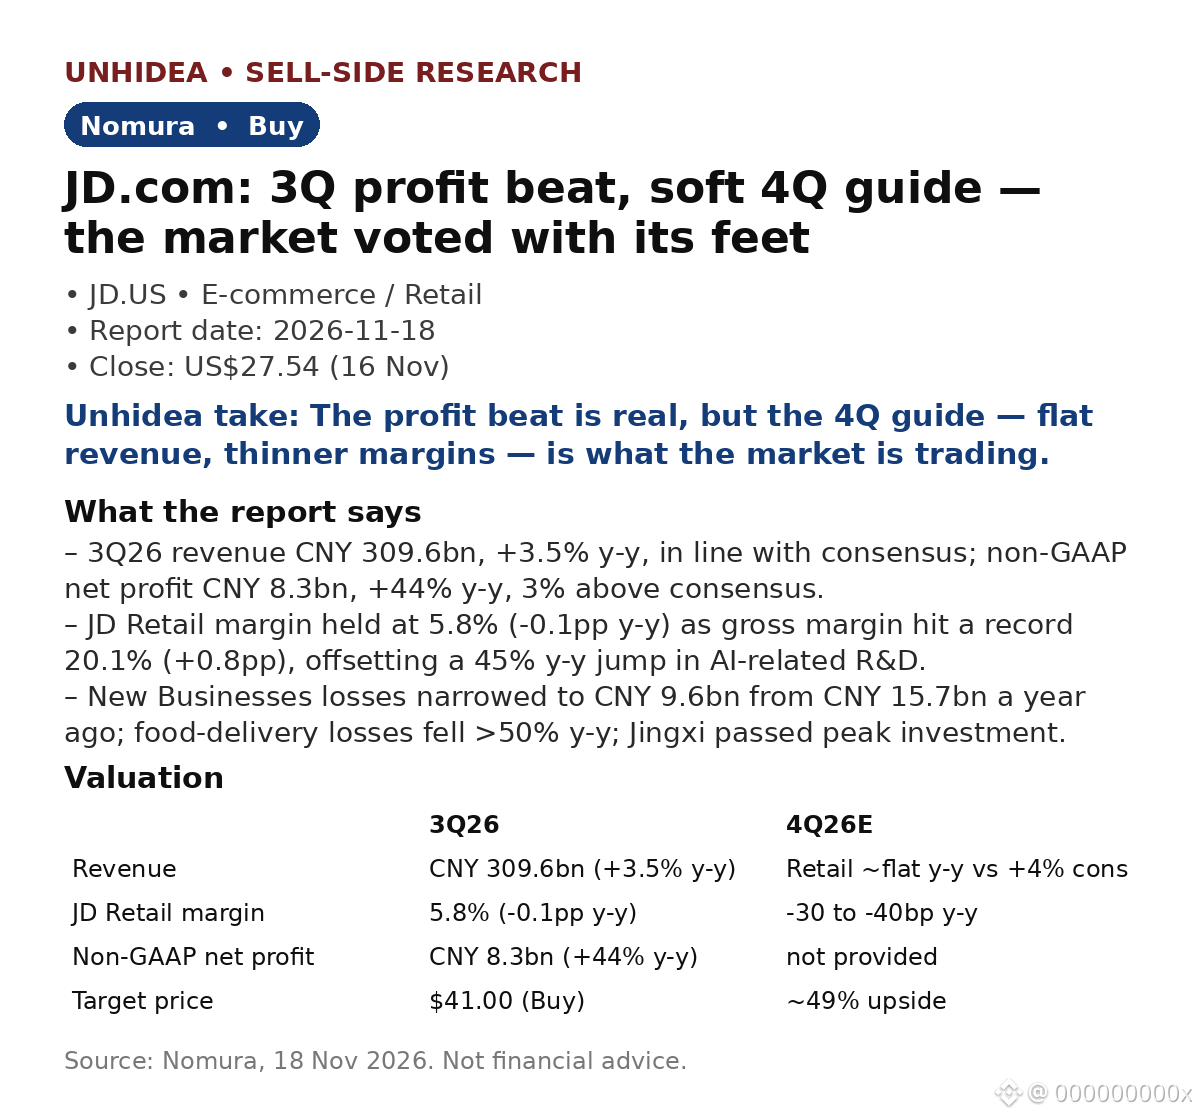
JD.com ($JD): Nomura stays Buy at $41 — a 3Q profit beat, a soft 4Q guide, and a market that voted with its feet
- 3Q26 revenue CNY 309.6bn, +3.5% y-y, in line; non-GAAP net profit CNY 8.3bn, +44% y-y, 3% above consensus; non-GAAP op profit CNY 7.3bn, 15% above consensus.
- JD Retail held a 5.8% margin (-0.1pp y-y); gross margin hit a record 20.1% (+0.8pp), offsetting a 45% y-y jump in AI R&D.
- New Businesses losses narrowed to CNY 9.6bn from CNY 15.7bn a year ago; food-delivery losses fell >50% y-y.
- But 4Q looks soft: JD Retail revenue seen flat y-y vs +4% consensus; margin -30 to -40bp y-y vs -10bp expected.
- Valuation: the $41 target implies 8.5x FY27E P/E vs 5.7x now — ~49% upside vs the $27.54 close on 16 Nov.
Unhidea take: the beat is real but backward-looking — the market is pricing the 4Q guide, not the 3Q print.
Unhidea take: JD's story is now margin discipline, not growth — shrinking losses matter more than a flat top line.
Market reaction: shares fell 7.7% on 17 Nov to $25.43, then 2.0% more on 18 Nov to $24.92 (Finnhub).
Risks: weak consumption; competition; CECONYOMY integration (deal closed 12 Nov).
Source: Nomura, 18 Nov 2026. Not financial advice.
- 3Q26 revenue CNY 309.6bn, +3.5% y-y, in line; non-GAAP net profit CNY 8.3bn, +44% y-y, 3% above consensus; non-GAAP op profit CNY 7.3bn, 15% above consensus.
- JD Retail held a 5.8% margin (-0.1pp y-y); gross margin hit a record 20.1% (+0.8pp), offsetting a 45% y-y jump in AI R&D.
- New Businesses losses narrowed to CNY 9.6bn from CNY 15.7bn a year ago; food-delivery losses fell >50% y-y.
- But 4Q looks soft: JD Retail revenue seen flat y-y vs +4% consensus; margin -30 to -40bp y-y vs -10bp expected.
- Valuation: the $41 target implies 8.5x FY27E P/E vs 5.7x now — ~49% upside vs the $27.54 close on 16 Nov.
Unhidea take: the beat is real but backward-looking — the market is pricing the 4Q guide, not the 3Q print.
Unhidea take: JD's story is now margin discipline, not growth — shrinking losses matter more than a flat top line.
Market reaction: shares fell 7.7% on 17 Nov to $25.43, then 2.0% more on 18 Nov to $24.92 (Finnhub).
Risks: weak consumption; competition; CECONYOMY integration (deal closed 12 Nov).
Source: Nomura, 18 Nov 2026. Not financial advice.