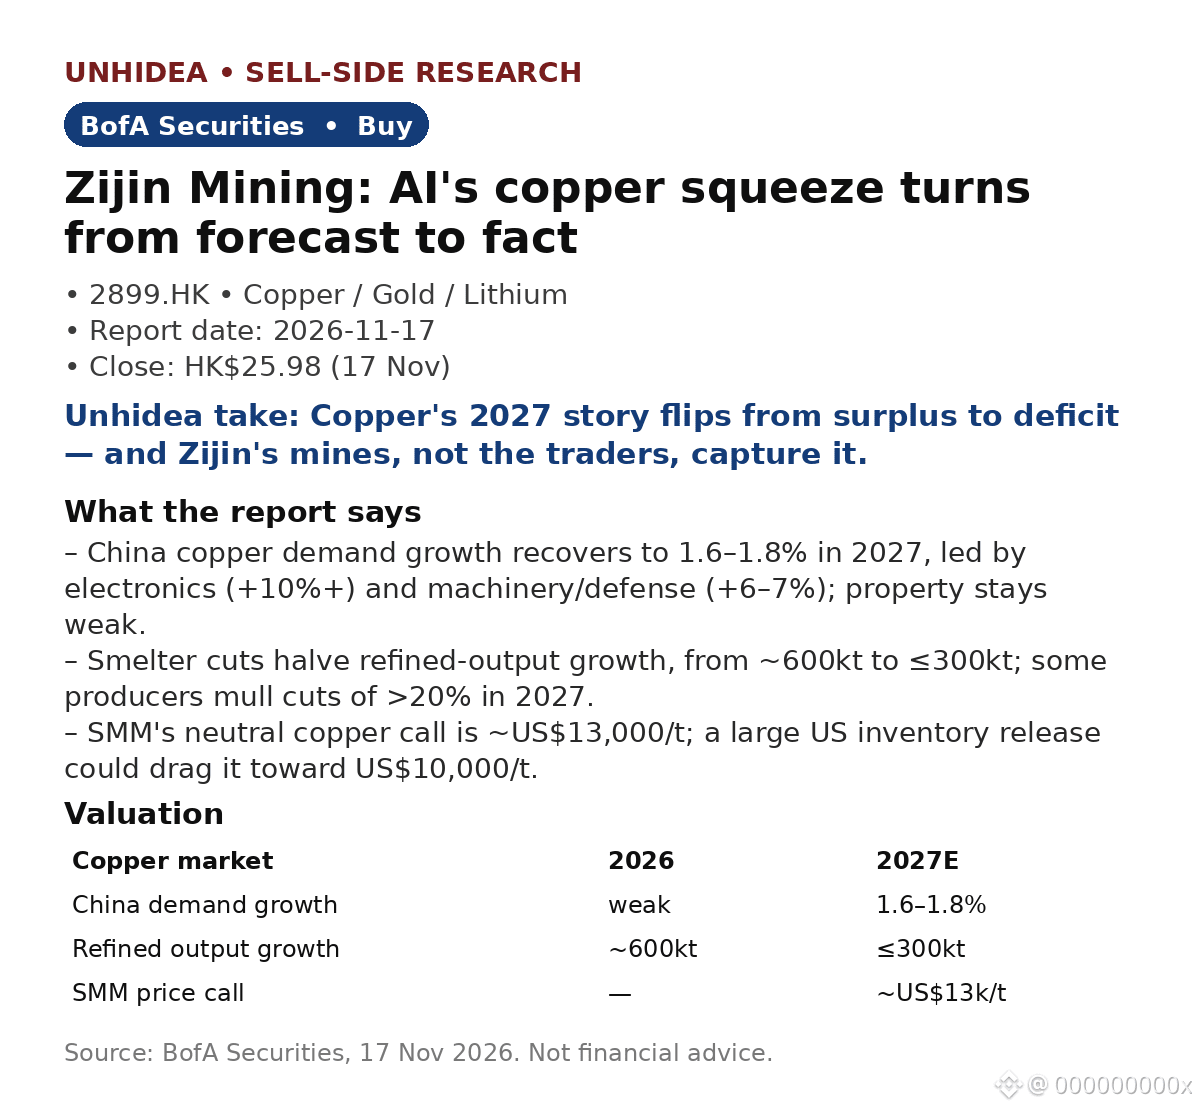
Zijin Mining (2899.HK): BofA stays Buy — China copper demand recovers as smelters cut
- China copper demand growth recovers to 1.6–1.8% in 2027, led by electronics (+10%+) and machinery/defense (+6–7%); property still weak.
- Smelter cuts halve refined-output growth, ~600kt to ≤300kt; SMM's neutral call is ~US$13,000/t, US inventory releases a risk toward US$10,000/t.
- Zijin keeps 2026 guidance (excl. ~50kt Kamoa-Kakula losses); existing mines deliver 1.40–1.45mnt in 2028 vs 1.50mnt target; Africa adds 300kt+.
- AI infra is the kicker: M8 CCL demand triples, 2.5mn to 7.5mn/month by end-2027; InP is >70% of Yunnan Germanium's net profit at >65% margin, orders locked thru 2027.
- Zijin rated Buy, HK$25.98 close on 17 Nov; price objective not restated in this note.
Unhidea take: copper is AI's forgotten bottleneck — the market debates GPUs while the metal wiring every data center flips from surplus to deficit.
Unhidea take: Zijin's edge is volume growth into a deficit — it grows while smelters shrink; in a tight market, tonnes beat multiples.
Risks: weak macro; US inventory releases; Kamoa-Kakula disruption.
Source: BofA Securities, 17 Nov 2026. Not financial advice.
- China copper demand growth recovers to 1.6–1.8% in 2027, led by electronics (+10%+) and machinery/defense (+6–7%); property still weak.
- Smelter cuts halve refined-output growth, ~600kt to ≤300kt; SMM's neutral call is ~US$13,000/t, US inventory releases a risk toward US$10,000/t.
- Zijin keeps 2026 guidance (excl. ~50kt Kamoa-Kakula losses); existing mines deliver 1.40–1.45mnt in 2028 vs 1.50mnt target; Africa adds 300kt+.
- AI infra is the kicker: M8 CCL demand triples, 2.5mn to 7.5mn/month by end-2027; InP is >70% of Yunnan Germanium's net profit at >65% margin, orders locked thru 2027.
- Zijin rated Buy, HK$25.98 close on 17 Nov; price objective not restated in this note.
Unhidea take: copper is AI's forgotten bottleneck — the market debates GPUs while the metal wiring every data center flips from surplus to deficit.
Unhidea take: Zijin's edge is volume growth into a deficit — it grows while smelters shrink; in a tight market, tonnes beat multiples.
Risks: weak macro; US inventory releases; Kamoa-Kakula disruption.
Source: BofA Securities, 17 Nov 2026. Not financial advice.